1
Ram P. Sah,
Nepal Agriculture Research Council (NARC)
Singh Durbar Plaza, Kathmandu
CONSTRAINTS TO SEED
ADOPTION, MARKET AND TRADE
IN NEPAL
Nepal: National Seed System
National Seed
System
Public Institutions
•MOAD, NARC, NSB, DOA, DADO, SQCC,
UAF, Gene banks, Biotech
International
Collaborators
• CGIAR, Donors, INGOs, Bilat
eral /Multilateral
Projects, Multinationals,
Farmers Communities
FGs, HHs, CBSP, Social Activists
Private Sector
SEAN, FNCCI/AEC, Seed
Co, Agrovets, Seed importers
0
500
1000
1500
2000
2500
3000
3500
0
1000
2000
3000
4000
5000
6000
7000
8000
9000
10000
1991/92 1995/96 2000/01 2005/06 2010/11 2011/12
Area('000Ha),Production('000Mt)&Yield(Kg/Ha)
Year
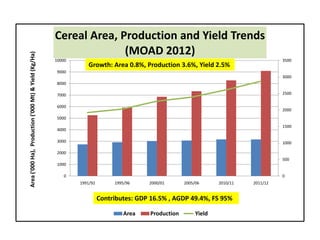
Cereal Area, Production and Yield Trends
(MOAD 2012)
Area Production Yield
Growth: Area 0.8%, Production 3.6%, Yield 2.5%
Contributes: GDP 16.5% , AGDP 49.4%, FS 95%
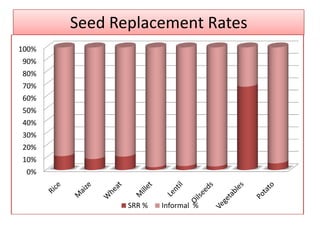
Seed Replacement Rates
0%
10%
20%
30%
40%
50%
60%
70%
80%
90%
100%
SRR % Informal %
-1
0
1
2
3
4
5
6
7
1999/00 2000/01 2001/02 2002/03 2003/04 2004/05 2005/06 2006/07 2007/08 2008/09 2009/10 2010/11 2011/12 2012/13
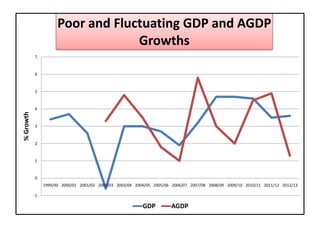
%Growth Poor and Fluctuating GDP and AGDP
Growths
GDP AGDP
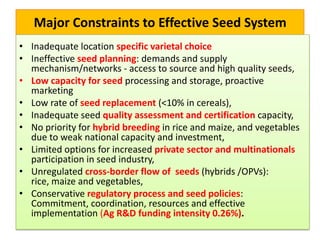
Major Constraints to Effective Seed System
• Inadequate location specific varietal choice
• Ineffective seed planning: demands and supply
mechanism/networks - access to source and high quality seeds,
• Low capacity for seed processing and storage, proactive
marketing
• Low rate of seed replacement (<10% in cereals),
• Inadequate seed quality assessment and certification capacity,
• No priority for hybrid breeding in rice and maize, and vegetables
due to weak national capacity and investment,
• Limited options for increased private sector and multinationals
participation in seed industry,
• Unregulated cross-border flow of seeds (hybrids /OPVs):
rice, maize and vegetables,
• Conservative regulatory process and seed policies:
Commitment, coordination, resources and effective
implementation (Ag R&D funding intensity 0.26%).
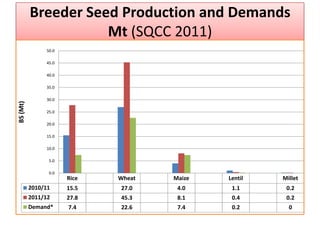
Breeder Seed Production and Demands
Mt (SQCC 2011)
Rice Wheat Maize Lentil Millet
2010/11 15.5 27.0 4.0 1.1 0.2
2011/12 27.8 45.3 8.1 0.4 0.2
Demand* 7.4 22.6 7.4 0.2 0
0.0
5.0
10.0
15.0
20.0
25.0
30.0
35.0
40.0
45.0
50.0
BS(Mt)
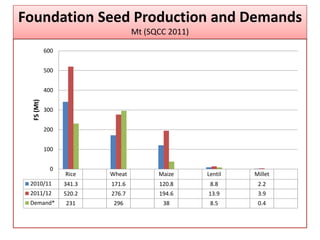
Rice Wheat Maize Lentil Millet
2010/11 341.3 171.6 120.8 8.8 2.2
2011/12 520.2 276.7 194.6 13.9 3.9
Demand* 231 296 38 8.5 0.4
0
100
200
300
400
500
600
FS(Mt)
Foundation Seed Production and Demands
Mt (SQCC 2011)
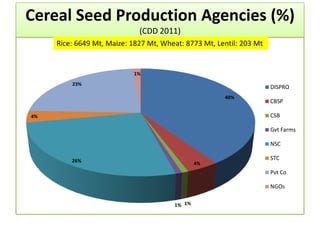
Cereal Seed Production Agencies (%)
(CDD 2011)
40%
4%
1%1%
26%
4%
23%
1%
DISPRO
CBSP
CSB
Gvt Farms
NSC
STC
Pvt Co
NGOs
Rice: 6649 Mt, Maize: 1827 Mt, Wheat: 8773 Mt, Lentil: 203 Mt
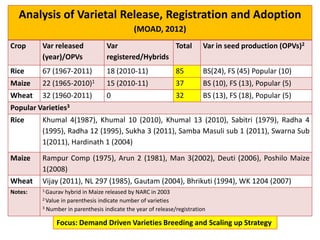
Analysis of Varietal Release, Registration and Adoption
(MOAD, 2012)
Crop Var released
(year)/OPVs
Var
registered/Hybrids
Total Var in seed production (OPVs)2
Rice 67 (1967-2011) 18 (2010-11) 85 BS(24), FS (45) Popular (10)
Maize 22 (1965-2010)1 15 (2010-11) 37 BS (10), FS (13), Popular (5)
Wheat 32 (1960-2011) 0 32 BS (13), FS (18), Popular (5)
Popular Varieties3
Rice Khumal 4(1987), Khumal 10 (2010), Khumal 13 (2010), Sabitri (1979), Radha 4
(1995), Radha 12 (1995), Sukha 3 (2011), Samba Masuli sub 1 (2011), Swarna Sub
1(2011), Hardinath 1 (2004)
Maize Rampur Comp (1975), Arun 2 (1981), Man 3(2002), Deuti (2006), Poshilo Maize
1(2008)
Wheat Vijay (2011), NL 297 (1985), Gautam (2004), Bhrikuti (1994), WK 1204 (2007)
Notes: 1 Gaurav hybrid in Maize released by NARC in 2003
2 Value in parenthesis indicate number of varieties
3 Number in parenthesis indicate the year of release/registration
Focus: Demand Driven Varieties Breeding and Scaling up Strategy
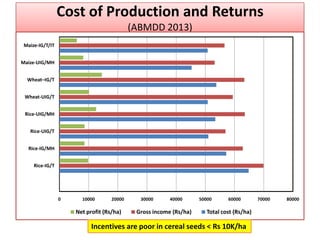
Cost of Production and Returns
(ABMDD 2013)
0 10000 20000 30000 40000 50000 60000 70000 80000
Rice-IG/T
Rice-IG/MH
Rice-UIG/T
Rice-UIG/MH
Wheat-UIG/T
Wheat–IG/T
Maize-UIG/MH
Maize-IG/T/IT
Net profit (Rs/ha) Gross income (Rs/ha) Total cost (Rs/ha)
Incentives are poor in cereal seeds < Rs 10K/ha
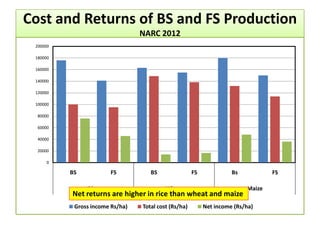
Cost and Returns of BS and FS Production
NARC 2012
0
20000
40000
60000
80000
100000
120000
140000
160000
180000
200000
BS FS BS FS Bs FS
Rice Wheat Maize
Gross income Rs/ha) Total cost (Rs/ha) Net income (Rs/ha)
Net returns are higher in rice than wheat and maize
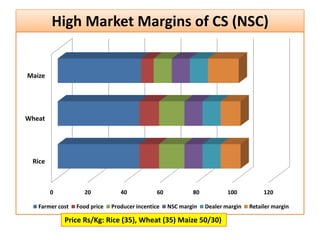
High Market Margins of CS (NSC)
0 20 40 60 80 100 120
Rice
Wheat
Maize
Farmer cost Food price Producer incentice NSC margin Dealer margin Retailer margin
Price Rs/Kg: Rice (35), Wheat (35) Maize 50/30)
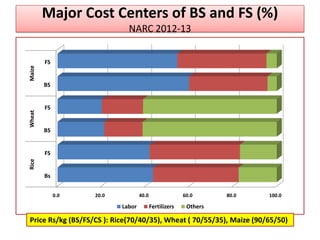
Major Cost Centers of BS and FS (%)
NARC 2012-13
0.0 20.0 40.0 60.0 80.0 100.0
Bs
FS
BS
FS
BS
FS
RiceWheatMaize
Labor Fertilizers Others
Price Rs/kg (BS/FS/CS ): Rice(70/40/35), Wheat ( 70/55/35), Maize (90/65/50)
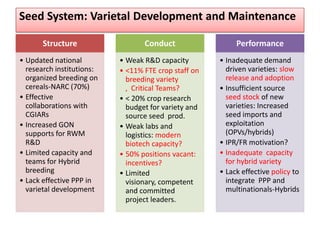
Seed System: Varietal Development and Maintenance
Structure
• Updated national
research institutions:
organized breeding on
cereals-NARC (70%)
• Effective
collaborations with
CGIARs
• Increased GON
supports for RWM
R&D
• Limited capacity and
teams for Hybrid
breeding
• Lack effective PPP in
varietal development
Conduct
• Weak R&D capacity
• <11% FTE crop staff on
breeding variety
, Critical Teams?
• < 20% crop research
budget for variety and
source seed prod.
• Weak labs and
logistics: modern
biotech capacity?
• 50% positions vacant:
incentives?
• Limited
visionary, competent
and committed
project leaders.
Performance
• Inadequate demand
driven varieties: slow
release and adoption
• Insufficient source
seed stock of new
varieties: Increased
seed imports and
exploitation
(OPVs/hybrids)
• IPR/FR motivation?
• Inadequate capacity
for hybrid variety
• Lack effective policy to
integrate PPP and
multinationals-Hybrids
Seed System: Seed Multiplication
Structure
•Modest R&D network for
seeds: PPP
•Weak integration between
varietal development and
seed multiplication chains
• Huge labor cost followed by
fertilizers and tillage, and
the net returns are low (<Rs
10K/ha)
•Weak infrastructure, and
markets: both public and
private sectors
•Lack updated technical staff
and capacity: small size of
industry
Conduct
• Mismatch of BS-FS-
CS/IS to address the
farmers’ demands
• New varieties from cross
border is coming on big
way that distort internal
seed demands and
supply
• Non compliance of
contract agreements:
Policy implementation
• Limited investment in
seed multiplication, cereal
seed production less
attractive:
• No policy and program for
Buffer stock management
Performance
• Foundation seeds are
being used as CS/IS seed
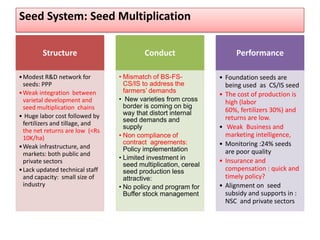
• The cost of production is
high (labor
60%, fertilizers 30%) and
returns are low.
• Weak Business and
marketing intelligence,
• Monitoring :24% seeds
are poor quality
• Insurance and
compensation : quick and
timely policy?
• Alignment on seed
subsidy and supports in :
NSC and private sectors
Seed System: Seed Marketing and Trade
Structure
• Inadequate seed
marketing
studies, intelligenc
e
• Poor Business
enterprise:
capacity and
investment in
marketing research
• Infrastructure and
labs
• Weak structure
and initiatives for
scaling-up superior
varieties, registere
d hybrids
Conduct
• Updated seed
Acts, Regulations and
Guidelines : Seed
Vision 2025
• Varietal
Registration, Contract
Farming, Compensatio
n, IPR and FR
Bill, promote PPP ??
• Lack commitment
• High tariffs and
bureaucratic delays in
export markets
• Cross border trade of
seeds:
formal/informal
Performance
• Uncontrolled flow of
exotic seeds
• Quality seeds and
varieties
• Low returns and B/C
ratio-less incentives
• Unregistered
varieties of OPVs and
hybrids
• Inadequate
performance
monitoring and
initiatives to promote
superior varieties
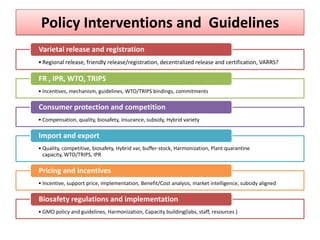
Policy Interventions and Guidelines
•Regional release, friendly release/registration, decentralized release and certification, VARRS?
Varietal release and registration
• Incentives, mechanism, guidelines, WTO/TRIPS bindings, commitments
FR , IPR, WTO, TRIPS
• Compensation, quality, biosafety, insurance, subsidy, Hybrid variety
Consumer protection and competition
• Quality, competitive, biosafety, Hybrid var, buffer-stock, Harmonization, Plant quarantine
capacity, WTO/TRIPS, IPR
Import and export
• Incentive, support price, implementation, Benefit/Cost analysis, market intelligence, subsidy aligned
Pricing and incentives
• GMO policy and guidelines, Harmonization, Capacity building(labs, staff, resources )
Biosafety regulations and implementation
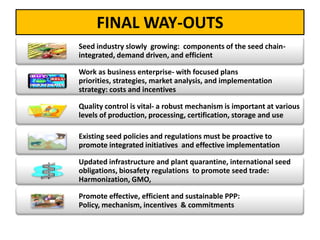
FINAL WAY-OUTS
Seed industry slowly growing: components of the seed chain-
integrated, demand driven, and efficient
Work as business enterprise- with focused plans
priorities, strategies, market analysis, and implementation
strategy: costs and incentives
Quality control is vital- a robust mechanism is important at various
levels of production, processing, certification, storage and use
Existing seed policies and regulations must be proactive to
promote integrated initiatives and effective implementation
Updated infrastructure and plant quarantine, international seed
obligations, biosafety regulations to promote seed trade:
Harmonization, GMO,
Promote effective, efficient and sustainable PPP:
Policy, mechanism, incentives & commitments
The seed sector in Nepal- Ram Sah