Disinvestment & payback period 
Presented by 
SAI KIRAN.B 
(12NA1E0036)
Introduction 
Investment and disinvestment are two sides of 
the same coin. Investment refers to conversion of 
money or cash into securities, debentures, bonds 
or any other claims on money. At the same time, 
disinvestment invloves the conversion of money 
claims or securities into money or cash.
Disinvestment DEFINITION 
“The action of an organisation or 
government selling or liquidating 
an asset or subsidiary”
Objectives of Disinvestment 
 To reduce the financial burden on 
government 
 To improve public finances 
 To introduce, competition and market 
discipline 
 To increase growth of the firm 
 To encourage wider share of ownership
Reasons for Disinvestment 
• To meet fiscal deficit 
• Expansion or diversification of the firm 
• To repayment of government debts 
• Implementation of government plan 
• PSU's give negative rate of return on 
capital
Background of Disinvestment 
The Indian economy had virtually embraced 
bankruptcy during the period of 1980-92. 
In 1991, there was 236 operating public sector 
undertakings, of which only 123 were profit making. 
The top 20 profit making PSU’s were responsible for 
80 percent of profits. 
The return on public sector investment for the year 
1990-91 was just over 2 percent.
Criteria for Disinvestment 
The decision regarding disinvestment or liquidation 
viewed in the light of following criteria: 
 Whether the objectives of the company are achieved 
 Whether there is decrease in number of beneficiaries 
 Whether serving the national interest will be affected 
because of disinvestment 
 Whether private sector can efficiently operate and manage 
the undertaking. 
 Whether the original rate of return targeted could not be 
possible to achieve. 
 Whether socio-economic objectives lots its purpose
Process of Disinvestment 
 The govt. in July 1991 initiated the disinvestment process in 
India, while launching the New Economic Policy (NEP). 
 The govt. had appointed the Krishnamurthy committee in 
1991 and Rangarajan committee in 1992 to look after the 
disinvestment process. 
 Both the committees have recommended disinvestments to 
fulfill objectives of modernization of the PSE’s through: 
(a) Strengthening R &D 
(b) Initiating diversification/expansion programme. 
(c) Retaining and reemployment of employees. 
(d) Funding genuine needs of expansion. 
(e) Mitigating fiscal deficit of the government. 
Contd..
 These committees also distinguished between the 
short term and long term goals of the disinvestment 
and advised the govt. not to sacrifice the long term 
goals for the sake of fulfilling the short term 
objectives. 
 The govt. has announced in its NEP that mitigating the 
fiscal deficits is the only objective of disinvestment. 
 The crucial shift in govt. policy for disinvestment of 
PSU’s was mainly attributed to poor performance of 
these enterprises and burden of financing their 
requirements through budget allocation. 
Contd.. 
Process of Disinvestment
Privatization and Disinvestment 
 Privatization implies a change in ownership, resulting in a 
change in management. 
The privatization of public sector enterprises will occur only 
when govt. sells more than 51% of its ownership to private 
entrepreneurs. 
 Disinvestment on the other hand, has a much wider 
connotation as it could either involve dilution of govt. stake to 
a level that result in a transfer of management or could also 
be limited to such a level as would permit govt. to retain 
control over the organization. 
 Disinvestment beyond 50% involves transfer of management, 
where as disinvestment below 50% would result in the govt. 
continuing to have a major say in the undertaking.
11 
PAYBACK PERIOD: Definition 
Is the time required for a firm 
to recover its original 
investment.
12 
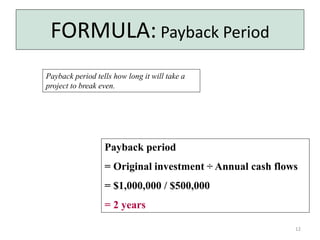
FORMULA: Payback Period 
Payback period tells how long it will take a 
project to break even. 
Payback period 
= Original investment ÷ Annual cash flows 
= $1,000,000 / $500,000 
= 2 years
13 
PAYBACK PERIOD: Uses 
• Sets maximum payback period for all projects; 
rejects any that exceed payback period 
• Measures risk 
– Riskier firms use shorter payback period 
– In liquidity problems, use shorter payback period 
• Avoids obsolescence
14 
PAYBACK PERIOD: Summary 
Payback period provides information that can be 
used to help 
– Control risks of uncertain future cash flows 
– Minimize impact of investment on liquidity 
problems 
– Control risk of obsolescence 
– Control effects of investment on performance 
measures
dis invest ment & pay back period