Simplified Forecasting
Masterclass
1
Warm up exercise
2
Instructions
There are ten questions. You choose a range
so that you are 90% confident you have the
answer inside your range.
Write down the question number, low and high.
Some as tables, some as individuals.
3
Instructions (cont)
For example, “Q1: How many plays did
Shakespeare write?”
Your answer could look like this:
Q1: 10 to 20
4
5
QUIZ!!! Hidden in separate slide
Now please hand your page to your neighbour
Statistically, there is a 99.9% chance that you
got at least 6 correct.
6
The answers
7
Conclusions
Most people doing this don’t get as many right
as expected.
Humans tend to be overconfident.
So now you’re all extra analytical …
8
Download Slides
(SlideShare)
http://goo.gl/tkJWwS
PDF: https://goo.gl/IKNJ3n
9
Introduction
Tim Richardson, CPA, B.A., B.Sc, M. Acct.
10
My Career
Developer at small, innovative IT firm. Large clients.
Large European firm acquires small Aus IT firm (to access technology and clients)
Now even larger clients, in Asia.
→ Sydney → Jakarta.
Works with Finance Director. Joins Philips, put into Finance talent pool
→ Singapore → Eindhoven (NL).
Controller then Finance Director for retail then manufacturing and sourcing.
Back to Australia. Equity raising, CFO of a fairly large international online retailer, then
started GrowthPath.
11
Your Career
Accounting has twice been found to be the
most likely profession to be replaced by expert
systems (modern learning AI)
In one survey, retail checkout was the only job
more likely to go. In another, it was call centre staff
pushing accounting to #2.
12
The accountant of the future …
13
Table Introductions
Please appoint a row leader
Survey your table-mates for their forecast
experience and how important it is to their role
Time budget: 6 minutes
14
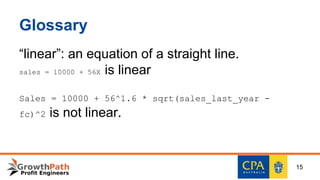
Glossary
“linear”: an equation of a straight line.
sales = 10000 + 56X is linear
Sales = 10000 + 56^1.6 * sqrt(sales_last_year -
fc)^2 is not linear.
15
Glossary
‘Regression’ is finding a formula which explains the shape of data.
Called a trend line in spreadsheets.
More advanced methods are not limited to straight lines; they can find
non-linear lines, like exponential lines.
“Correlation” scores how close the line is to the data.
16
Glossary
‘sand-bagging’: putting in artificially high costs or low sales, expected to
be later ‘thrown overboard’ when needed, as in a hot air balloon.
‘gaming’: manipulating forecasts to reach objectives.
‘sensitivity analysis’: changing an important input (like selling price) to
see how it affects the outcome of a forecast.
‘big data’: collections of massive amounts of business data which never
makes it to accounting records and used to be invisible.
17
“A good player plays where the puck is.
A great player plays where the puck is going
to be”
Wayne Gretzky, ice hockey great.
18
19
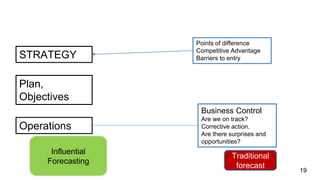
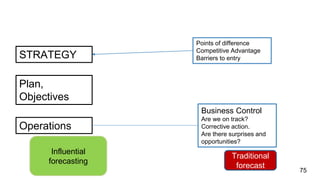
STRATEGY
Points of difference
Competitive Advantage
Barriers to entry
Plan,
Objectives
Operations
Business Control
Are we on track?
Corrective action.
Are there surprises and
opportunities?
Traditional
forecast
Influential
Forecasting
It’s not just about
numbers.
There are people too
20
True or False?
Politics is a sign of a less effective forecast:
True or False?
21
Forecasting and anthropology
Forecasting is a numerical process
But it also involves opinion, power, politics and the allocation of resources.
Processes which do not affect resource allocation are not important.
Processes which do affect resource allocation will be challenged.
Changing how you do forecasting can therefore meet resistance.
22
Forecasting outcomes
How important is this outcome of forecasting:
to accurately predict the future.
Rate your answer from 0 = Not important to 10 = the most important outcome
26
Forecasting outcomes
How important is this outcome of forecasting …
To choose the best future from a forecasted
selection of possible futures
27
Forecasting outcomes
How important is this outcome of forecasting …
To understand how to influence the future by
understanding the link between decisions made
today and future outcomes
28
Now ...
Now that you’ve seen all three questions, do
you change your first two scores?
Are there other questions to add?
29
Our objective today
Something simple: why?
Something relevant to management
Something useful for decisions: why?
30
Why is simplicity so valuable?
Easier to understand.
When someone else can understand your forecast and
own it to convince others of the right course of action, you
have communicated effectively.
Faster to prepare
More time for other things
31
When is a number useful to
management?
32
Forecasting through the ages ….
We need a definition of
forecasting that excludes
things like:
● tea leaves
● tarot cards
● chicken entrails
● signs from god
Why do we reject
these methods today?
Why did people do
them anyway?
33
The use of prediction
Centuries of evidence that humans find
obviously inaccurate forecasts useful anyway.
It’s very interesting to think about why this is
the case.
34
Problem with stone-age forecasts
lack cause and effect.
They make predictions, but don’t show how we
change affect the future.
There is no diagnostic feedback. If the forecast
was wrong, why?
35
A good forecast method
Write three to five characteristics of a good
forecast process
Try to include organisational aspects about the process (who, how long, how is
it discussed) not just technical aspects.
What trade-offs must you make when choosing
a forecast process? A perfect forecast would take one second
and be 100% accurate. But in reality, what compromises do you make?
36
And for bonus points….
Sensitivity analysis / multiple scenarios
based on cashflows with a clear separation of
relevant and sunk costs
37
DECISION FOCUS:
Helps focus on what decisions, impacts and opportunity cost (tradeoffs)
CAUSE AND EFFECT:
Shows how decisions will affect the future
SIMPLE:
People get it, own it, use it.
FEEDBACK: if the future surprises us, our forecast should be diagnostic:
what happened, in a way we can action.
CASHFLOW:
Very useful to forecast on the cash effects of decisions.
Possible answers: A good forecast …
38
Predicting the future
Apart from tea leaves, how can we make
predictions about the future?
What is the traditional method of forecasting?
39
Traditional forecasting
Traditional forecasting believes the secret to the future is based in the past.
Often there is a lot of data. The temptation is to believe that the answer is
there, if only we apply more and more ‘power’.
Statistical forecasting (linear regression, non-linear,... neural networks) is
based on discovering trends and patterns in history to tell us what will happen.
This is a very common myth (e.g. Asimov’s Foundation books).
These methods can become so complex and powerful they approach a
priesthood. Most managers won’t understand them.
40
Advanced tea leaves
Traditional forecasting can be “enhanced” with
advanced methods to mine historical data for
patterns which will repeat in the future.
But this is, in my opinion, largely a waste of time.
This is advanced tea leaves.
41
Random quiz
If my sales are normally distributed, how much
of the time will my sales be below two standard
deviations from the mean?
Write down the answer. You have 10 seconds.
42
Simplification though focus and aggregation
43
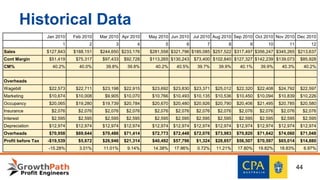
Historical Data
Jan 2010 Feb 2010 Mar 2010 Apr 2010 May 2010 Jun 2010 Jul 2010 Aug 2010 Sep 2010 Oct 2010 Nov 2010 Dec 2010
1 2 3 4 5 6 7 8 9 10 11 12
Sales $127,843 $188,151 $244,650 $233,176 $281,558 $321,796 $185,085 $257,522 $317,497 $356,247 $345,265 $213,637
Cont Margin $51,419 $75,317 $97,433 $92,728 $113,265 $130,243 $73,400 $102,840 $127,327 $142,239 $139,073 $85,928
CM% 40.2% 40.0% 39.8% 39.8% 40.2% 40.5% 39.7% 39.9% 40.1% 39.9% 40.3% 40.2%
Overheads
Wagebill $22,573 $22,711 $23,198 $22,915 $23,692 $23,830 $23,371 $25,012 $22,320 $22,408 $24,792 $22,597
Marketing $10,674 $10,008 $9,905 $10,070 $10,766 $10,493 $10,135 $10,536 $10,450 $10,094 $10,839 $10,226
Occupancy $20,065 $19,280 $19,739 $20,784 $20,670 $20,480 $20,926 $20,790 $20,406 $21,495 $20,785 $20,580
Insurance $2,076 $2,076 $2,076 $2,076 $2,076 $2,076 $2,076 $2,076 $2,076 $2,076 $2,076 $2,076
Interest $2,595 $2,595 $2,595 $2,595 $2,595 $2,595 $2,595 $2,595 $2,595 $2,595 $2,595 $2,595
Depreciation $12,974 $12,974 $12,974 $12,974 $12,974 $12,974 $12,974 $12,974 $12,974 $12,974 $12,974 $12,974
Overheads $70,958 $69,644 $70,486 $71,414 $72,773 $72,448 $72,076 $73,983 $70,820 $71,642 $74,060 $71,048
Profit before Tax -$19,539 $5,672 $26,946 $21,314 $40,492 $57,796 $1,324 $28,857 $56,507 $70,597 $65,014 $14,880
-15.28% 3.01% 11.01% 9.14% 14.38% 17.96% 0.72% 11.21% 17.80% 19.82% 18.83% 6.97%
44
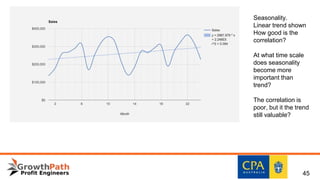
Seasonality.
Linear trend shown
How good is the
correlation?
At what time scale
does seasonality
become more
important than
trend?
The correlation is
poor, but it the trend
still valuable?
45
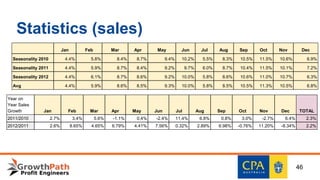
Statistics (sales)
Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec
Seasonality 2010 4.4% 5.8% 8.4% 8.7% 9.4% 10.2% 5.5% 8.3% 10.5% 11.5% 10.6% 6.9%
Seasonality 2011 4.4% 5.9% 8.7% 8.4% 9.2% 9.7% 6.0% 8.7% 10.4% 11.5% 10.1% 7.2%
Seasonality 2012 4.4% 6.1% 8.7% 8.6% 9.2% 10.0% 5.8% 8.6% 10.6% 11.0% 10.7% 6.3%
Avg 4.4% 5.9% 8.6% 8.5% 9.3% 10.0% 5.8% 8.5% 10.5% 11.3% 10.5% 6.8%
Year on
Year Sales
Growth Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec TOTAL
2011/2010 2.7% 3.4% 5.6% -1.1% 0.4% -2.4% 11.4% 6.8% 0.8% 3.0% -2.7% 6.4% 2.3%
2012/2011 2.6% 8.65% 4.65% 6.79% 4.41% 7.56% 0.32% 2.89% 6.98% -0.76% 11.20% -8.34% 2.2%
46
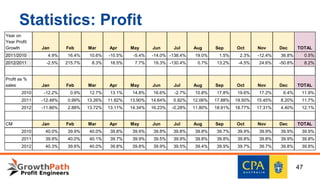
Statistics: Profit
Year on
Year Profit
Growth Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec TOTAL
2011/2010 4.9% 16.4% 10.6% -10.5% -5.4% -14.0% -138.4% 19.0% 1.5% 2.3% -12.4% 36.8% 0.5%
2012/2011 -2.5% 215.7% 8.3% 18.5% 7.7% 19.3% -130.4% 0.7% 13.2% -4.5% 24.6% -50.8% 8.2%
Profit as %
sales Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec TOTAL
2010 -12.2% 0.9% 12.7% 13.1% 14.8% 16.6% -2.7% 10.8% 17.8% 19.6% 17.2% 6.4% 11.9%
2011 -12.48% 0.99% 13.26% 11.82% 13.90% 14.64% 0.92% 12.06% 17.88% 19.50% 15.45% 8.20% 11.7%
2012 -11.86% 2.88% 13.72% 13.11% 14.34% 16.23% -0.28% 11.80% 18.91% 18.77% 17.31% 4.40% 12.1%
CM Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec TOTAL
2010 40.0% 39.9% 40.0% 39.8% 39.9% 39.8% 39.8% 39.8% 39.7% 39.9% 39.9% 39.9% 39.9%
2011 39.9% 40.0% 40.1% 39.7% 39.9% 39.5% 39.9% 39.8% 39.8% 39.8% 39.8% 39.9% 39.8%
2012 40.3% 39.6% 40.0% 39.8% 39.8% 39.9% 39.5% 39.4% 39.9% 39.7% 39.7% 39.8% 39.8%
47
Which is easier to forecast
accurately
Profit in a specific month
Profit in a specific quarter
48
What we can we improve so far?
Variations month to month are hard to forecast from
historical data but the variations smooth out when you
aggregate.
We call this “swings and roundabouts”
Mathematically, it’s related to ‘regression to the mean’
49
First steps: A simplified forecast
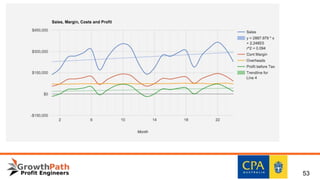
We first just take the existing historical P&L
data and see where common sense leads us
50
51
52
53
Based on the data we have so far,
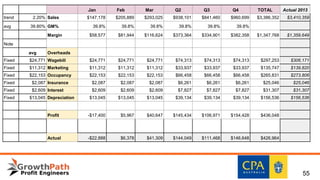
What drives the result?
Use a simple annual growth for sale trend.
Use last year averages for overhead costs
Use avg for GM
54
Jan Feb Mar Q2 Q3 Q4 TOTAL Actual 2013
trend 2.20% Sales $147,178 $205,889 $293,025 $938,101 $841,460 $960,699 $3,386,352 $3,410,359
avg 39.80% GM% 39.8% 39.8% 39.8% 39.8% 39.8% 39.8%
Margin $58,577 $81,944 $116,624 $373,364 $334,901 $382,358 $1,347,768 $1,359,649
Note
avg Overheads
Fixed $24,771 Wagebill $24,771 $24,771 $24,771 $74,313 $74,313 $74,313 $297,253 $306,171
Fixed $11,312 Marketing $11,312 $11,312 $11,312 $33,937 $33,937 $33,937 $135,747 $139,820
Fixed $22,153 Occupancy $22,153 $22,153 $22,153 $66,458 $66,458 $66,458 $265,831 $273,806
Fixed $2,087 Insurance $2,087 $2,087 $2,087 $6,261 $6,261 $6,261 $25,046 $25,046
Fixed $2,609 Interest $2,609 $2,609 $2,609 $7,827 $7,827 $7,827 $31,307 $31,307
Fixed $13,045 Depreciation $13,045 $13,045 $13,045 $39,134 $39,134 $39,134 $156,536 $156,536
Profit -$17,400 $5,967 $40,647 $145,434 $106,971 $154,428 $436,048
Actual -$22,888 $6,378 $41,309 $144,049 $111,468 $146,648 $426,964
55
Summary
Focus on what matters,
Take advantage of swings and roundabouts:
• Aggregate
• Forecast by quarters instead of months (take
a page from the Rolling Forecasting book)
56
Was that over-simple?
We do some some analysis on what’s going on in
sales.
We are concerned about the role of price and mix
play. Maybe growth based on volume increase is
too crude?
What are some scenarios where this may be the
case?
57
Synthesised KPIs
This business sells a range of products in four
categories with consistent margins. There is
seasonality and some underlying trend growth.
58
Synthesised KPIs
A synthesised KPI is an indicator created form
data you already have. Accounting ratios like
days sales outstanding, or inventory stock
cover, are examples.
We will explore a measure of sale mix.
59
Sales KPIs: An example of a synthesised KPI
Price effect
Mix effect
Voume effect
A small technique that may help give some
insight into sales trends of product categories
60
When may it be useful?
If innovation or competition is affecting products
differently
The concept can be extended to anywhere
there is ‘something going on’ at a level of detail
which is partially or substantially influenced by
outside factors
61
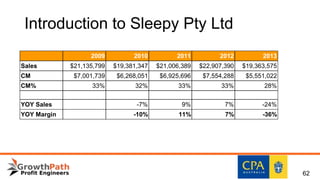
2009 2010 2011 2012 2013
Sales $21,135,799 $19,381,347 $21,006,389 $22,907,390 $19,363,575
CM $7,001,739 $6,268,051 $6,925,696 $7,554,288 $5,551,022
CM% 33% 32% 33% 33% 28%
YOY Sales -7% 9% 7% -24%
YOY Margin -10% 11% 7% -36%
Introduction to Sleepy Pty Ltd
62
Minor spreadsheet point
To multiply one block of numbers by another,
can use SUMPRODUCT(block1, block2)
A block from f1 to f5 is written F1:F5
63
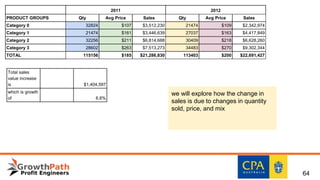
2011 2012
PRODUCT GROUPS Qty Avg Price Sales Qty Avg Price Sales
Category 0 32824 $107 $3,512,230 21474 $109 $2,342,974
Category 1 21474 $161 $3,446,639 27037 $163 $4,417,849
Category 2 32256 $211 $6,814,688 30409 $218 $6,628,260
Category 3 28602 $263 $7,513,273 34483 $270 $9,302,344
TOTAL 115156 $185 $21,286,830 113403 $200 $22,691,427
Total sales
value increase
is $1,404,597
which is growth
of 6.6%
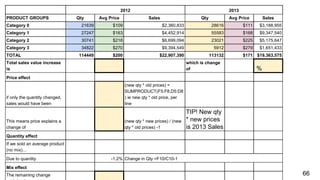
we will explore how the change in
sales is due to changes in quantity
sold, price, and mix
64
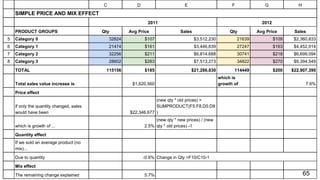
C D E F G H
SIMPLE PRICE AND MIX EFFECT
2011 2012
PRODUCT GROUPS Qty Avg Price Sales Qty Avg Price Sales
5 Category 0 32824 $107 $3,512,230 21639 $109 $2,360,833
6 Category 1 21474 $161 $3,446,639 27247 $163 $4,452,914
7 Category 2 32256 $211 $6,814,688 30741 $218 $6,699,094
8 Category 3 28602 $263 $7,513,273 34822 $270 $9,394,549
TOTAL 115156 $185 $21,286,830 114449 $200 $22,907,390
Total sales value increase is $1,620,560
which is
growth of 7.6%
Price effect
if only the quantity changed, sales
would have been $22,346,677
(new qty * old prices) =
SUMPRODUCT(F5:F8,D5:D8
)
which is growth of ... 2.5%
(new qty * new prices) / (new
qty * old prices) -1
Quantity effect
If we sold an average product (no
mix)...
Due to quantity -0.6% Change in Qty =F10/C10-1
Mix effect
The remaining change explained 5.7% 65
2012 2013
PRODUCT GROUPS Qty Avg Price Sales Qty Avg Price Sales
Category 0 21639 $109 $2,360,833 28616 $111 $3,188,955
Category 1 27247 $163 $4,452,914 55583 $168 $9,347,540
Category 2 30741 $218 $6,699,094 23021 $225 $5,175,647
Category 3 34822 $270 $9,394,549 5912 $279 $1,651,433
TOTAL 114449 $200 $22,907,390 113132 $171 $19,363,575
Total sales value increase
is
which is change
of %
Price effect
if only the quantity changed,
sales would have been
(new qty * old prices) =
SUMPRODUCT(F5:F8,D5:D8
) ie new qty * old price, per
line
This means price explains a
change of
(new qty * new prices) / (new
qty * old prices) -1
TIP! New qty
* new prices
is 2013 Sales
Quantity effect
If we sold an average product
(no mix)...
Due to quantity -1.2% Change in Qty =F10/C10-1
Mix effect
The remaining change 66
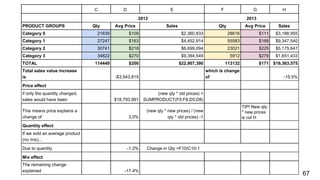
C D E F G H
2012 2013
PRODUCT GROUPS Qty Avg Price Sales Qty Avg Price Sales
Category 0 21639 $109 $2,360,833 28616 $111 $3,188,955
Category 1 27247 $163 $4,452,914 55583 $168 $9,347,540
Category 2 30741 $218 $6,699,094 23021 $225 $5,175,647
Category 3 34822 $270 $9,394,549 5912 $279 $1,651,433
TOTAL 114449 $200 $22,907,390 113132 $171 $19,363,575
Total sales value increase
is -$3,543,815
which is change
of -15.5%
Price effect
if only the quantity changed,
sales would have been $18,793,991
(new qty * old prices) =
SUMPRODUCT(F5:F8,D5:D8)
This means price explains a
change of 3.0%
(new qty * new prices) / (new
qty * old prices) -1
TIP! New qty
* new prices
is col H
Quantity effect
If we sold an average product
(no mix)...
Due to quantity -1.2% Change in Qty =F10/C10-1
Mix effect
The remaining change
explained -17.4%
67
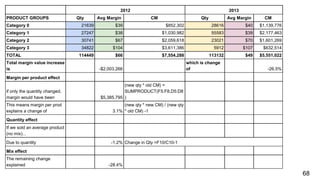
2012 2013
PRODUCT GROUPS Qty Avg Margin CM Qty Avg Margin CM
Category 0 21639 $39 $852,302 28616 $40 $1,139,776
Category 1 27247 $38 $1,030,982 55583 $39 $2,177,463
Category 2 30741 $67 $2,059,618 23021 $70 $1,601,269
Category 3 34822 $104 $3,611,386 5912 $107 $632,514
TOTAL 114449 $66 $7,554,288 113132 $49 $5,551,022
Total margin value increase
is -$2,003,266
which is change
of -26.5%
Margin per product effect
if only the quantity changed,
margin would have been $5,385,795
(new qty * old CM) =
SUMPRODUCT(F5:F8,D5:D8
)
This means margin per prod
explains a change of 3.1%
(new qty * new CM) / (new qty
* old CM) -1
Quantity effect
If we sold an average product
(no mix)...
Due to quantity -1.2% Change in Qty =F10/C10-1
Mix effect
The remaining change
explained -28.4%
68
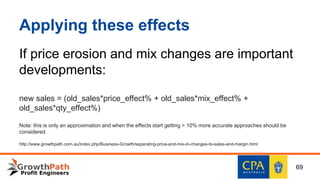
If price erosion and mix changes are important
developments:
new sales = (old_sales*price_effect% + old_sales*mix_effect% +
old_sales*qty_effect%)
Note: this is only an approximation and when the effects start getting > 10% more accurate approaches should be
considered.
http://www.growthpath.com.au/index.php/Business-Growth/separating-price-and-mix-in-changes-to-sales-and-margin.html
Applying these effects
69
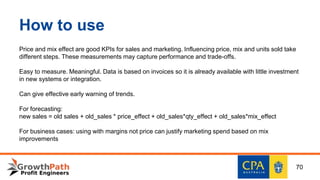
How to use
Price and mix effect are good KPIs for sales and marketing. Influencing price, mix and units sold take
different steps. These measurements may capture performance and trade-offs.
Easy to measure. Meaningful. Data is based on invoices so it is already available with little investment
in new systems or integration.
Can give effective early warning of trends.
For forecasting:
new sales = old sales + old_sales * price_effect + old_sales*qty_effect + old_sales*mix_effect
For business cases: using with margins not price can justify marketing spend based on mix
improvements
70
Synthesised KPIs
Synthesised KPIs can’t reveal new information,
but they can reveal new perspectives in facts
you already have.
Since we have lots of accounting data points,
this is best place to look for them. Traditional
accounting ratios are synthesised KPIs.
71
Next topic:
Making the forecast influential
73
Making the forecast influential
Traditional forecasting aims to predict future accounting
reports mostly using old accounting reports, and the
outcome of forecasting is a P&L
But the decisions and the plans for the business are
probably focused on customers and innovations.
74
75
STRATEGY
Points of difference
Competitive Advantage
Barriers to entry
Plan,
Objectives
Operations
Business Control
Are we on track?
Corrective action.
Are there surprises and
opportunities?
Traditional
forecast
Influential
forecasting
Influence and Diagnose
The important decisions for a business are
mostly based on
Customers, Competitors, Innovation.
So the closer finance gets to that, the more useful we become.
Too often finance is merely helping to manage the consequences of
those decisions.
76
But we also need ...
Simplicity
Numbers
Focus
77
A solution
1. Use models but use them properly
2. Base the forecast on “business drivers”
78
What is the default model
of traditional forecasting?
79
Models are great. Are they perfect?
Models work because they let us freeze most
real world complexity and focus on what
matters.
If the stuff we freeze is just noise, this is very
helpful.
80
When models go bad
1. Black Swans
2. When the “noise” actually becomes
important.
E.g. you may ignore a stable cost but if it
turns out to be currency driven (supplier
offshored) and the AUD crashes...
81
When models go bad
3. When business drivers change (competitor,
M&A, innovation, market shift, new
management)
82
Black Swans
So named after the Australian Black Swan.
Other examples:
GFC
Rise of iPhone
Sept 11
83
Black Swans
• "Black swans" are highly consequential but unlikely
events that are easily explainable – but only in retrospect.
• Black swans have shaped the history of technology,
science, business and culture.
• As the world gets more connected, black swans are
becoming more consequential.
84
Black Swans
• The human mind is subject to numerous
blind spots, illusions and biases.
• One of the most pernicious biases is
misusing standard statistical tools
• Expert advice is often useless and
overvalued.
85
Black Swans
• Most forecasting is pseudoscience.
• You can retrain yourself to overcome your
cognitive biases and to appreciate randomness.
But it's not easy.
86
My Black Swans
Indonesia 96/97
Sept 11, 2001
Rise of China 2000s
EU Anti-dumping
Shift to consumer for CFLi
CO2 abatement programs
GFC 2009
87
One of the biggest black swans
North American shale oil (fracking)
Remember peak oil?
Now, oil is $50 a barrel and the US no longer
needs to import. It has so much gas that cheap
energy is now a competitive advantage.
88
How to deal with black swans?
Don’t be over-confident in your forecasts.
Be robust and highly responsive to opportunities.
We should value forecasting approaches which can quickly adapt to
new circumstance.
An agile, responsive business will use simple forecasting methods, but
simple forecasting methods won’t make a business agile.
Extremely expensive and sophisticated models are not better. They can
be worse because they encourage over-confidence.
Google Long-Term Capital Management.
89
When models get over-extended
A model which loses its simplicity is a half-way
place, the worst of both worlds.
90
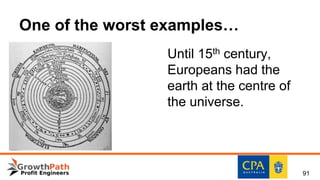
One of the worst examples…
Until 15th century,
Europeans had the
earth at the centre of
the universe.
91
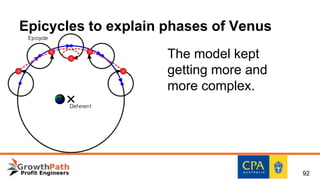
Epicycles to explain phases of Venus
The model kept
getting more and
more complex.
92
What was the “Black Swan” for
models of the solar system?
93
Coping with the weakness of models
Be prepared to change models when business
focus changes.
As a habit, diagnose both favourable and
unfavourable deviations from your forecast.
94
What to model?
95
The P&L as a forecast model: Pros and Cons
PROS
• You are going to do it anyway
• Historical data in this format is
free
CONS
• Bad at focus
• Says little or nothing about how
the business wins customers
• Poor for diagnostics
• Extremely limited at decision
support
• Very complex (mix of cash and
imaginary numbers, and technical
considerations)
• Serves too many masters
96
Business Drivers
A business driver is
●Influenceable by the business
●Measurable
●Linked to sales (or costs) via a simple
formula
97
Model built on business drivers
Connect drivers to a cashflow event with linear
formulas:
cash_event = driver_score * something1 + something2
You can initially guess something1 and something2.
Measuring it means you will get more accurate.
98
The Perfect Customer
A business should have a “perfect customer” in
mind.
This customer should recognise herself in the
selected handful of business drivers.
99
Which of these could be business drivers for a mid-sized
residential construction business operating in Melbourne’s north?
• National home lending approvals
• Number of visitors to our display homes
• Number of VCAT modifications and rejections of our plans
• Percentage of modifications per job to our standard home designs
• Avg percentage of total home project spend we capture
• Percentage of clients who take our landscape gardening bundled
service
• RBA interest rate settings
• Number of days lost to injury on site
100
Strategic plan says
“We target customers looking for fast, simple
and cheaper builds”.
Choose two drivers.
101
Or Strategic plan says
“We will capture high value clients by providing
a complete, custom approach to the entire
family home project including integrating green
space with the home design”.
Choose best two.
102
Account for most, not all
A small range of drivers will not capture every
variation in the business, but they should
capture most.
103
Recap Business Drivers
A P&L is a generic report.
But what is the fingerprint, the DNA of a
business?
104