The Syndicated Loan Market     definitions and sizing    Russia and Europe’s  experience   Transforming the Syndicated Loan Market   March 14, 2010 – Page  BWBB 5043: Credit and Syndicated Loan Management PREPARED FOR: CIK JULAILA JOHARI PREPARED BY: Hajaj S. M. Foujo 801468 Ahmed K. M. Madi 801131 Hocine Boughezala Hamad 802042 Bannapov Feruzbek 805873
May 2006 – Page  contents  Transforming the Syndicated Loan Market Conclusion  2 3 4 Syndicated loan market in Europe &Russia Overview of syndicated loan 1
- Definition and sizing - vision syndicated loan market - characteristics of old and new loan market    May 2006 – Page  Overview  of syndicated loan
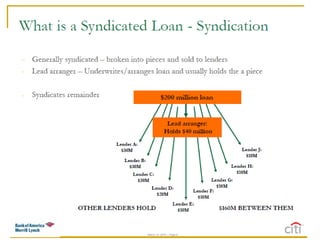
Syndicated Loans A loan provided by a group of banks  Single loan agreement, common terms and conditions One or more arranging  banks  (‘Mandated Lead Arranger’ or ‘MLA’) Various roles are divided between the MLAs: Book runner Underwriting bank Documentation bank Information memorandum bank Signing bank Agent bank Each participant bank may commit a different amount, reflected in the title Structures cover a wide variety of options (e.g. plain vanilla, property finance, acquisition finance) March 14, 2010 – Page  Q. What is a syndicated loan? Size  Significance nationally & internationally  Creditworthiness  Industry sector Q. What factors determine which borrowers can access the syndicated loan market?
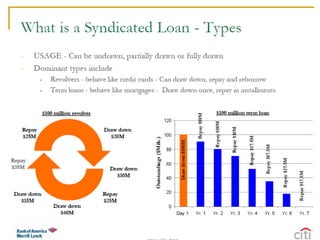
Syndicated Loans (cont’d) Discuss funding requirements with potential arrangers Decide on best way to meet these requirements Ask for bids or indications Select the most suitable bid and appoint arranger Assist arranger with syndication process March 14, 2010 – Page  International and local banks Insurance companies Hedge funds, relatively new to the market, very aggressive Q. What is the Structure of a typical Syndicated Loan Q. How does a Borrower access the Syndicated Loan Market Q. Who are the lenders in the syndicated loan market Each Loan is different Revolver/ Term Loan Extended drawdown Bullet/amortising Early repayment Multi-currency Secured/unsecured Multi-tranche
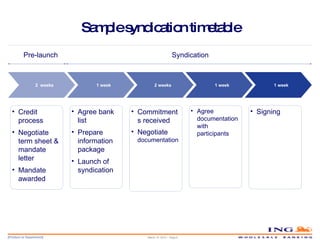
Sample syndication timetable March 14, 2010 – Page  Credit process Negotiate term sheet & mandate letter Mandate awarded Agree bank list Prepare information package  Launch of syndication Commitments received Negotiate  documentation Agree documentation with participants Signing Pre-launch Syndication 1 week  2 weeks   1 week   1 week  2  weeks
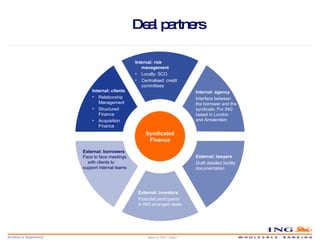
Deal partners March 14, 2010 – Page  Internal: clients Relationship Management Structured Finance Acquisition Finance External: lawyers Draft detailed facility documentation External: investors Potential participants in ING arranged deals External: borrowers  Face to face meetings  with clients to support internal teams Internal: agency Interface between the borrower and the syndicate. For ING based in London  and Amsterdam Internal: risk management Locally: SCO Centralised: credit committees Syndicated Finance
May 2006 – Page  March 14, 2010 – Page
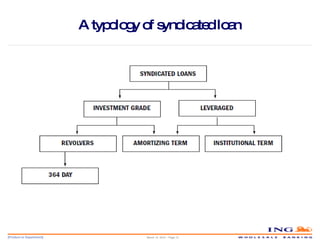
A typology of syndicated loan March 14, 2010 – Page
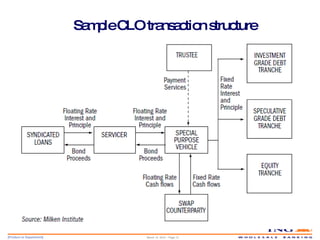
Sample CLO transaction structure  March 14, 2010 – Page
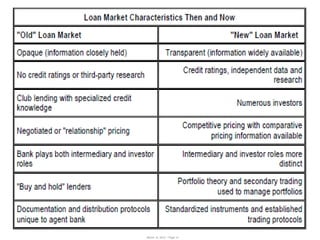
May 2006 – Page  March 14, 2010 – Page
May 2006 – Page  Sources :Syndicated Finance ING Bank London Syndicated loan market in Europe &Russia
March 14, 2010 – Page  The syndicated loan market in CEE, Russia and CIS is a private market. As a consequence, reliable information and statistics about individual transactions and the market overall is difficult to obtain. Various different publicly available sources of information, such as IFR, Euroweek, Loan Pricing Corporation/Reuters, Loanware and Standard & Poors provide information on the market and general trends, although each has a different methodology. As a result of the lack of a centrally co-ordinated and verified market database, the information provided by these sources may be inconsistent or indeed unreliable.
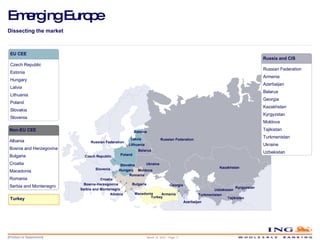
Emerging Europe Russian Federation Poland Slovakia Hungary Lithuania Latvia Estonia Belarus Ukraine Moldova Kazakhstan Kyrgyzstan Uzbekistan Tajikistan Turkmenistan Georgia Romania Bulgaria Turkey Dissecting the market Turkey March 14, 2010 – Page  EU CEE Czech Republic Estonia Hungary Latvia Lithuania Poland Slovakia Slovenia Non-EU CEE Albania Bosnia and Herzegovina Bulgaria Croatia Macedonia Romania Serbia and Montenegro Russia and CIS Russian Federation Armenia Azerbaijan Belarus Georgia Kazakhstan Kyrgyzstan Moldova Tajikistan Turkmenistan Ukraine Uzbekistan Russia and CIS Azerbaijan Croatia Czech Republic Bosnia-Herzegovina Serbia and Montenegro  Albania Russian Federation Slovenia Macedonia Armenia
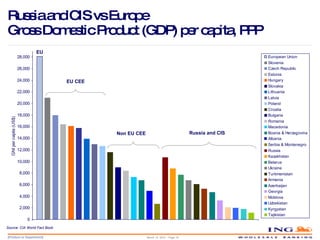
Russia and CIS vs Europe  Gross Domestic Product (GDP) per capita, PPP Source: CIA World Fact Book EU EU CEE Non EU CEE Russia and CIS March 14, 2010 – Page
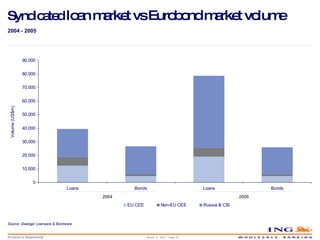
Syndicated  loan market vs Eurobond market volume 2004 2005 2004 - 2005 Source: Dealogic Loanware & Bondware March 14, 2010 – Page
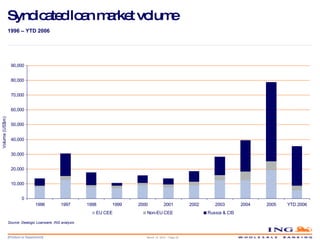
Syndicated loan market volume 1996 – YTD 2006  Source: Dealogic Loanware, ING analysis March 14, 2010 – Page
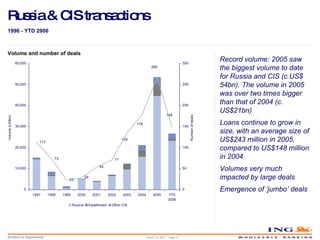
Russia & CIS transactions Volume and number of deals 1996 - YTD 2006 Record volume: 2005 saw the biggest volume to date for Russia and CIS (c.US$ 54bn). The volume in 2005 was over two times bigger than that of 2004 (c. US$21bn) Loans continue to grow in size, with an average size of US$243 million in 2005, compared to US$148 million in 2004  Volumes very much impacted by large deals Emergence of ‘jumbo’ deals March 14, 2010 – Page
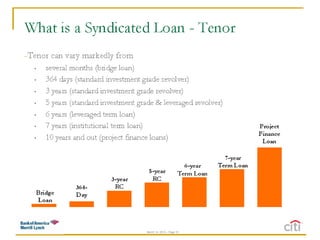
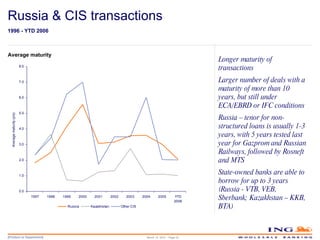
Russia & CIS transactions Average maturity 1996 - YTD 2006 Longer maturity of transactions Larger number of deals with a maturity of more than 10 years, but still under ECA/EBRD or IFC conditions Russia – tenor for non-structured loans is usually 1-3 years, with 5 years tested last year for Gazprom and Russian Railways, followed by Rosneft and MTS State-owned banks are able to borrow for up to 3 years (Russia - VTB, VEB, Sberbank; Kazakhstan – KKB, BTA) March 14, 2010 – Page
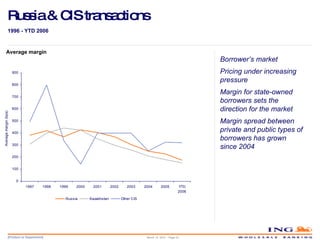
Russia & CIS transactions Average margin 1996 - YTD 2006 Borrower’s market Pricing under increasing pressure Margin for state-owned borrowers sets the direction for the market Margin spread between private and public types of borrowers has grown since 2004 March 14, 2010 – Page
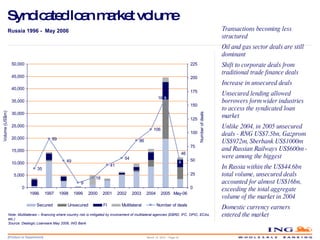
Syndicated loan market volume Note: Multilaterals – financing where country risk is mitigated by involvement of multilateral agencies (EBRD, IFC, OPIC, ECAs, etc.) Source: Dealogic Loanware May 2006, ING Bank Russia 1996 -  May 2006 Transactions becoming less structured Oil and gas sector deals are still dominant Shift to corporate deals from traditional trade finance deals Increase in unsecured deals Unsecured lending allowed borrowers form wider industries to access the syndicated loan market Unlike 2004, in 2005 unsecured deals - RNG US$7.5bn, Gazprom US$972m, Sberbank US$1000m and Russian Railways US$600m - were among the biggest In Russia within the US$44.6bn total volume, unsecured deals accounted for almost US$16bn, exceeding the total aggregate volume of the market in 2004 Domestic currency earners entered the market March 14, 2010 – Page
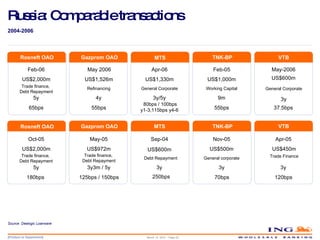
Russia: Comparable transactions Source: Dealogic Loanware Feb-06 May 2006 Apr-06 Feb-05 May-2006 US$2,000m US$1,526m US$1,330m US$1,000m US$600m General Corporate Working Capital General Corporate 5y 4y 3y/5y 9m 3y 65bps 55bps 37.5bps Trade   finance ,  Debt   Repayment Refinancing 55bps 80bps / 100bps y1-3,115bps y4-6  Oct-05 May-05 Sep-04 Nov-05 US$2,000m US$972m US$600m US$500m Debt Repayment 5y 3y3m / 5y 3y 3y 180bps 125bps / 150bps General corporate 70bps Rosneft OAO Gazprom OAO MTS TNK-BP VTB Gazprom OAO MTS TNK-BP 250bps Rosneft OAO Trade   finance ,  Debt   Repayment Trade   finance ,  Debt   Repayment Apr-05 US$450m 3y Trade Finance 120bps VTB 2004-2006 March 14, 2010 – Page
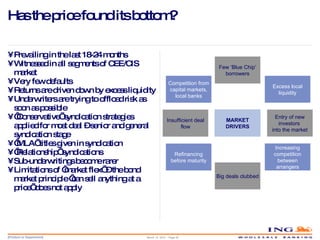
Has the price found its bottom? Prevailing in the last 18-24 months Witnessed in all segments of CEE/CIS market Very few defaults Returns are driven down by excess liquidity Underwriters are trying to offload risk as soon as possible ‘ Conservative’ syndication strategies applied for most deal – senior and general syndication stage ‘ MLA’ titles given in syndication ‘ Relationship’ syndications Sub-underwritings become rarer Limitations of ‘market flex’ – the bond market principle ‘can sell anything at a price’ does not apply MARKET DRIVERS Few ‘Blue Chip’ borrowers Insufficient deal flow Competition from capital markets, local banks Increasing competition between arrangers Entry of new investors  into the market Excess local liquidity Refinancing before maturity Big deals clubbed March 14, 2010 – Page
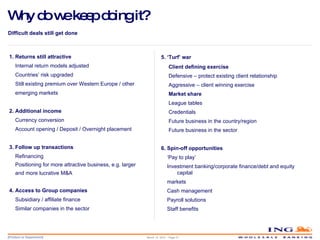
Why do we keep doing it? Difficult deals still get done 1. Returns still attractive Internal return models adjusted Countries’ risk upgraded Still existing premium over Western Europe / other emerging markets 2. Additional income Currency conversion Account opening / Deposit / Overnight placement 3. Follow up transactions Refinancing Positioning for more attractive business, e.g. larger  and more lucrative M&A 4. Access to Group companies Subsidiary / affiliate finance Similar companies in the sector 5. ‘Turf’ war  Client defining exercise Defensive – protect existing client relationship Aggressive – client winning exercise Market share League tables Credentials Future business in the country/region Future business in the sector 6. Spin-off opportunities ‘ Pay to play’ Investment banking/corporate finance/debt and equity capital markets Cash management Payroll solutions Staff benefits March 14, 2010 – Page
Outlook for 2006 Russia At current growth rate, the size of the market will double in two years New borrowers will enter the market driven by attractiveness of the syndicated loan market Investor inflow will continue – driven by still attractive yields and low recent default rates Fragile market – ‘a single ‘failed’ deal can shake market confidence Arranging banks will look for new borrowers; move to 2 nd  tier Growth of event-driven deals, including sponsor-driven LBOs Relationship-defining syndications and local currency syndications Syndicated loan market – substitution for volatile DCM Top names will follow the ‘longer tenor’ trend Rest of CIS Shift away from secured deals  Industry diversity  Returns for investors likely to be lower, but still remain attractive  March 14, 2010 – Page
A White Paper to the Industry – September 2008 by The Depository Trust & Clearing Corporation (DTCC) May 2006 – Page  Transforming the Syndicated Loan Market
Introduction  The syndicated loan market has shown expansive growth in the past several years, reaching a global volume of more than $4.5 trillion in 2007, an increase of 13% over 2006 and 32% over 2005. The largest market was the United States, with $2.1 trillion in loan activity, an increase of more than 20% over 2006. The second largest market was the United Kingdom, with $376.3 billion in syndicated lending .  May 2006 – Page
Cont’d... Secondary trading in the market has also grown significantly in the U.S., with an estimated 92% increase in trading volumes in 2007 over 2006. The processing of syndicated loans is hampered by manual processes, outdated communications and an absence of industry-wide standards . May 2006 – Page
The Depository Trust & Clearing Corporation (DTCC) is working closely with an advisory committee of leading global banks, including The Bank of New York Mellon, Barclays Capital, Citi, Deutsche Bank and The Royal Bank of Scotland to introduce technology and solutions to address the processing and recordkeeping challenges that persist in this market. May 2006 – Page
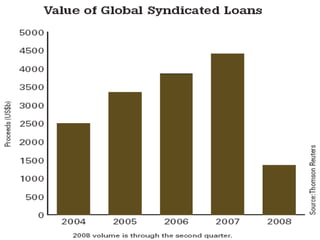
The Historical Demand for Syndicated Lending The syndicated loan industry, comparatively minuscule before the early 1970s, grew explosively after the oil crisis of 1973. As petroleum prices soared, banks amassed deposits from oil-exporting countries and funneled them out in syndicated loans to oil-importing countries By 2003, new deals had soared to $1.6 trillion globally, roughly 10 times the total a decade earlier. The syndicated loan market grew spectacularly over the next few years, especially in 2006 and 2007, due in large part to the vast liquidity in the markets and a sharp increase in leveraged investing. In 2007 alone, worldwide syndicated loan volume totaled a record $4.5 trillion, up 13% over 2006. May 2006 – Page
May 2006 – Page
Current and Long-Term Opportunities  The global credit tightening that began around mid- 2007 has affected the primary market in syndicated lending, as it has affected almost every sector of the loan marketplace. In the U.S., for instance, first-half volume in 2008 was down 51% when compared to the first half of 2007. Global syndicated lending for the first half of 2008 reached $1.3 trillion, representing a 47% decrease from the first half of 2007 . May 2006 – Page
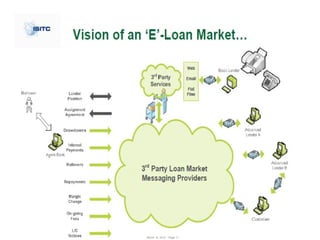
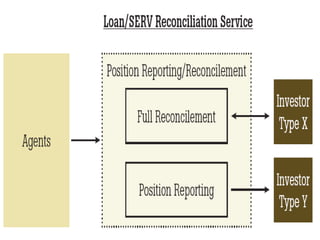
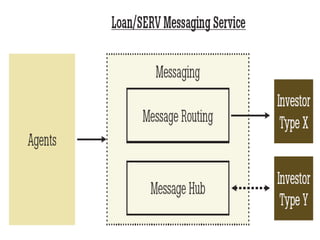
Automation Initiatives for the Syndicated Loan Market In the first quarter of 2008, DTCC announced it was developing a new and evolving suite of services called Loan/SERV that would help automate and streamline the processing of syndicated commercial loans. DTCC will introduce two specific services in 2008, including: •  Loan/SERV Reconciliation Service. •  Loan/SERV Messaging Service. May 2006 – Page
May 2006 – Page
May 2006 – Page
The Loan/SERV suite of services will introduce increased automation to the industry in several ways such as  Bring standardized loan. Reduce position breaks. Reduce cash breaks. Help reduce trade settlement delays caused by inaccurate recordkeeping. Reduce fax-based communications . May 2006 – Page
Position  and Cash Breaks Position breaks happen when records of loan commitment balances registered by the agent differ from those recorded by lenders. Such occurrences are not uncommon because lenders and agents keep completely separate records, and the problem has grown increasingly troublesome with the growth of the syndicated loan market. Through such improvements, Loan/SERV will create more efficient and less risky loan syndication operational processes. This will reduce position and cash breaks, make the flow of information less error-prone and help move the industry towards its goal of closing secondary trades seven days after trade date in the U.S. and 10 days in Europe . May 2006 – Page
Standardization of Transaction Language Loan/SERV will help bring efficient syndicated loan communications, in part by embracing FpML (Financial products Markup Language), the industry- standardized ecommerce language. FpML is well-tested in over-the-counter derivative-trading markets, where it was constructed to combine speed, usability and security. May 2006 – Page
DTCC will continue to follow the model of its successful Deriv/SERV product line and, like Deriv/ SERV, Loan/SERV will grow the market while helping to manage operational risk. Loan/SERV addresses the fundamental issues in both the U.S. and European syndicated loan markets by offering automation initiatives. Help reduce position breaks by adopting automation to track, report and update position changes daily. Help reduce related cash breaks. Replace outdated fax-based communications with a Web-based interface linked to a central platform. Employ standardized loan servicing language with the adoption of FpML . May 2006 – Page  Conclusion
Thank you  for attention  March 14, 2010 – Page  Questions ?