Sales & Cost Analysis


                  1
Sales & Cost Analysis
Done for sales control: statistical purpose of sales
    control: A/cg analysis to determine profitability
Why Sales Control?
1. Measuring Performance: Objective evaluation of
    sales efforts critical for growth
      Some measures: Sales / Quota ratio / Budget
    ratio, Closes / Calls ratio
2. Identifying problems before they magnify:
    Inaccurate sales forecasts, low profit margins,
    low business, inability of Sales Management to
    maximize revenues to existing customers
3. Identifying sales opportunities


                                           2
How to manage Sales Control?
1. Setting goals: Part of Sales Planning & Sales
   Budgeting process
   SP: Staffing, Recruiting, Training, Evaluation
     SB: Targets for Sales and for Costs associated
   with Sales
2. Comparing actual with targets
3. Taking corrective action

Problem in sales control
1. External factors over which sales people have no
    control
2. Inadequate information

                                         3
Sales Analysis
1. Gathering, classifying, comparing and studying
    sales data
2. Converts row data from various sources into
    actionable information
3. Helps in non marketing functions like production
    planning,     cash      management,   inventory
    management etc.
4. Managers have to decide on purpose of
    evaluation before doing sales analysis; simple
    sales analysis gives figures while comparative
    sales analysis sets standards
5. Sales information systems use mathematical and
    statistical procedures to generate reports;
    managers have to decide which information to
    use for what purpose.
                                         4
How to do Sales Analysis?

1.   Most critical element in sales analysis is sales
     information; most commonly used source for
     sales information is the sales invoice.
2.   Other sources of information include cash
     register receipts, sales person call reports and
     expense reports, financial reports, warranties etc.
3.   Different types of sales analysis could be :


                                             5
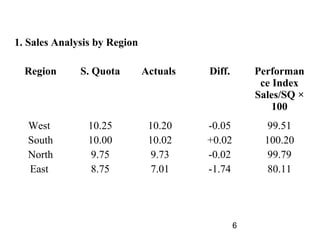
1. Sales Analysis by Region

  Region      S. Quota        Actuals   Diff.       Performan
                                                     ce Index
                                                    Sales/SQ ×
                                                        100
  West          10.25          10.20    -0.05          99.51
  South         10.00          10.02    +0.02         100.20
  North          9.75           9.73    -0.02          99.79
  East           8.75           7.01    -1.74          80.11


                                                6
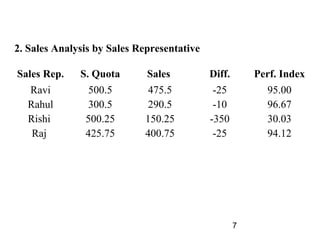
2. Sales Analysis by Sales Representative

Sales Rep.    S. Quota       Sales          Diff.       Perf. Index
  Ravi          500.5        475.5           -25          95.00
  Rahul         300.5        290.5           -10          96.67
  Rishi        500.25       150.25          -350          30.03
   Raj         425.75       400.75           -25          94.12


                                                    7
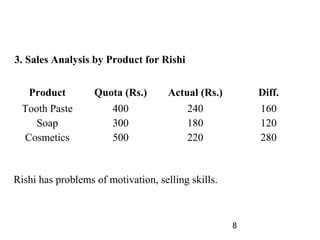
3. Sales Analysis by Product for Rishi


   Product         Quota (Rs.)       Actual (Rs.)       Diff.
 Tooth Paste           400               240            160
    Soap               300               180            120
 Cosmetics             500               220            280


Rishi has problems of motivation, selling skills.


                                                    8
4.   Sales analysis by customer: Company can focus
     on promising segments
5.   Sales analysis by distribution channel: Can help
     in making elimination decisions regarding
     channels
6.   Sales analysis by units sold: Useful during times
     of inflation and price changes


                                            9
Sales Audit


              10
Sales Audit

 Periodic Review of Sales Activity
 Earlier Financial Review, but now done for HR,
  Marketing etc.
 A Sales Force Management Audit involves
   Study of sales management environment
      (customers, economic, competitive, tech.
      legal etc.)
   Study of sales department’s objectives,
      strategies, implementation.
   Evaluation of the sales organization to its
      effectiveness
   Evaluation of SM functions: recruitment,
      compensation,      forecasting,   training,
      budgeting
                                        11
Sales Analysis focuses on Results
Cost Analysis looks into costs incurred to
produce results.

Profitability Analysis would include Sales
Cost and Marketing Costs.
Marketing Cost Analysis analyses sales
volume and selling expenses to identify the
profitability of sales activities.


                                     12
Break Even Analysis

(Unit SP × No. of Units) – (Unit Var Cost × No.
of Units)
Less fixed costs = Operating Income = 0
Eq. SP = Rs.30, CP = Rs.21, Fixed Cost =
Rs.36,000
(30 – 21) × N – 360000 = 0
or, N = 360000 / 9 = 40,000 (Break Even Point)
Eq. Co. wants operating profit of 1,35,000
(30 – 21) × N – 360000 = 135000
So N = (360000 + 135000) / 9 = 55000


                                        13
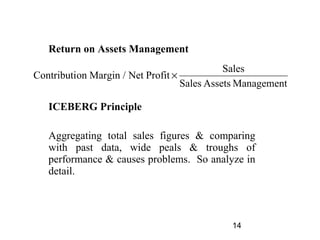
Return on Assets Management
                                             Sales
Contribution Margin / Net Profit ×
                                   Sales Assets Management

   ICEBERG Principle

   Aggregating total sales figures & comparing
   with past data, wide peals & troughs of
   performance & causes problems. So analyze in
   detail.


                                             14