January 2016
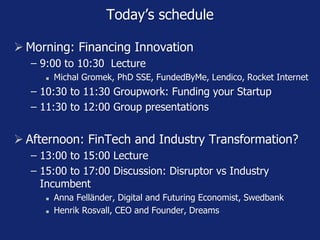
Today’s schedule
 Morning: Financing Innovation
− 9:00 to 10:30 Lecture
 Michal Gromek, PhD SSE, FundedByMe, Lendico, Rocket Internet
− 10:30 to 11:30 Groupwork: Funding your Startup
− 11:30 to 12:00 Group presentations
 Afternoon: FinTech and Industry Transformation?
− 13:00 to 15:00 Lecture
− 15:00 to 17:00 Discussion: Disruptor vs Industry
Incumbent
 Anna Felländer, Digital and Futuring Economist, Swedbank
 Henrik Rosvall, CEO and Founder, Dreams
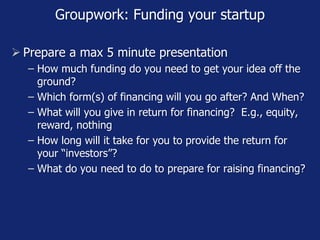
Groupwork: Funding your startup
 Prepare a max 5 minute presentation
− How much funding do you need to get your idea off the
ground?
− Which form(s) of financing will you go after? And When?
− What will you give in return for financing? E.g., equity,
reward, nothing
− How long will it take for you to provide the return for
your “investors”?
− What do you need to do to prepare for raising financing?
If the rate of change on the
outside exceeds the rate of
change on the inside,
the end is near....
-Jack Welch
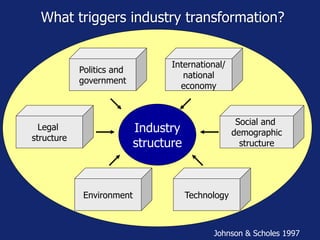
What triggers industry transformation?
Johnson & Scholes 1997
Politics and
government
Environment Technology
Legal
structure
Social and
demographic
structure
International/
national
economy
Industry
structure
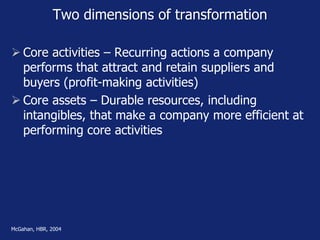
Two dimensions of transformation
 Core activities – Recurring actions a company
performs that attract and retain suppliers and
buyers (profit-making activities)
 Core assets – Durable resources, including
intangibles, that make a company more efficient at
performing core activities
McGahan, HBR, 2004
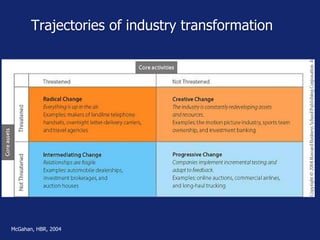
Trajectories of industry transformation
McGahan, HBR, 2004
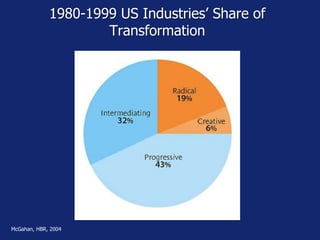
1980-1999 US Industries’ Share of
Transformation
McGahan, HBR, 2004
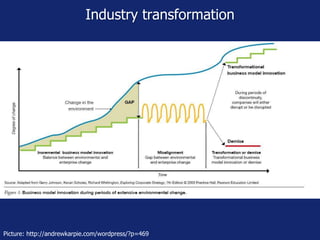
Industry transformation
Picture: http://andrewkarpie.com/wordpress/?p=469
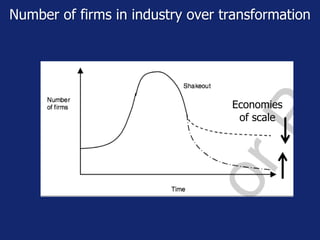
Number of firms in industry over transformation
Economies
of scale
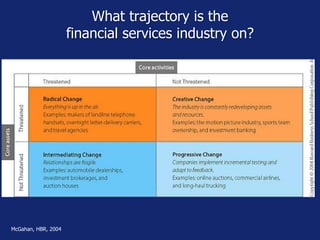
What trajectory is the
financial services industry on?
McGahan, HBR, 2004
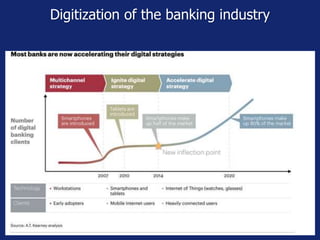
Digitization of the banking industry
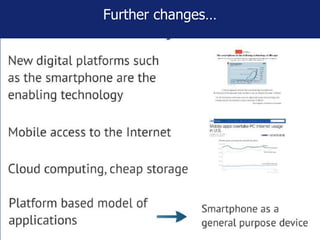
Further changes…
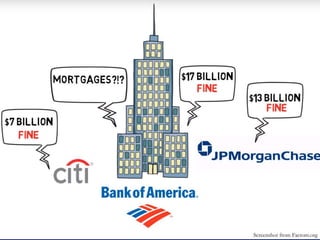
Screenshot from Factom.org
Banking is essential,
but banks are not.
Bill Gates
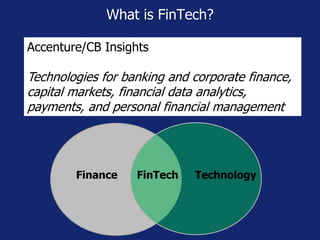
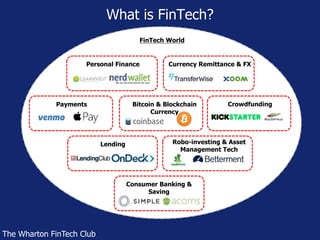
What is FinTech?
Accenture/CB Insights
Technologies for banking and corporate finance,
capital markets, financial data analytics,
payments, and personal financial management
Finance TechnologyFinTech
What is Fintech?
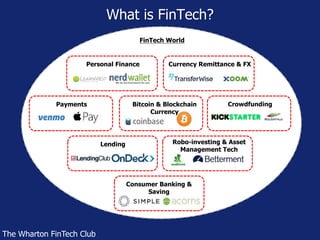
FinTech World
Personal Finance
Payments Bitcoin & Blockchain
Currency
Currency Remittance & FX
Lending
Crowdfunding
Robo-investing & Asset
Management Tech
Consumer Banking &
Saving
The Wharton FinTech Club
What is FinTech?
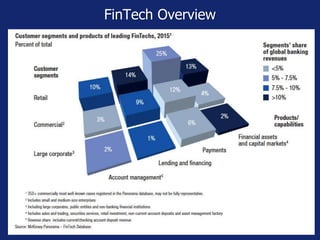
FinTech Overview
http://www.slideshare.net/eteigland
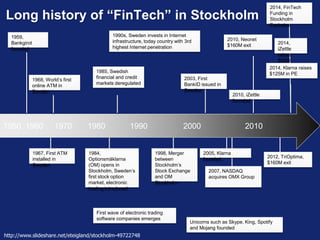
1950 1960 1970 1980 1990 2000 2010
1959,
Bankgirot
founded
1985, Swedish
financial and credit
markets deregulated
1968, World’s first
online ATM in
Sweden
First wave of electronic trading
software companies emerges
2003, First
BankID issued in
Sweden
1990s, Sweden invests in Internet
infrastructure, today country with 3rd
highest Internet penetration
2010, iZettle
founded
2010, Neonet
$160M exit 2014,
iZettle
raises
$55M
2014, Klarna raises
$125M in PE
1967, First ATM
installed in
Sweden
1984,
Optionsmäklarna
(OM) opens in
Stockholm, Sweden’s
first stock option
market, electronic
trading introduced
2012, TriOptima,
$160M exit
2005, Klarna
founded
1998, Merger
between
Stockholm’s
Stock Exchange
and OM
Stockholm
2007, NASDAQ
acquires OMX Group
Unicorns such as Skype, King, Spotify
and Mojang founded
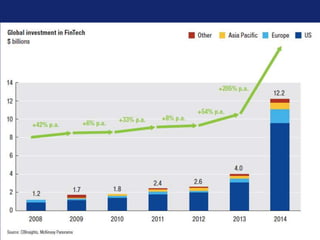
2014, FinTech
Funding in
Stockholm
Explodes
Long history of “FinTech” in Stockholm
http://www.slideshare.net/eteigland/stockholm-49722748
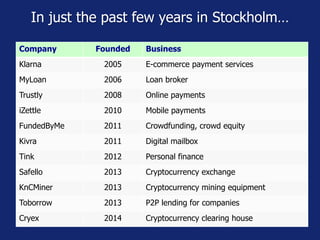
In just the past few years in Stockholm…
Company Founded Business
Klarna 2005 E-commerce payment services
MyLoan 2006 Loan broker
Trustly 2008 Online payments
iZettle 2010 Mobile payments
FundedByMe 2011 Crowdfunding, crowd equity
Kivra 2011 Digital mailbox
Tink 2012 Personal finance
Safello 2013 Cryptocurrency exchange
KnCMiner 2013 Cryptocurrency mining equipment
Toborrow 2013 P2P lending for companies
Cryex 2014 Cryptocurrency clearing house
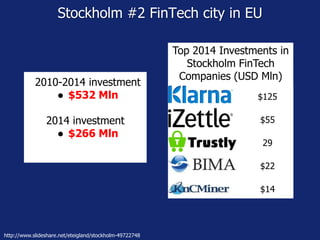
Stockholm #2 FinTech city in EU
2010-2014 investment
● $532 Mln
2014 investment
● $266 Mln
Top 2014 Investments in
Stockholm FinTech
Companies (USD Mln)
Klarna $125
iZettle $55
Trustly 29
Bima Mobile $22
KNC Miner $14
http://www.slideshare.net/eteigland/stockholm-49722748
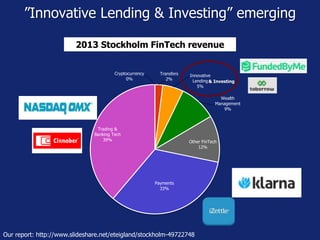
”Innovative Lending & Investing” emerging
2013 Stockholm FinTech revenue
Cryptocurrency
0%
Transfers
2%
Innovative
Lending
5%
Wealth
Management
9%
Other FinTech
12%
Payments
33%
Trading &
Banking Tech
39%
& Investing
Our report: http://www.slideshare.net/eteigland/stockholm-49722748
Crowdfunding rapidly growing in Europe
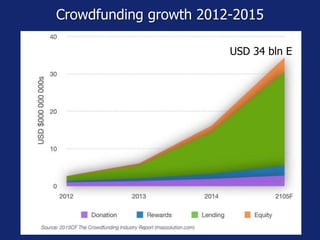
Crowdfunding growth 2012-2015
USD 34 bln E
But in China alone in 2015…
http://www.crowdfundinsider.com/2016/01/79612-report-china-p2p-lending-topped-150-billion-in-2015/
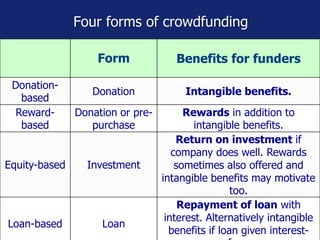
Four forms of crowdfunding
Form Benefits for funders
Donation-
based
Donation Intangible benefits.
Reward-
based
Donation or pre-
purchase
Rewards in addition to
intangible benefits.
Equity-based Investment
Return on investment if
company does well. Rewards
sometimes also offered and
intangible benefits may motivate
too.
Loan-based Loan
Repayment of loan with
interest. Alternatively intangible
benefits if loan given interest-
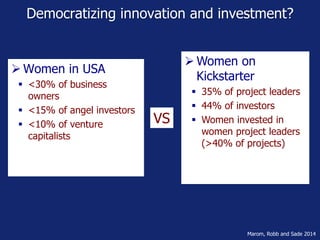
Democratizing innovation and investment?
 Women in USA
 <30% of business
owners
 <15% of angel investors
 <10% of venture
capitalists
Marom, Robb and Sade 2014
 Women on
Kickstarter
 35% of project leaders
 44% of investors
 Women invested in
women project leaders
(>40% of projects)
VS
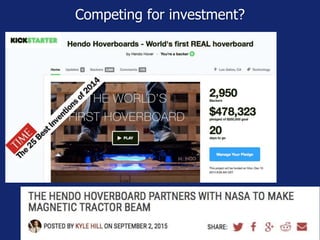
Competing for investment?
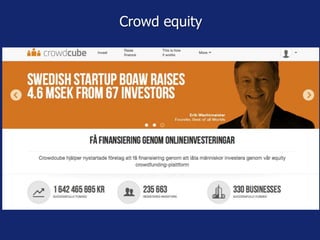
Crowd equity
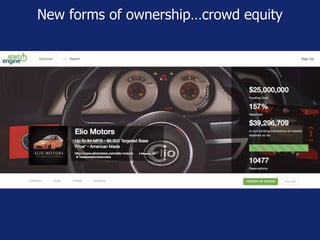
New forms of ownership…crowd equity
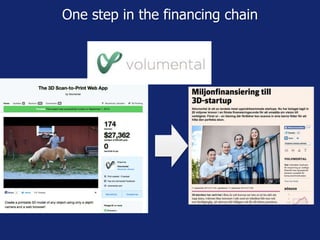
One step in the financing chain
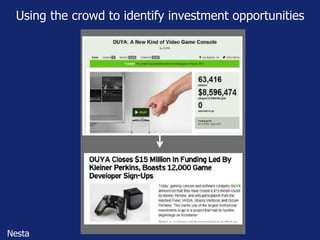
Using the crowd to identify investment opportunities
Nesta
zopa
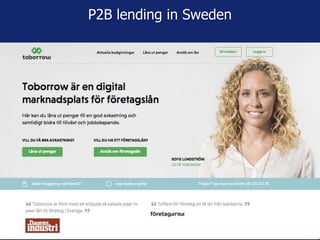
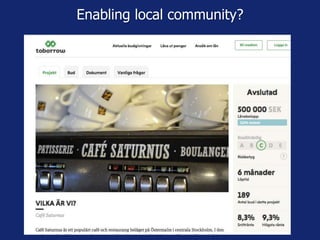
P2B lending in Sweden
Enabling local community?
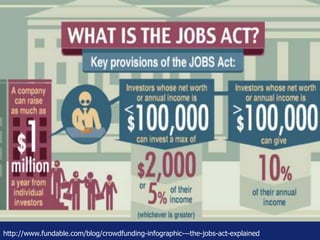
http://www.fundable.com/blog/crowdfunding-infographic---the-jobs-act-explained
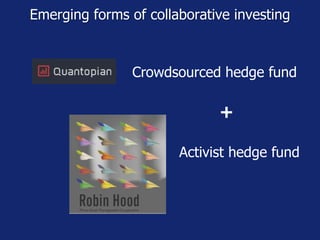
Emerging forms of collaborative investing
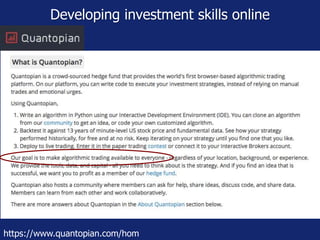
Crowdsourced hedge fund
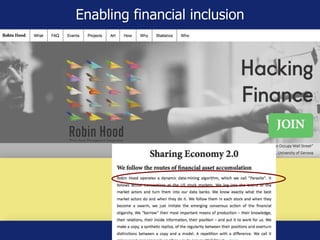
Activist hedge fund
+
Developing investment skills online
https://www.quantopian.com/hom
Enabling financial inclusion
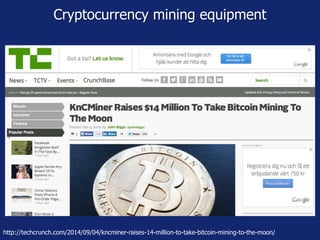
Cryptocurrency mining equipment
http://techcrunch.com/2014/09/04/kncminer-raises-14-million-to-take-bitcoin-mining-to-the-moon/
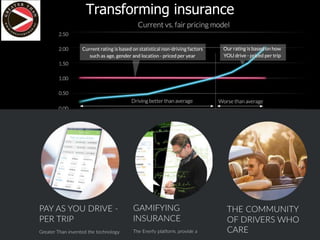
Transforming insurance
What is a cryptocurrency?
 Digital
 Decentralized, peer-to-peer (P2P), i.e., no central,
third party
 Uses cryptography to validate/secure transactions
 Also uses cryptography to generate currency itself
 Non-technical explanation of Bitcoin
− https://www.youtube.com/watch?v=t5JGQXCTe3c
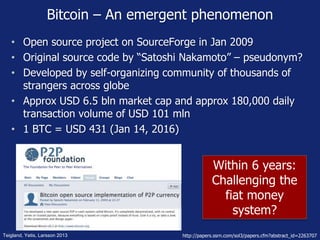
Within 6 years:
Challenging the
fiat money
system?
Bitcoin – An emergent phenomenon
• Open source project on SourceForge in Jan 2009
• Original source code by “Satoshi Nakamoto” – pseudonym?
• Developed by self-organizing community of thousands of
strangers across globe
• Approx USD 6.5 bln market cap and approx 180,000 daily
transaction volume of USD 101 mln
• 1 BTC = USD 431 (Jan 14, 2016)
Teigland, Yetis, Larsson 2013 http://papers.ssrn.com/sol3/papers.cfm?abstract_id=2263707
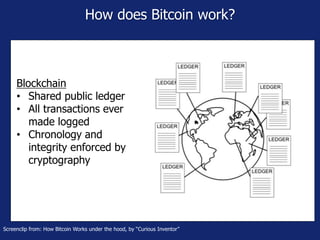
How does Bitcoin work?
Screenclip from: How Bitcoin Works under the hood, by “Curious Inventor”
Blockchain
• Shared public ledger
• All transactions ever
made logged
• Chronology and
integrity enforced by
cryptography
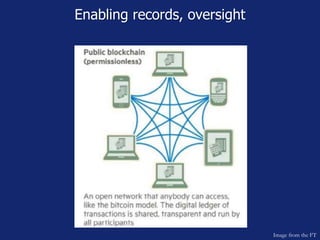
Enabling records, oversight
Image from the FT
Screenshot from the Economist
But also Vendor Transparency AML
and KYC Features…
IoT and smart contracts
 Ownership attached to asset/property (e.g., real
estate, shares) and can be verified
 Run on Bitcoin ledger, execute legal rules between
two entities: people, organizations, machines
 Trustless because no center, no one in middle – the
network is the middleman
 Example: I run a private weather station using
neighbors’ sensors. Smart contracts enable payment
to neighbors for data sent from their sensors to my
weather station.
 But time will tell… uses we cannot imagine today.
https://www.youtube.com/watch?v=JsC4ptn2Aik
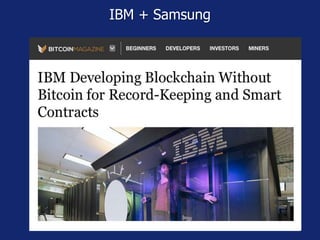
IBM + Samsung
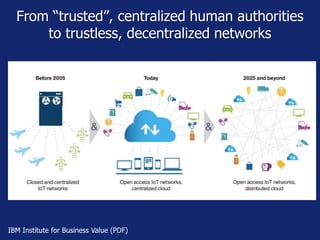
From “trusted”, centralized human authorities
to trustless, decentralized networks
IBM Institute for Business Value (PDF)
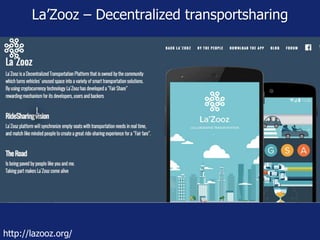
La’Zooz – Decentralized transportsharing
http://lazooz.org/
FinTech World
Personal Finance
Payments Bitcoin & Blockchain
Currency
Currency Remittance & FX
Lending
Crowdfunding
Robo-investing & Asset
Management Tech
Consumer Banking &
Saving
The Wharton FinTech Club
What is FinTech?
FinTech – An increasingly crowded space
• Growing number of entrepreneurs with
experience from established finance industry
• Increasing number of FinTech incubators
• Collaboration among established banks
• Open innovation through open APIs
• Other big non-banking entrants
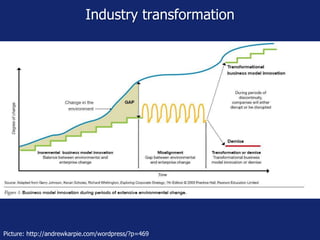
Industry transformation
Picture: http://andrewkarpie.com/wordpress/?p=469
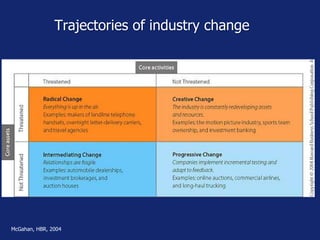
Trajectories of industry change
McGahan, HBR, 2004
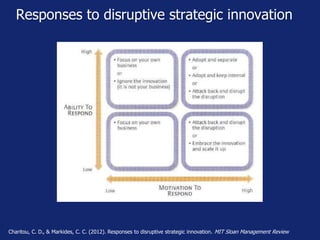
Responses to disruptive strategic innovation
Charitou, C. D., & Markides, C. C. (2012). Responses to disruptive strategic innovation. MIT Sloan Management Review
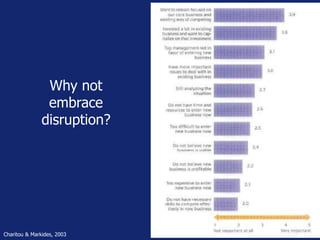
Why not
embrace
disruption?
Charitou & Markides, 2003
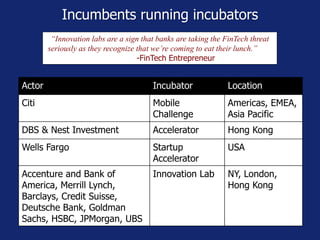
Incumbents running incubators
Actor Incubator Location
Citi Mobile
Challenge
Americas, EMEA,
Asia Pacific
DBS & Nest Investment Accelerator Hong Kong
Wells Fargo Startup
Accelerator
USA
Accenture and Bank of
America, Merrill Lynch,
Barclays, Credit Suisse,
Deutsche Bank, Goldman
Sachs, HSBC, JPMorgan, UBS
Innovation Lab NY, London,
Hong Kong
“Innovation labs are a sign that banks are taking the FinTech threat
seriously as they recognize that we’re coming to eat their lunch.”
-FinTech Entrepreneur
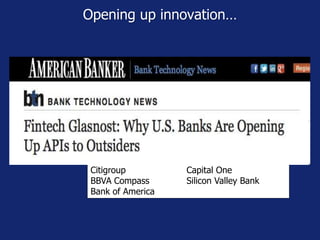
Opening up innovation…
Citigroup Capital One
BBVA Compass Silicon Valley Bank
Bank of America
P2p industyry incumbents
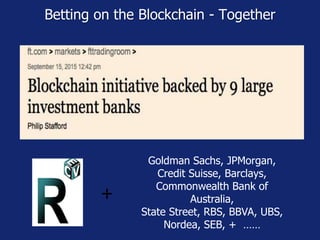
Betting on the Blockchain - Together
Goldman Sachs, JPMorgan,
Credit Suisse, Barclays,
Commonwealth Bank of
Australia,
State Street, RBS, BBVA, UBS,
Nordea, SEB, + ……
+
FinTech challenges
 Regulation
 Privacy
 Security
 Untested in periods of high interest rates,
increased risk, and reduced investment
Previously…
 In the eight-year period between the Netscape IPO
and the acquisition of PayPal (one of the winners of
this era) by eBay, more than 450 attackers – new
digital currencies, wallets, networks, etc. –
attempted to challenge incumbents.
 Fewer than five of these survive as stand-alone
entities today.
McKinsey, 2015
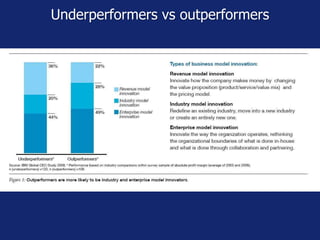
Underperformers vs outperformers
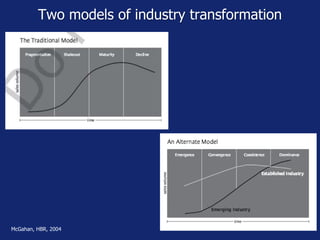
Two models of industry transformation
McGahan, HBR, 2004
Thomas Jefferson (1816)
“Laws and institutions must go hand in hand
with the progress of the human mind.”
The problem is that the human mind itself
can’t keep pace with the advances that
computers are enabling.
http://wadhwa.com/2014/04/15/mit-technology-review-laws-and-ethics-cant-keep-pace-with-technology/
The future is already here,
it’s just not very evenly
distributed.
- William Gibson
Robin Teigland
robin.teigland@hhs.se
www.slideshare.net/eteigland
@robin.teigland
If you love knowledge,
set it free…
If you like this presentation and would like to
contribute to our research, we accept bitcoins:
14hs4JbnQLXE87GGzu84uXGaspmxmnLpwC.
Thank you!!!!!