RISK AND
INSURANCE


  PRINCIPLES OF
   INSURANCE
INSURABLE INTEREST (i.i)
 One major difference
  between insurance
  and gambling is the
  the former has to be
  supported by
  insurable interest.
Subject Matter of Insurance - Contract
 Subject matter of insurance is the life,
  limbs, property, rights or any potential
  legal liability insured under a policy.
 Subject matter of contract is the insured’s
  financial interest in the subject matter of
  insurance.
What is i.i
 The right to insure arising out of legally
  recognized financial interest which a
  person has in the subject matter of
  insurance.
 Which is the financial interest that is
  recognized under the common law or
  statute.
When i.i must exist?
 At the time of inception and at the time of
  loss.
 EXCEPT:
  – Life insurance – at the time of inception
  – Marine – at the time of loss
ASSIGNMENT
      The transfer of rights
       and liabilities by one
       person to another.
      An assignee, the
       person who takes over
       the assignment rights
       will have no better
       rights that those
       enjoyed by the
       assignor.
Exception of the Rule
 Marine Policies
  – Freely assignable by statutory provision. Only
    cargo policies are freely assignable.

 Life Policies
  – Freely assignable by statutory provision
Assignment of Policy Proceeds
 Arises when an insured instructs his
  insurer to pay the policy proceeds to a third
  party.
 The insurer remains a party to the
  insurance contract and continue to assume
  liabilities under it.
 All policy proceeds are freely assignable
  under the policy unless the contract
  provides otherwise.
UTMOST GOOD FAITH (UGF)

 Subject to duty of
  good faith in relation
  to disclosure during
  negotiation.
 The buyer should ask
  questions if the need
  more information
  (caveat emptor – let
  the buyer beware)
Duty of UGF and
          Contractual duty of UGF
 Positive duty (of the insured) to disclosed fully
  and accurately all material facts that he (the
  insured) knows or ought to know, whether asked
  for or not by the insurer.
 The proposal form commonly contain a
  declaration to the effect that the particulars given
  in the proposal is true and correct.
 By signing the form, the proposer warrants the
  truth of this statement.
Material Fact
 A fact which would influence the
  PRUDENT underwriter in accepting the
  risk or fixing the premium.
Duration
 Lasts until the completion of the insurance
  contract.
 If any changes in teh material facts occur
  after they have been intimated to the
  insurer but before the completion of the
  contract, the proposer is required to notify
  the changes to the insurer otherwise the
  contract would be voidable.
Breaches of UGF
 Breaches of UGF is committed the contract is
  voidable.
 Breaches of UGF if:
  - Fails to provide the insurer with information
      relating to the material fact, consider as non-
  disclosure or
  - Misrepresent a material fact, i.e
  incorrect information relating to a
  material fact, termed as
  misrepresentation.
PROXIMATE CAUSE
         When a loss has
          occurred the onus is
          on the insured to
          prove that the loss in
          respect of which a
          claim is made was
          caused by the
          operation of an
          insured peril.
Definition
 The active, efficient cause that sets in
  motion a train of events which brings
  about a result, without the intervention of
  any force started and working from a new
  and independent source.
INDEMNITY
 To make good a loss
  or damage.
 When the insured has
  measurable insurable
  interest the contract of
  insurance will be a
  contract of indemnity.
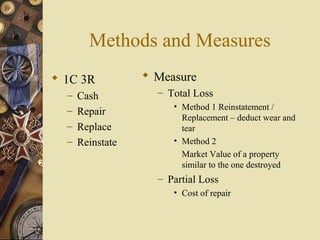
Methods and Measures
 1C 3R          Measure
  – Cash          – Total Loss
                     • Method 1 Reinstatement /
  – Repair
                       Replacement – deduct wear and
  – Replace            tear
  – Reinstate        • Method 2
                       Market Value of a property
                       similar to the one destroyed
                  – Partial Loss
                     • Cost of repair
Factors Limiting Indemnity
 Sum Insured
 Average Condition
 Policy Excess
 Franchise
Policies Which Pay More Than
            Indemnity
 Reinstatement Policies
 Agreed Additional Costs
 Valued Policies
SUBROGATION
 Taking the rights belonging
  to an insured by the insurer
  after the latter has
  indemnified the insured.
 Rights including those
  rights against third parties
  who are also liable for the
  loss which is the subject of
  the claim and the right of
  the insured in the salvage.
Subrogation rights may arise
 Subrogation arising from tort
 Subrogation arising out of contract
 Subrogation arising out of a statute
 Subrogation arising out of salvage
CONTRIBUTION
       The amount which
        each insurer has to
        contribute to the cost
        of a loss when the loss
        is covered by two or
        more insurers
Principle of contribution and
        reason for necessary
 Principle of indemnity – an insurer who has
  indemnified the insures may call upon the other
  insurers who are similarly liable for the loss to
  contribute to the payment of indemnity.
 If the insured is allowed to recover from more
  than one insurer for the same loss, he may
  recover more than the loss, because there is no
  enrichment out of insurance claim.
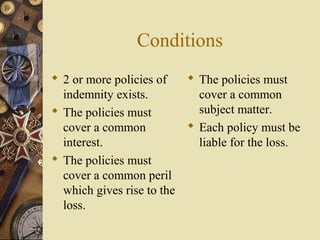
Conditions
 2 or more policies of    The policies must
  indemnity exists.         cover a common
 The policies must         subject matter.
  cover a common           Each policy must be
  interest.                 liable for the loss.
 The policies must
  cover a common peril
  which gives rise to the
  loss.