Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 1
UNIVERSITY OF MYSORE
Department of Studies in Commerce
Manasagangothri, Mysore
“CONSUMER PERCEPTION ON LIFE- A STUDY ON STATE BANK OF INDIA LIFE INSURANCE IN
KRISHNARAJANAGARA”
Project Submitted in partial fulfillment for the award of
MASTER OF COMMERCE
Degree as prescribed by University of Mysore
Submitted by:
JAYANTH KUMAR K.R
Reg. No. CM112031
M.Com. IV Semester
Department of Studies in Commerce
Under the guidance of:
Dr. M. L. ASHOKA
Guide &Faculty
Department of Studies in Commerce
University of Mysore
2013- 2014
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 2
UNIVERSITY OF MYSORE
Dr. H. RAJASHEKAR
Professor & Chairman,
DOS in Commerce,
Manasagangotri,
Mysore.
BONAFIDE CERTIFICATE
This is to certify that that Mr. JAYANTH KUMAR K.R (Register No: (CM112031) is
a student of final year M.Com, DOS in Commerce, Manasagangotri, Mysore during the
academic year 2013-14.
The Project report entitled “CONSUMER PERCEPTION ON LIFE- A STUDY ON
STATE BANK OF INDIA LIFE INSURANCE IN KRISHNARAJANAGARA” is prepared
and submitted by him/her under my guidance in partial fulfillment of the requirements of final
year M.com examination during the academic year 2013-14.
DATE:
PLACE: MYSORE (Dr. H. RAJASHEKAR)
CHAIRMAN
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 3
UNIVERSITY OF MYSORE
Dr.M. L. ASHOKA, M.com, ph.d
Professor,
Faculty of Commerce and Management,
DOS in Commerce,
Manasagangotri,
Mysore.
GUIDE’S CERTIFICATE
This is to certify that Mr. JAYANTH KUMAR K.R (Register No: CM112031) is a
student of final year M.Com, DOS in Commerce, Manasagangotri, Mysore during the academic
year 2013-14.
The Project report entitled “CONSUMER PERCEPTION ON LIFE INSURANCE- A
STUDY ON STATE BANK OF INDIA LIFE INSURANCE IN
KRISHNARAJANAGARA” is prepared and submitted by him under my guidance in partial
fulfillment of the requirements of final year M.com examination during the academic year 2013-
14.
DATE:
PLACE: MYSORE (Dr. M. L. ASHOKA)
Guide & Faculty
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 4
DECLARATION
I Mr. JAYANTH KUMARA K.R (Register No: CM112031) student of final year M.Com,
DOS in Commerce, Manasagangotri, University of Mysore, bearing the Reg. No. CM112031,
hereby declare that the project work entitled " CONSUMER PERCEPTION ON LIFE
INSURANCE- A STUDY ON STATE BANK OF INDIA LIFE INSURANCE IN
KRISHNARAJANAGARA" has been carried out by me entirely under the guidance of
Dr.M.L.ASHOKA.M.com, Ph.d, Faculty of Commerce and Management, DOS in Commerce,
Manasagangotri, Mysore.
Further, I declare that the Project Work submitted in a partial fulfillment for the award of
degree of "MASTER OF COMMERCE" in the DOS IN COMMERCE,
MANASAGANGOTRI, UNIVERSITY OF MYSORE, MYSORE, during the academic year
2013-14. And to the best of my knowledge, the Project Work does not form part of any thesis or
dissertation on the basis of which the degree was conferred on an earlier occasion or any other
candidate.
Date:
Place: Mysore (JAYANTH KUMAR K.R)
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 5
ACKNOWLEDGEMENT
“Happiness cannot be expressed by words, and help taken cannot be left unthankful. I
would like to thank all of them, who were part of my work and my life”
Doing this project is an exciting experience to me. It was not just a part of my academic
curriculum; it is a different exposure, a challenge. A chance to explore a new experience which
involved a lot of running around, interaction with lot of people, learning a lot of new thing so on
and so forth.
The project work would not have been completed without the support and encouragement
of all those, whom I would like to, thank for their help and encouragement in this endeavor.
I was excited when Dr. H. RAJASHEKAR, Professor and Chairman, Department of
studies in commerce, University of Mysore, Manasagangothri, Mysore. Suggested and approved
the subject for my project work. I sincerely thank him for all the help, guidance, support and
encouragement extended to me in completing this research work.
I would like to express my sincere gratitude to DR. M. L. ASHOKA, Guide &Faculty,
DOS in Commerce, Manasagangothri, Mysore, Who absolutely showed great zeal and
enthusiasm in this project work by guiding me, with deep sense of involvement and confidence
in bringing this project report.
My father was main soul for my confidence, determination and strength throughout my
life. Their sweat hopes and wishes have made me able to present this work. So not thanking my
friends and remembering them will be a fault on my part. Their help in every field has made me
possible to present this tedious work. I extend my thanks to all my friends who kindly supported
me in all means.
(JAYANTH KUMAR K.R)
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 6
CONTENTS
CHAPTERS CHAPTER NAME
PAGE
NO.
1 INTRODUCTION 01-08
2 THEORETICAL FRAMEWORK 09-22
3 PROFILE OF THE STUDY 23-83
4 DATA ANALYSIS AND INTERPRETATION 84-107
6 FINDINGS, SUGGESTIONS AND CONCLUSION 108-111
BIBLIOGRAPHY 111-112
ANNEXURE 113-116
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 7
LIST OF TABLES
TABLE NO. TABLE TITLE
PAGE
NO.
2.1 Shows the benifits of insurance 14
2.2 Shows the plans that are appropriate for different life stages 16
3.1 Shows the number of public life and non-life insurance companies 25
3.2 Shows the life insurers in india 34-37
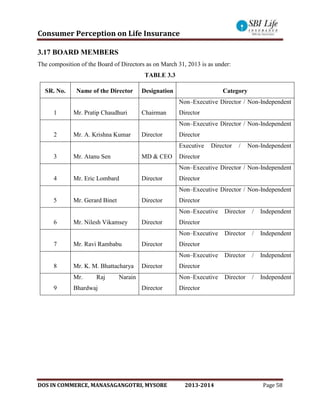
3.3 Shows the board of members of SBI Life Insurance 48
4.1 Shows the Gender wise distribution of respondents 85
4.2
Shows the Age group of respondents 86
4.3
Shows the education knowledge of respondents 87
4.4
Shows the Qualification of respondents 88
4.5
Shows the Occupation of respondents 89
4.6
Shows the Income group of respondents 90
4.7
Shows the respondent’s investment as percentage of annually 91
4.8 Shows the kind of investment preferred by respondents 92
4.9 Shows the reason for choosing SBI life insurance 93
4.10 Shows the Respondents knowing about SBI life insurance 94
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 8
4.11 Shows the Respondents purchasing decision influence 95
4.12
Shows the Respondent’s purpose for buying an insurance policy 96
4.13 Shows the Life insurance plan taken by respondents
97
4.14 Shows the Insurance policies taken by respondents 98
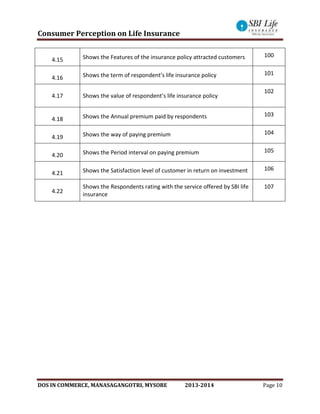
4.15 Shows the Features of the insurance policy attracted customers 100
4.16 Shows the term of respondent’s life insurance policy 101
4.17 Shows the value of respondent’s life insurance policy
102
4.18 Shows the Annual premium paid by respondents 103
4.19 Shows the way of paying premium 104
4.20 Shows the Period interval on paying premium 105
4.21 Shows the Satisfaction level of customer in return on investment 106
4.22
Shows the Respondents rating with the service offered by SBI life
insurance
107
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 9
LIST OF CHARTS
CHART NO. CHART TITLE
PAGE
NO.
4.1 Shows the Gender wise distribution of respondents 85
4.2
Shows the Age group of respondents 86
4.3
Shows the education knowledge of respondents 87
4.4
Shows the Qualification of respondents 88
4.5
Shows the Occupation of respondents 89
4.6
Shows the Income group of respondents 90
4.7
Shows the respondent’s investment as percentage of annually 91
4.8 Shows the kind of investment preferred by respondents 92
4.9 Shows the reason for choosing SBI life insurance 93
4.10 Shows the Respondents knowing about SBI life insurance
94
4.11 Shows the Respondents purchasing decision influence 95
4.12
Shows the Respondent’s purpose for buying an insurance policy 96
4.13 Shows the Life insurance plan taken by respondents
97
4.14 Shows the Insurance policies taken by respondents 98
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 10
4.15 Shows the Features of the insurance policy attracted customers 100
4.16 Shows the term of respondent’s life insurance policy 101
4.17 Shows the value of respondent’s life insurance policy
102
4.18 Shows the Annual premium paid by respondents 103
4.19 Shows the way of paying premium 104
4.20 Shows the Period interval on paying premium 105
4.21 Shows the Satisfaction level of customer in return on investment 106
4.22
Shows the Respondents rating with the service offered by SBI life
insurance
107
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 11
CHAPTER-1
INTRODUCTION
1.1 INTRODUCTION
Life is full of risk and uncertainties. Since we are the social human being we have certain
responsibilities too. Indian consumers have big influence of emotions and rationality on their
buying decisions. They believe in future rather than the present and desire to have a better and
secured future, in these direction insurance services have its own value in terms of minimizing
risk and uncertainties. Insurance is a basic form of risk management which provides protection
against possible loss to life or physical assets. Life insurance is one of the best known insurance
products today. People buy these products as investment tools and also as protection for
themselves and their families. Gradually as competition increased benefits given by industry to
its customers increased by leaps and bounds. Person who seeks protection against such loss is
termed as insured, and company that promises to honor claim, in case such loss is actually
incurred by insured, is termed as Insurer. In order to get insurance, insured is required to pay to
insurance company a certain amount called premium. Premium is collected by insurance
companies which acts as trustee to pool created through contributions made by persons seeking
to protect themselves from common risk. Any loss to the insured in case of happening of an
uncertain event is paid out of this pool.
1.2 BACKGROUND OF THE STUDY
Insurance occupies an important position in the financial sector of an economy. India is
a country where the average selling of Life insurance policies is still lower than many Western
and Asian countries, with the second largest population in world the Indian insurance market is
looking very prospective to many multinational and Indian insurance companies for expanding
their business and market share. Before the opening of Indian market for Multinational
Insurance Companies, Life Insurance Corporation (LIC) was the only company which dealt in
Life Insurance and after opening of this sector to other private companies, all the world leaders
of life insurance has started their operation in India. With their world market experience and
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 12
network, these companies have offered many good schemes to all type of Indian consumers but
unfortunately failed to get the major share of market. Still the LIC is the biggest player in the
life insurance market with approx 72.70% market share (As per IRDA annual report 2012-
2013).
The insurance business in India is projected to reach Rs 4 trillion (US$ 63.01 billion)
in FY 2013–14, according to Mr. TS Vijayan, Chairman, IRDA. Total premiums collected by
the general and the life insurance industry in FY 2012–2013 amounted to Rs 3.75 trillion (US$
59.07 billion). The chairman believes that insurance penetration in India has the potential to
rise to 5–6 percent from the current 3.86 per cent. The life insurance companies are issued
44.1-million new policies in 2012-13 in which Private life insurers had covered 5.02 million
lives and LIC covered 13.2 million lives in the year 2012-13.Customer loyalty depends on
satisfaction of his multiple needs. The main objective of the paper is to study the
policyholder’s perceptions on Life Insurance Policies with reference to Krishnarajanagara in
Karnataka.
1.3 LITERATURE REVIEW
Quality of life consists of various factors including health, community life, gender
equality, political freedom, political stability and security, material well being, family life, and
job security. In addition to it, insurance against illness or death is also considered as indicator for
quality of life in developing countries. Being an indicator of quality of life, insurance has
significance in human life. The literature of attitude and perception of life insurance
policyholders have largely focused on factors predicting these attitudes (Skinner and Dubinsky,
1984; Kruse and Ozdemir, 2004). Factors such as consumers’ perceived value (Kuhlemeyer and
Allen, 1999) and purchase decision-making responsibility (Barron and Staten, 1995) have been
considered as most important them of the literature on attitude and perception of life insurance
policyholders. For example, in a survey of 1,462 families, Skinner and Dubinsky found out that
employment status of the wife and education of the husband discriminate mostly between which
family member(s) is responsible for insurance purchasing decision. Other significant variables
husband‘s employment status, KrusefamilyandOzdemir(2004)income, explore the relationship
between individual‘s-to-pay for increased safety in risk a low-probability, high-consequence
event.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 13
A study conducted by Keerthi, R.Vijayalakshmi (2009) “A Study on the Expectations
and perceptions of the services in private life insurance companies”. Smart the life insurance
companies taken for study, the policy holders’ expectations are well met in the case of certain
factors reacting to service quality. But in the case of other variables, there exists a significant
gap which means that policy holders have experienced low levels of service as against their
expectations. If all the players in the life insurance industry focus on the effective delivery of
services, they can win the hearts of customers and anticipate their increased market share.
A study conducted by S.Raju and M.Gurupandi (2009) article “Analysis of the Socio
economic Back ground and attitude of the policy holders towards life insurance corporation of
india”, Smart journal of Business Management Studies revealed that the study was of great
help to the policy holders, as it was aimed finding the attitude towards the services of LIC
Policy holders. Hence the prospective customers, who propose to buy the insurance products
and avail of the services of an insurance company for the first time, can get benefited by the
best service provider.
A study conducted by Sunayna Khurana (2008)2 article “Customer Preferences in Life
insurance industry in India”, revealed that the insurance sector plays a very important role in
the development of any economy. It is necessary for the economic and overall development of
any country. In today’s competitive economy, the business, finance and insurance sector plays
a very important role. More and more job opportunities are available in these sectors.
Dr.Praveen Sanu, Gaurav Jaiswal, Vijay Kumar Panday (2009)6
in their article, “ A
study of buying behaviour of consumers towards LIC”,
Prestige institute of Management and
Research, Gwalior, revealed that in present Indian market, the investment habits of Indian
consumers are changing very frequently. The individuals have their own perception towards
various types of investment plans. The study of this research work was focused over
consumer’s perception on investment towards Life Insurance Services.
K. Selvavinayagam and R. Mathivanan (2010)7
article has revealed that the competitive
climate in the Indian insurance market has changed dramatically over the last few years. At the
same time, changes have been taking place in the government regulations and technology. The
expectations of policy holders are also changing. The existing insurance companies have to
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 14
introduce many new products in the market, which have competitive advantage over the
products of life insurance companies.
A.Srujan (Insurance marketing July 2004) in his article “Rural insurance market in
India” States that the growth in the insurance sector is higher than the GDP growth rate of the
country. A careful analysis of postal liberalization period suggest that new insurance players
made a good start while the existing one maintained consistent growth level. The two segments
of Indian insurance market i.e., Urban and Rural have their own characteristic features. The
economic growth of the two has not been the same. But there is a fact that most of the new
insurance companies started operating from metros and urban. So they got more opportunity to
cover by several types of insurance. Moreover due to the better educational status they got
awareness about several financial and insurance products. Still there are many opportunities in
rural insurance market.
Gigantic population, growth in income level of rural population, high saving habits etc.
are some plus areas and if we exploit these areas, there in a very good scope for the growth.
Government of India makes steps to improve the conditions of the rural area. Janasree Bima
Yojna, LALGI etc. are some examples. Government made a tie with LIC and made several
scheme for rural people like Siksha Sahayog Yojna, Krishi Shrimik Samajik suraksha Yojna
etc. Anyway it is the opportunities not compulsions which would drive the old and new players
to rural India and the outcome will be steady and secured economic growth.
1.4 STATEMENT OF THE PROBLEM
Investors are confusing because various insurance policies are available in market so this study
will help us to understand the consumer’s perception about life insurance policies with respect to
State Bank of India Life Insurance Company and how a consumer selects, organizes and
interprets the Quality of service and product offered by the company.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 15
1.5 SCOPE OF THE STUDY
The scope of the study is limited to only insurance & no other financial instruments were
considered .The study will help us to know the perception of customers about insurance policies
with reference to State Bank of India life insurance. The various risks involves in buying an
insurance policy and how to tackle it. It will also help us to get a basic knowledge about need
analysis calculation and its requirement.
1.6 NEED FOR THE STUDY
1) The deeper the company understands of consumer’s needs and perception, the earlier the
product is introduced ahead of competition, the greater the expected contribution margin. Hence
the study is very important.
2) Consumer markets and consumer buying behavior can be understood before sound product
and marketing plans are developed.
3) This study will help State Bank of India life insurance Company to customize the service and
product, according to the consumer’s need.
4) This study will also help the company to understand the experience and expectations of the
existing customers.
5) Apart from creating, manufacturing and distribution capabilities for life insurance products,
and in depth study of the consumers, their preferences and demand for their product is very
necessary for setting up an efficient marketing network.
1.7 OBJECTIVE OF THE STUDY
1. To understand the theoretical background of insurance.
2. To study the life insurance products offered by State Bank of India Life Insurance.
3. To examine the existing investment pattern among different age groups, different income
categories and different occupations.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 16
4. To analyze the selection of insurance products of State Bank of India Life Insurance.
1.8 LIMITATIONS
1. The study is limited to Krishnarajanagara only.
2. The study is limited due to constraint of time and information available
3. Possibility of error in data collection because many of respondent may have not given actual
answers of questionnaire.
4. The study had done only on 125 respondents.
5. The study is limited to policy holders of State Bank of India Life Insurance.
1.9 RESEARCH METHODOLOGY
Methodology is the systematic, theoretical analysis of the methods applied to a field of
study. Project or research study methodology gives a clear picture of suitable classification and
sequence of different stage of study as to arrive at proper manifestation of the objective, scope
and limitation of study.
The study is carried out to understand the Consumer Perception about life insurance
policies with reference to State Bank of India Life Insurance in Krishnarajanagara .Exploratory
research is using for this study. This research covers 123 consumers in Krishnarajanagara,
belonging to various age groups, qualification, occupation and income level.
1.9.1 Population:
Population included existing customers of State Bank of India life insurance in
Krishnarajanagara.
1.9.2 Sampling Unit:
Since the data was collected through personal contacts, the sample unit of this survey was the
existing customers of State Bank of India life insurance in Krishnarajanagara, KARNATAKA.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 17
1.9.3 Sampling elements:
Individual respondents were the sampling elements.
1.9.4 Sample Size:
The sample size was 125 customers of State Bank of India Life Insurance Company, from
various parts of the Krishnarajanagara.
1.9.5 Sampling Technique Adopted: Convenient sampling
1.9.6 Analysis:
The data for study was collected both from primary and secondary sources. Percentage and
graphs are used to show the data more clearly.
Out of 125 respondents, data is collected from 123 respondents only.
1.9.7 Tools Used for Data Collection
Self designed questionnaire was used to study the evaluation of factors affecting consumer’s
perception towards State Bank of India Life Insurance.
1.9.8 Tools Used for Data Analysis
To fulfill the objectives of the study percentage analysis, Bar graph and Pie charts are used.
1.10 SOURCE OF DATA
1.10.1 Primary Data:
The primary data are those which are collected afresh and for the first time, and thus happened to
be original in character. There are several methods of collecting primary data particularly in
surveys.
For the study: Questionnaire method is used for collecting the data while conducting the
research.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 18
1.10.2 Secondary Data:
The secondary data are those which have already been collected by someone and which have
already been passed through the statistical process. Secondary data may either be published
data or un- published data.
For this study the secondary data was collected from the following sources.
 Books related to insurance
 Websites related to insurance
1.11 CHAPTERISATION PLAN
1. Introduction
This chapter covers introduction, review of literature, statement of the problem,
objectives of the study, need of the study, scope of the study, research methodology,
sampling design and limitations of the study.
2. Theoretical aspects on Insurance:
This chapter deals with the theoretical aspects of performance management system.
3. Profile of the study:
This chapter deals with the insurance industry of India and company profile of State Bank
of India Life Insurance Company Ltd.
4. Analysis and interpretation of data:
This chapter covers the analysis of data collected through primary and secondary source
to study the topic.
5. Major findings, suggestions and conclusion:
This chapter summarizes and comprises of major findings. It also deals with suggestions
and conclusions.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 19
CHAPTER- 2
THEORETICAL FRAMEWORK
2.1 MEANING OF INSURANCE
Insurance may be described as a social device to reduce or eliminate risk of loss to life
and property. Insurance is a collective bearing of risk. Insurance spreads the risks and losses of
few people among a large number of people as people prefer small fixed liability instead of big
uncertain and changing liability. Insurance is a scheme of economic cooperation by which
members of the community share the unavoidable risks.
Insurance can be defined as a legal contract between two parties whereby one party called
Insurer undertakes to pay a fixed amount of money on the happening of a particular event, which
may be certain or uncertain. The other party called Insure or Insurant pays in exchange a fixed
sum known as premium. The insurer and the insurant are also known as Assurer or Underwriter
and Assurant, respectively. The document which embodies the contract is called the policy.
2.2 DEFINITION
“Insurance is a contract in which sum of money is paid to the assured in consideration
of insurer’s incurring risk of paying a large sum upon a given contingency.” -JUSTICE
TINDALL
“Insurance is a contract by which one party for a compensation called in the premium assumes
particular risks of the other party and promises to pay to him or his nominee a certain sum of
money on a specified contingency.” -E.W.FITTERSON
“Insurance may be described as social device whereby a large group of individuals, through a
system of equitable contribution, may reduce certain measurable risk of economic loss common
to all members of the group.” -ENCYCLOPEDIA BRITANNICA
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 20
2.3 ORIGIN OF INSURANCE
Almost 4,500 years ago, in the ancient land of Babylonia, traders used to bear risk of the caravan
trade by giving loans that had to be later repaid with interest when the goods arrived safely. In
2100 BC, the Code of Hammurabi granted legal status to the practice that, perhaps, was how
insurance made its beginning. Life insurance had its origins in ancient Rome, where citizens
formed burial clubs that would meet the funeral expenses of its members as well as help
survivors by making some payments. As European civilization progressed, its social institutions
and welfare practices also got more and more refined. With the discovery of new lands, sea
routes and the consequent growth in trade, medieval guilds took it upon themselves to protect
their member traders from loss on account of fire, shipwrecks and the like.
Since most of the trade took place by sea, there was also the fear of pirates. So these guilds even
offered ransom for members held captive by pirates. Burial expenses and support in times of
sickness and poverty were other services offered. Essentially, all these revolved around the
concept of insurance or risk coverage. That's how old these concepts are, really In 1347, in
Genoa, European maritime nations entered into the earliest known insurance contract and
decided to accept marine insurance as a practice.
The first step:
Insurance as we know it today owes its existence to 17th century England. In fact, it began
taking shape in 1688 at a rather interesting place called Lloyd's Coffee House in London, where
merchants, ship-owners and underwriters met to discuss and transact business. By the end of the
18th century, Lloyd's had brewed enough business to become one of the first modern insurance
companies.
Enter companies:
The first stock companies to get into the business of insurance were chartered in England in
1720. The year 1735 saw the birth of the first insurance company in the American colonies in
Charleston, SC. In 1759, the Presbyterian Synod of Philadelphia sponsored the first life
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 21
insurance corporation in America for the benefit of ministers and their dependents. However, it
was after 1840 that life insurance really took off in a big way. The trigger: reducing opposition
from religious groups.
The growing years:
The 19th
century saw huge developments in the field of insurance, with newer products being
devised to meet the growing needs of urbanization and industrialization. In 1835, the infamous
New York fire drew people's attention to the need to provide for sudden and large losses. Two
years later, Massachusetts became the first state to require companies by law to maintain such
reserves. The great Chicago fire of 1871 further emphasized how fires can cause huge losses in
densely populated modern cities. The practice of reinsurance, wherein the risks are spread among
several companies, was devised specifically for such situations. There were more offshoots of
the process of industrialization. In 1897, the British government passed the Workmen's
Compensation Act, which made it mandatory for a company to insure its employees against
industrial accidents. With the advent of the automobile, public liability insurance, this first made
its appearance in the 1880s, gained importance and acceptance.
In the 19th
century, many societies were founded to insure the life and health of their members,
while fraternal orders provided low-cost, members-only insurance.
Even today, such fraternal orders continue to provide insurance coverage to members as do most
labour organizations. Many employers sponsor group insurance policies for their employees,
providing not just life insurance, but sickness and accident benefits and old-age pensions.
Employees contribute a certain percentage of the premium for these policies.
In India:
Insurance in India can be traced back to the Vedas. For instance, Yogakshema, the name of Life
Insurance Corporation of India's corporate headquarters, is derived from the Rig Veda. The term
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 22
suggests that a form of "community insurance" was prevalent around 1000 BC and practised by
the Aryans. Burial societies of the kind found in ancient Rome were formed in the Buddhist
period to help families build houses, protect widows and children.
Bombay Mutual Assurance Society, the first Indian life assurance society, was formed in 1870.
Other companies like Oriental, Bharat and Empire of India were also set up in the 1870- 90s. It
was during the Swadeshi movement in the early 20th
century that insurance witnessed a big
boom in India with several more companies being set up.
As these companies grew, the government began to exercise control on them. The Insurance Act
was passed in 1912, followed by a detailed and amended Insurance Act of 1938 that looked into
investments, expenditure and management of these companies' funds. By the mid- 1950s, there
were around 170 insurance companies and 80 provident fund societies in the country's life
insurance scene. However, in the absence of regulatory systems, scams and irregularities were
almost a way of life at most of these companies.
As a result, the government decided nationalise the life assurance business in India. The Life
Insurance Corporation of India was set up in 1956 to take over around 250 life companies. For
years thereafter, insurance remained a monopoly of the public sector. It was only after seven
years of deliberation and debate –after the RN Malhotra Committee report of 1994 became the
first serious document calling for the re-opening up of the insurance sector to private players that
the sector was finally opened up to private players in 2001.
2.4 TYPES OF INSURANCE CONTRACT
 Life insurance
 General insurance
2.4.1 Life Insurance Products
Life insurance is a contract for payment of money to the person assured (or to the person
entitled to receive the same) on the occurrence of an event insured against.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 23
Usually the contract provides for –
Payment of an amount may be on the date of maturity or at specified periodic intervals or
after death, if it occurs earlier.
Periodical payment of insurance premium can be done by the assured to the corporation
who provides the insurance.
2.4.2 General Insurance Products
2.4.2.1 Fire Insurance:
Fire Insurance is a comprehensive policy which covers loss on account of fire, earth
quake, riots, floods, strikes, and malicious intent. It can be taken only by the owner of the
premises to be insured.
2.4.2.2 Motor Insurance:
This covers:
In motor insurance, the rates were revised. Upwards twice, once in 1982 and then in1990
as the high cost of repairs coupled with third party claims had adversely affect the insured loss
ratio. Motor insurance is mandatory leading to good amount of premium collection but it is not
being fancied upon as it could lead to litigation problem.
2.4.2.3 Marine Cargo Insurance: This covers:
a. Cargo in Transit.
b. Cargo Declaration policy.
It includes insurance of Marine Hull Insurance Inland Vessels, Ocean going Vessels, fishing
and scaling vessels, freight at risk, construction of ships, voyage insurance of various vessels,
ship breaking insurance, oil and energy in respect of onshore and offshore risks, including
construction risk.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 24
2.5 BENEFITS OF INSURANCE
TABLE 2.1
Investment option It is good investment option because insurer will not get the insurance
cover but also the in some amount of return.
Tax benefits We can also save tax up to RS 100000.
Loan on insurance Customer can also take loan against insurance policies.
Habits of saving It also develops the habits of saving certain amount of money which
can be helpful in future.
Employment
generation
An increase in the penetration of insurance is going to generate more
employment as insurance policies will require more advisors.
Social benefits It is going to help in developing the infrastructure of the country.
2.6 NEED FOR INSURANCE
Who will take care of my family if tomorrow something unfortunate happens to me?” If
this question bothers us, then Life Insurance is the answer. Of course, under any circumstances,
the loss of a loved one is a traumatic experience. But, if our family is also left without sufficient
money to meet basic living needs or prepare for future goals, they will have to cope with a
financial crisis at the same time. A Life Insurance plan ensures that our family is financially
secure even if tomorrow we are no longer around to care for them. Life insurance, especially
tailored to meet our financial needs.
2.6.1 Need for Life Insurance
Today, there is no shortage of investment options for a person to choose from. Modern
day investments include gold, property, fixed income instruments, mutual funds and of course,
life insurance. Given the plethora of choices, it becomes imperative to make the right choice
when investing our hard-earned money. Life insurance is a unique investment that helps us to
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 25
meet our dual needs - saving for life's important goals, and protecting our assets. Let us look at
these unique benefits of life insurance in detail.
2.6.2 Asset Protection
From an investor's point of view, an investment can play two roles - asset appreciation or
asset protection. While most financial instruments have the underlying benefit of asset
appreciation, life insurance is unique in that it gives the customer the reassurance of asset
protection, along with a strong element of asset appreciation.
The core benefit of life insurance is that the financial interests of one’s family remain
protected from circumstances such as loss of income due to critical illness or death of the
policyholder. Simultaneously, insurance products also have a strong inbuilt wealth creation
proposition. The customer therefore benefits on two counts and life insurance occupies a unique
space in the landscape of investment options available to a customer.
2.6.3 Goal based savings
Each of us has some goals in life for which we need to save. For a young, newly married
couple, it could be buying a house. Once, they decide to start a family, the goal changes to
planning for the education or marriage of their children. As one grows older, planning for one's
retirement will begin to take precedence. Clearly, as our life stage and therefore our financial
goals change, the instrument in which we invest should offer corresponding benefits pertinent to
the new life stage.
Life insurance is the only investment option that offers specific products tailor made for
different life stages. It thus ensures that the benefits offered to the customer reflect the needs of
the customer at that particular life stage, and hence ensures that the financial goals of that life
stage are met.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 26
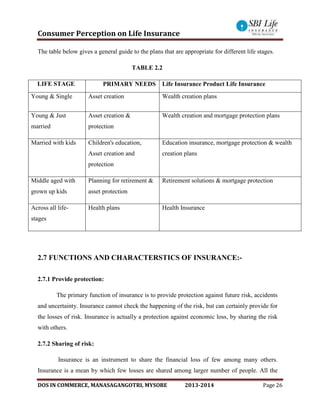
The table below gives a general guide to the plans that are appropriate for different life stages.
TABLE 2.2
g LIFE STAGE PRIPPRIMARY NEEDS Life Insurance Product Life Insurance Product
Young & Single Asset creation Wealth creation plans
Young & Just
married
Asset creation &
protection
Wealth creation and mortgage protection plans
Married with kids Children's education,
Asset creation and
protection
Education insurance, mortgage protection & wealth
creation plans
Middle aged with
grown up kids
Planning for retirement &
asset protection
Retirement solutions & mortgage protection
Across all life-
stages
Health plans Health Insurance
2.7 FUNCTIONS AND CHARACTERSTICS OF INSURANCE:-
2.7.1 Provide protection:
The primary function of insurance is to provide protection against future risk, accidents
and uncertainty. Insurance cannot check the happening of the risk, but can certainly provide for
the losses of risk. Insurance is actually a protection against economic loss, by sharing the risk
with others.
2.7.2 Sharing of risk:
Insurance is an instrument to share the financial loss of few among many others.
Insurance is a mean by which few losses are shared among larger number of people. All the
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 27
insured contribute the premiums towards a fund and out of which the persons exposed to a
particular risk is paid.
2.7.3 Small capital to cover larger risk:
Insurance relieves the businessmen from security investments, by paying small amount
of premium against larger risks and uncertainty.
2.7.4 Contribute towards the Development of country:
Insurance provides development opportunity to those larger industries having more
risks in their setting up. Even the financial institutions may be prepared to give credit to sick
industrial units which have insured their assets including plant and machinery.
2.7.5 Means of savings and investment:
Insurance serves as savings and investment, insurance is a compulsory way of savings
and it restricts the unnecessary expenses by the insured's For the purpose of availing income-
tax exemptions also, people invest in insurance.
2.8 STAGES IN POLICY INSUANCE
1. Proposal: A Proposal stage is the first stage before the policy is issued at COPS. At this stage, the
application form is received by COPS, but it is pending for issuance due to further clarifications
required from the customer.
2. Login: A Proposal which is complete i.e., duly filled with all necessary documents attached to it
and accepted by the branch cops is called a login.
3. Reject: An Application gets rejected at the branch cops level due to necessary details not filled in
the form or necessary documents not submitted is a Reject. It is then sent back to the advisor for
completion.
4. Issuance: Issuance means a policy that is issued to the customer central cops.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 28
5. Decline status: When a customer refuses to take a policy post login but before issuance is called
a Decline.
6. Cancellation: When the Cheque given by the customer bounces, it amounts to the cancellation of
the policy.
7. Lapse: A Policy for which the customer fails to pay subsequent premiums is a lapsed policy.
8. Free look: Post issuance of the policy, the policyholder has the option to turn down the policy
within 15 days from the date of issuance. This period of 15 days is called Free look period.
9. Surrender: When a customer wants to discontinue with the policy.
2.9 LIFE INSURANCE
Life insurance is a contract under which the insurer (Insurance Company) in Consideration of
a premium paid undertakes to pay a fixed sum of money on the death of the insured or on the expiry of
a specified period of time whichever is earlier. In case of life insurance, the payment for life insurance
policy is certain. The Event insured against is sure to happen only the time of its happening is not
known. So life insurance is known as “Life Assurance”. The subject matter of insurance is life of
human being. Life insurance provides risk coverage to the life of a person. On death of the person
insurance offers protection against loss of income and compensate the titleholders of the policy.
2.10 DEFINITION
“A contract of life assurance is that in which one party agrees to pay a given sum on the
happening of a particular event contingent upon the duration of human life in consideration of
immediate payment of a smaller sum by another.”
A protection against the loss of income that would result if the insured passed away. The
named beneficiary receives the proceeds and is thereby safeguarded from the financial impact of
the death of the insured.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 29
2.11 TYPES OF LIFE INSURANCE
1. Term Insurance Policy
2. Whole life Insurance Policy
3. Endowment Policy
4. Pure Endowment Policy
5. Money Back Policy
Most of the products offered by Indian life insurers are developed and structured around
these "basic" policies and are usually an extension or a combination of these policies.
2.11.1 Term Insurance Policy:
A term insurance policy is a pure risk cover for a specified period of time. What this
means is that the sum assured is payable only if the policyholder dies within the policy term. For
instance, if a person buys Rs 2 lakh policy for 15-years, his family is entitled to the money if he
dies within that 15-year period. There is no element of savings or investment in such a policy. It
is a 100 per cent risk cover. It simply means that a person pays a certain premium to protect his
family against his sudden death. He forfeits the amount if he outlives the period of the policy.
This explains why the Term Insurance Policy comes at the lowest cost.
2.11.2 Whole life Insurance Policy
As the name suggests, a Whole Life Policy is an insurance cover against death, irrespective of
when it happens. Under this plan, the policyholder pays regular premiums until his death,
following which the money is handed over to his family. This policy, however, fails to fulfill the
additional needs of the insured during his post-retirement years. It doesn't take into account a
person's increasing needs either. While the insured buys the policy at a young age, his
requirements increase over time. By the time he dies, the value of the sum assured is too low to
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 30
meet his family's needs. As a result of these drawbacks, insurance firms now offer either a
modified Whole Life Policy or combine in with another type of policy.
2.11.3 Endowment Policy
Combining risk cover with financial savings, endowment policies is the most popular policies in
the world of life insurance.
 In an Endowment Policy, the sum assured is payable even if the insured survives the
policy term.
 If the insured dies during the tenure of the policy, the insurance firm has to pay the sum
assured just as any other pure risk cover.
2.11.4 Pure Endowment Policy:
A pure endowment policy is also a form of financial saving, whereby if the person covered
remains alive beyond the tenure of the policy; he gets back the sum assured with some other
investment benefits.
2.11.5 Money Back Policy
These policies are structured to provide sums required as anticipated expenses (marriage,
education, etc) over a stipulated period of time. With inflation becoming a big issue, companies
have realized that sometimes the money value of the policy is eroded. That is why with-profit
policies are also being introduced to offset some of the losses incurred on account of inflation.
 A portion of the sum assured is payable at regular intervals. On survival the remainder of
the sum assured is payable.
 In case of death, the full sum assured is payable to the insured.
 The premium is payable for a particular period of time..
In addition to the basic policy, insurers offer various benefits such as double endowment and
marriage/ education endowment plans. The cost of such a policy is slightly higher but worth its
value.1
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 31
2.12 ROLE OF THE LIFE INSURANCE
1. Life insurance as an investment: - Insurance products yield more than any other
investment instruments and it also provides added incentives or bonus offered by insurance
companies.
2. Life insurance as risk cover:- Insurance is all about risk cover and protection of life.
Insurance provides a unique sense of security that no other form of invest can provide.
3. Life insurance as tax planning:- Insurance serves as an excellent tax saving mechanism.
Government gives tax relaxation on every life insurance policy.
2.12 IMPORTANCE OF THE LIFE INSURANCE
1. Protection against untimely death: - Life insurance provides protection to the
dependents of the life insured and the family of the assured in case of his untimely
death. The dependents or family members get a fixed sum of money in case of death of
the assured.
2. Saving for old age: - After retirement the earning capacity of a person reduces. Life
insurance enables a person to enjoy peace of mind and a sense of security in his/her old
age.
3. Promotion of savings: - Life insurance encourages people to save money
compulsorily. When life policy is taken, the assured is to pay premiums regularly to
keep the policy in force and he cannot get back the premiums, only surrender value can
be returned to him. In case of surrender of policy, the policyholder gets the surrendered
value only, after the expiry of duration of the policy.
4. Initiates investments: - Life Insurance Corporation encourages the public savings and
canalizes the same in various investments for the economic development of the
country. Life insurance is an important tool for the collection of small savings.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 32
5. Credit worthiness: - Life insurance policy can be used as a security to raise loans. It
improves the credit worthiness of business.
6. Social Security: - Life insurance is important for the society as a whole also. Life
insurance enables a person to provide for education and marriage of children and for
construction of house. It helps a person to make financial base for future.
7. Tax Benefit: - Under the Income Tax Act, premium paid is allowed as a deduction
from the total income under section 80C.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 33
CHAPTER-3
PROFILE OF THE STUDY
3.1 INDIAN INSURANCE INDUSTRY
The Insurance sector in India governed by Insurance Act, 1938, the Life Insurance
Corporation Act, 1956 and General Insurance Business (Nationalization) Act, 1972, Insurance
Regulatory and Development Authority (IRDA) Act, 1999 and other related Acts. With such a
large population and the untapped market area of this population Insurance happens to be a very
big opportunity in India. Today it stands as a business growing at the rate of 15-20 per cent
annually. Together with banking services, it adds about 7 per cent to the country’s GDP .In spite of
all this growth the statistics of the penetration of the insurance in the country is very poor. Nearly
80% of Indian populations are without Life insurance cover and the Health insurance. This is an
indicator that growth potential for the insurance sector is immense in India. It was due to this
immense growth that the regulations were introduced in the insurance sector and in continuation
“Malhotra Committee” was constituted by the government in 1993 to examine the various aspects
of the industry. The key element of the reform process was Participation of overseas insurance
companies with 26% capital. Creating a more efficient and competitive financial system suitable
for the requirements of the economy was the main idea behind this reform. Since then the
insurance industry has gone through many sea changes .The competition LIC started facing from
these companies were threatening to the existence of LIC .since the liberalization of the industry
the insurance industry has never looked back and today stand as the one of the most competitive
and exploring industry in India. The entry of the private players and the increased use of the new
distribution are in the limelight today. The use of new distribution techniques and the IT tools has
increased the scope of the industry in the longer run.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 34
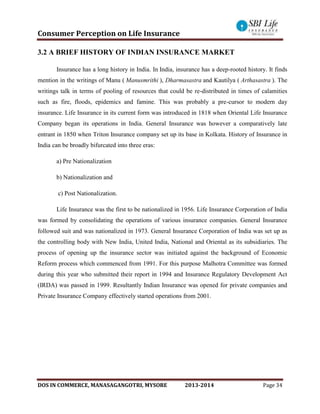
3.2 A BRIEF HISTORY OF INDIAN INSURANCE MARKET
Insurance has a long history in India. In India, insurance has a deep-rooted history. It finds
mention in the writings of Manu ( Manusmrithi ), Dharmasastra and Kautilya ( Arthasastra ). The
writings talk in terms of pooling of resources that could be re-distributed in times of calamities
such as fire, floods, epidemics and famine. This was probably a pre-cursor to modern day
insurance. Life Insurance in its current form was introduced in 1818 when Oriental Life Insurance
Company began its operations in India. General Insurance was however a comparatively late
entrant in 1850 when Triton Insurance company set up its base in Kolkata. History of Insurance in
India can be broadly bifurcated into three eras:
a) Pre Nationalization
b) Nationalization and
c) Post Nationalization.
Life Insurance was the first to be nationalized in 1956. Life Insurance Corporation of India
was formed by consolidating the operations of various insurance companies. General Insurance
followed suit and was nationalized in 1973. General Insurance Corporation of India was set up as
the controlling body with New India, United India, National and Oriental as its subsidiaries. The
process of opening up the insurance sector was initiated against the background of Economic
Reform process which commenced from 1991. For this purpose Malhotra Committee was formed
during this year who submitted their report in 1994 and Insurance Regulatory Development Act
(IRDA) was passed in 1999. Resultantly Indian Insurance was opened for private companies and
Private Insurance Company effectively started operations from 2001.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 35
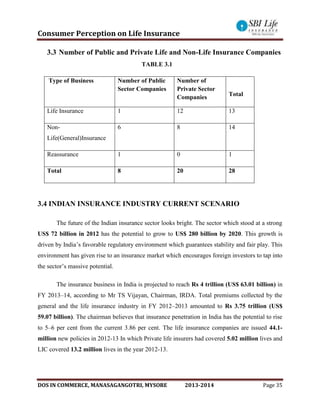
3.3 Number of Public and Private Life and Non-Life Insurance Companies
TABLE 3.1
Type of Business Number of Public
Sector Companies
Number of
Private Sector
Companies Total
Life Insurance 1 12 13
Non-
Life(General)Insurance
6 8 14
Reassurance 1 0 1
Total 8 20 28
3.4 INDIAN INSURANCE INDUSTRY CURRENT SCENARIO
The future of the Indian insurance sector looks bright. The sector which stood at a strong
US$ 72 billion in 2012 has the potential to grow to US$ 280 billion by 2020. This growth is
driven by India’s favorable regulatory environment which guarantees stability and fair play. This
environment has given rise to an insurance market which encourages foreign investors to tap into
the sector’s massive potential.
The insurance business in India is projected to reach Rs 4 trillion (US$ 63.01 billion) in
FY 2013–14, according to Mr TS Vijayan, Chairman, IRDA. Total premiums collected by the
general and the life insurance industry in FY 2012–2013 amounted to Rs 3.75 trillion (US$
59.07 billion). The chairman believes that insurance penetration in India has the potential to rise
to 5–6 per cent from the current 3.86 per cent. The life insurance companies are issued 44.1-
million new policies in 2012-13 In which Private life insurers had covered 5.02 million lives and
LIC covered 13.2 million lives in the year 2012-13.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 36
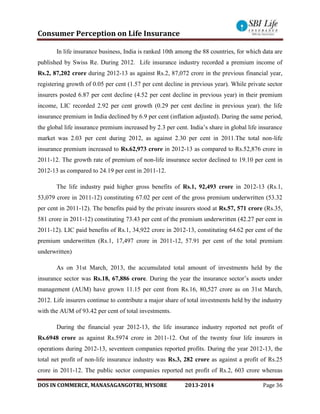
In life insurance business, India is ranked 10th among the 88 countries, for which data are
published by Swiss Re. During 2012. Life insurance industry recorded a premium income of
Rs.2, 87,202 crore during 2012-13 as against Rs.2, 87,072 crore in the previous financial year,
registering growth of 0.05 per cent (1.57 per cent decline in previous year). While private sector
insurers posted 6.87 per cent decline (4.52 per cent decline in previous year) in their premium
income, LIC recorded 2.92 per cent growth (0.29 per cent decline in previous year). the life
insurance premium in India declined by 6.9 per cent (inflation adjusted). During the same period,
the global life insurance premium increased by 2.3 per cent. India’s share in global life insurance
market was 2.03 per cent during 2012, as against 2.30 per cent in 2011.The total non-life
insurance premium increased to Rs.62,973 crore in 2012-13 as compared to Rs.52,876 crore in
2011-12. The growth rate of premium of non-life insurance sector declined to 19.10 per cent in
2012-13 as compared to 24.19 per cent in 2011-12.
The life industry paid higher gross benefits of Rs.1, 92,493 crore in 2012-13 (Rs.1,
53,079 crore in 2011-12) constituting 67.02 per cent of the gross premium underwritten (53.32
per cent in 2011-12). The benefits paid by the private insurers stood at Rs.57, 571 crore (Rs.35,
581 crore in 2011-12) constituting 73.43 per cent of the premium underwritten (42.27 per cent in
2011-12). LIC paid benefits of Rs.1, 34,922 crore in 2012-13, constituting 64.62 per cent of the
premium underwritten (Rs.1, 17,497 crore in 2011-12, 57.91 per cent of the total premium
underwritten)
As on 31st March, 2013, the accumulated total amount of investments held by the
insurance sector was Rs.18, 67,886 crore. During the year the insurance sector’s assets under
management (AUM) have grown 11.15 per cent from Rs.16, 80,527 crore as on 31st March,
2012. Life insurers continue to contribute a major share of total investments held by the industry
with the AUM of 93.42 per cent of total investments.
During the financial year 2012-13, the life insurance industry reported net profit of
Rs.6948 crore as against Rs.5974 crore in 2011-12. Out of the twenty four life insurers in
operations during 2012-13, seventeen companies reported profits. During the year 2012-13, the
total net profit of non-life insurance industry was Rs.3, 282 crore as against a profit of Rs.25
crore in 2011-12. The public sector companies reported net profit of Rs.2, 603 crore whereas
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 37
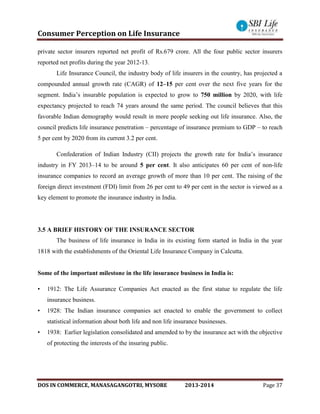
private sector insurers reported net profit of Rs.679 crore. All the four public sector insurers
reported net profits during the year 2012-13.
Life Insurance Council, the industry body of life insurers in the country, has projected a
compounded annual growth rate (CAGR) of 12–15 per cent over the next five years for the
segment. India’s insurable population is expected to grow to 750 million by 2020, with life
expectancy projected to reach 74 years around the same period. The council believes that this
favorable Indian demography would result in more people seeking out life insurance. Also, the
council predicts life insurance penetration – percentage of insurance premium to GDP – to reach
5 per cent by 2020 from its current 3.2 per cent.
Confederation of Indian Industry (CII) projects the growth rate for India’s insurance
industry in FY 2013–14 to be around 5 per cent. It also anticipates 60 per cent of non-life
insurance companies to record an average growth of more than 10 per cent. The raising of the
foreign direct investment (FDI) limit from 26 per cent to 49 per cent in the sector is viewed as a
key element to promote the insurance industry in India.
3.5 A BRIEF HISTORY OF THE INSURANCE SECTOR
The business of life insurance in India in its existing form started in India in the year
1818 with the establishments of the Oriental Life Insurance Company in Calcutta.
Some of the important milestone in the life insurance business in India is:
• 1912: The Life Assurance Companies Act enacted as the first statue to regulate the life
insurance business.
• 1928: The Indian insurance companies act enacted to enable the government to collect
statistical information about both life and non life insurance businesses.
• 1938: Earlier legislation consolidated and amended to by the insurance act with the objective
of protecting the interests of the insuring public.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 38
• 1956: 245 Indian and foreign insurers and provident societies taken over by the central
government and nationalized .LIC formed by an act of parliament, viz LIC Act, 1956, with a
capital contribution of Rs 5 crore from the government of India.
• The General insurance business in India, on the other hand, can trace its roots to the Triton
Insurance Company Ltd the first general insurance company established in the year 1850 in
Calcutta by the British.
3.5.1 General insurance business in India is
• 1907: The Indian Mercantile Insurance Ltd set up the first company to transact all classes of
general insurance business.
• 1957: General Insurance Council, a wing of the insurance Association pf India, frames a
code of the conduct for ensuring fair conduct and sound business practices.
• 1968: The Insurance Act amended to regulate investments and set minimum solvency.
3.5.2 Margins and the Tariff Advisory Committee set up
• 1972: The general insurance Business Act nationalized the general insurance business in
India with effect from 1st
January 1973.107 insurers amalgamated and grouped into four
companies viz the national insurance company Ltd ,the New India Assurance Company Ltd
,the Oriental Insurance Company Ltd and the United India Insurance Company Ltd .GIC
incorporated as a company.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 39
3.6 INSURANCE SECTOR REFORMS
In 1993 Malhotra committee headed by former finance secretary and RBI governor R. N.
Malhotra was formed to evaluate the Indian insurance industry and recommend its future
direction.
The Malhotra committee was set up with the objective of complementing the reforms
initiated in the financial sector. The reforms were aimed at “creating the reforms more efficient
and competitive financial system suitable for the requirements of the economy keeping in mind
the structural changes currently underway and recognizing that insurance to address the need for
similar reforms”.
In 1994 the committee submitted the report and some of the key recommendations included.
1. Structure
Government stake in the insurance companies to be brought down to 50%. Government
should take over the holdings of GIC and its subsidiaries so that these subsidiaries can act as
independent corporations.
All the insurance companies should be given greater freedom to operate.
2. Competition
• Private companies with a minimum paid up capital of Rs 1 Bn should be allowed to enter the
industry No Company should deal in both Life and General Insurance through a single entity.
• Foreign companies may be allowed to enter the industry in collaboration with the domestic
companies.
• Postal Life Insurance should be allowed to operate in the rural market
• Only on state level Life Insurance Company should be allowed to operate in each state.
3. Regulatory Body
• The Insurance Act should be changed.
• An Insurance Regulatory body should be set up.
• Controller of insurance (currently a part from the finance ministry) should be made independent.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 40
4. Investments
• Mandatory Investments of LIC Fund in government securities to be reduced from 75% to 50%.
• GIC and its subsidiaries are not to hold more than 5 % in any company (there current holdings to
be brought down to this level over a period of time).
5. Customer service
• LIC should pay interest on delays in payments beyond 30 days.
• Computerization of operations and updating of technology to be carried out in the insurance
industry. The committee emphasized that in order to improve the customer services and increase
the coverage of the insurance industry should be opened up to competition.
• But at the same time the committee felt the need to exercise caution as any failure on the part of
new players could ruin the public confidence in the industry. Hence, it was decided to allow
competition in a limited way by stipulating the minimum capital requirements of Rs 100 crores.
• The committee felt the need to provide greater autonomy to insurance companies in order to
improve their performance and enable to act as independent companies with economic motives.
For this purpose, it had proposed setting up an independent regulatory body.
3.7 BANK AND INSURANCE
Bank assurance symbolizes the convergence of banking and insurance has its origins in
France and involves distribution of insurance products through a bank’s branch network. While
banc assurance has developed into a tremendous success story in Europe, it is a relatively new
concept in Australia and Asia.
Most new insurers have entered into memoranda of understanding with banks to use their
branches as outlets for marketing standard products. State Bank of India, vysya Bank and J&K
Bank already have joint ventures in life insurance. Vijaya Bank and Punjab National Bank are in
the midst of finalizing life and non-life ventures.
The Insurance Act allows only those companies registered under the companies Act to
become corporate agents. This gives the new generation and old private sector banks a head start
over public sector banks, which are technically not eligible to sell risk products.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 41
IRDA, IBA&RBI are in discussions to iron out the various issues, as public sector banks
will play a key role in the distribution of products.
3.8 ROLE OF INSURANCE IN ECONOMIC DEVELOPMENT
For economic development, investments are necessary. Investments are made out of
savings. A life insurance company is a major instrument for the mobilization of savings of
people, particularly from the middle and lower income groups. These savings are channeled into
investments foe economic growth. All good life insurance companies have huge funds,
accumulated through the payments of small amount of premium of individuals. These funds are
invested in ways that contribute substantially for the economic development of the countries in
which they do business. All good life insurance companies have huge funds, accumulated
through the payments of small amount of premia of individuals. These funds are invested in
ways that contribute substantially for the economic development of the countries in which they
do business. The private insurers in India are new and had not built up funds in 2002. But, in
course of time, they also would be directly and indirectly contributing to the country’s economic
development.
A life insurance company will have large funds. These amounts are collected by way of
premiums. Every premium represents a risk that is covered by that premium. In effect, therefore,
these vast amounts represent pooling of risks. The funds are collected and held in trust for the
benefit of the policyholders. The management of life insurance companies is required to keep
this aspect in mind and make all its decisions in ways that benefit the community. This applies
also to its investments. That is why successful insurance companies would not be found
investing in speculative ventures. Apart from investments, business and trade benefit through
insurance. Without insurance, trade and commerce will find it difficult to face the impact of
major perils like fire, earthquake, floods, etc. Financiers, like banks, would collapse if the
factory, financed by it, is reduced to ashes by a terrible fire. Insurers cover also the loss to
financiers, if their debtors default.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 42
3.9 INSURANCE REGULATIORY AND DEVEVLOPMENT AUTHORITY
(IRDA):-
The opening of insurance sector has been long standing and development authority-IRDA
bill a significant step has been taken.
IRDA is formed as an authority to protect the interest of holders of insurance policies, to
regulate, promote and ensure orderly growth of insurance industry and for matters connected
there with incidental thereto.
3.9.1 Composition of authority under IRDA, Act, 1999
As per the section 4 of IRDA Act ‘1999, insurance Regulatory and development
Authority (IRDA, which was constituted by an act of parliament) specify the composition of
authority. The authority is ten-member team consisting of,
1) A chairman
2) 5 whole team members
3) 4 part time members
3.9.2 Duties, powers and functions of IRDA
Section 14 of IRDA Act, 1999 lays down the duties, powers and functions of IRDA.
1) Subject to the provisions of this act and any other law for the time being in force, the authority
shall have the duty to regulate, promote ensure orderly growth of the insurance business and re-
insurance business.
2) Without prejudice to the generality of the provisions contained in sub-section (1) the power
and functions of the authority shall include
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 43
a) Issue to the applicant a certificate of registration, renew, modify, withdraw, suspend or cancel
such registration.
b) Protection of the interests of the policy holders in matters concerning assigning of policy,
nomination by policy holders, insurable interests, settlement of insurance claim, surrender value
of policy and other terms and conditions of contracts of insurance.
c) Specifying requisite qualification, code of conduct and practical training for intermediary or
insurance intermediaries and agent.
d) Specifying the code of conduct for surveyors and loss assessors.
e) Promoting efficiency in the conduct of insurance business
f) Promoting and regulating professional organizations connected with the insurance.
g) Levying fees and other charges for carrying out the purposes of this Act.
h) Calling for information from, undertaking inspection of, conducting enquiries and
investigations including audit of the insurers, intermediaries, insurance intermediaries and other
organizations connected with the insurance business.
i) Control and regulation of the rates, advantages, terms and conditions that may be offered by
insurers in respect of general insurance business not so controlled and regulated by the tariff
advisory committee under section 64u of the insurance Act, 1938(4 of 1938).
h) Specifying the form and manner in which books of account shall be maintained and insurers
and other insurance intermediaries shall render statement of accounts.
j) Regulating maintenance of margin of solvency.
k) Adjudication of disputes between insurers and intermediaries or insurance intermediaries.
l) Supervising the functioning of the Tariff Advisory Committee.
m) Specifying the percentage of premium income of the insurer to finance schemes for
promoting and regulating professional organizations referred to in clause (f).
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 44
o) Specifying the percentage of life insurance business and general insurance business to be
understood by the insurer in the rural or social sector.
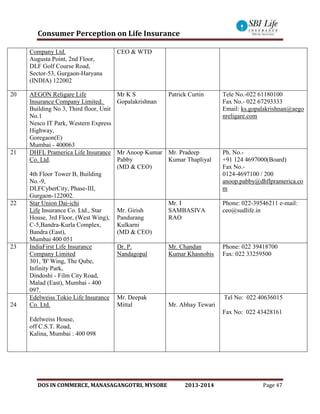
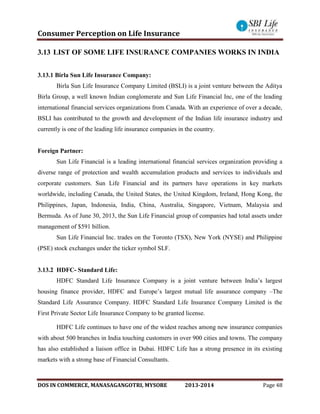
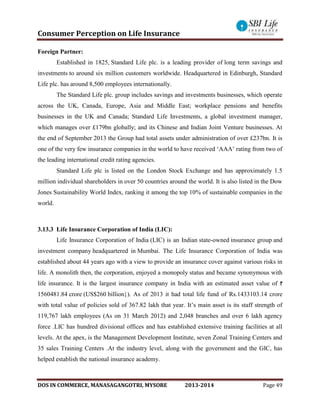
3.10 LIFE INSURERS
TABLE 3.2
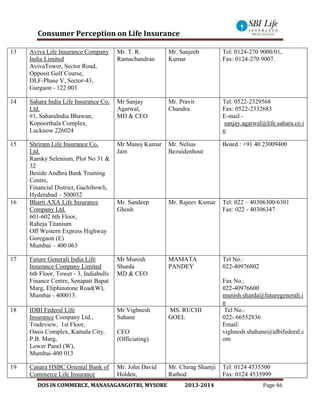
S.No NAME OF THE COMPANY NAME OF
PRINCIPAL
OFFICER
NAME OF
APPOINTED
ACTUARY
TELEPHONE NO./FAX No./E-
MAIL & WEB ADDRESS
1. Bajaj Allianz Life Insurance
Company Limited .
GE Plaza, Airport Road ,
YerawadaPune 411 006
Mr Anuj Agarwal Dhulipala
SAISRINIVAS
Tel : 020-66026777
Fax : 020 -66026789
2. Birla Sun Life Insurance Co.
Ltd
Reg. Office: One India Bulls
Centre, Tower 1, 16th Floor,
Jupiter Mill Compound, 841 ,
Senapati Bapat Marg,
Elphinstone Road,
Mumbai-400013.
Mr Pankaj
Razdan
MD & CEO
ANIL KUMAR
SINGH Tel: +91 22 67239100
Email: pankaj.razdan@adityabir
la.com
Toll-free:1-800-270-7000
Email
:customerservice@birlasunlife.c
om
3. HDFC Standard Life Insurance
Co. Ltd
19th Floor, Lodha Excelus,
Apollo Mills Compound,
N.M. Joshi Road,
Mahalaxmi,
Mumbai - 400 011
Mr. Amitabh
Chaudhry
Mr. Srinivasan
Parthasarathy
Tel : 022-67516666
4. ICICI Prudential Life Insurance
Co. Ltd
ICICIPrulifeTowers , 1089,
Appasaheb Marathe Marg,
Prabhadevi,
Mumbai 400 025.
Mr. Sandeep
Bakhshi
SATYAN
JAMBUNATHAN
Telephone no. : (022) 40391600
Fax no.: (022) 66622031
5. ING Vysya Life Insurance
Company Ltd.
ING Vysya Home, 5th
Floor, #22 Mahatma gandhi
Mr.Kshitij Jain Mr.B.N.Rangaraja
n
Tel : 080-25328000
Fax: 080-25559764
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 45
RoadBangalore-560 001.
6. Life Insurance Corporation of
IndiaYogakshema, Jeeva Bima
Marg, Post Box No. 19953
MUMBAI 400 021
Mr. S.K. Roy P K ARORA Tel : 022- 66598000
7. Max Life Insurance Co. Ltd
11th
Floor, DLF
Square , Jacaranda
Marg, DLFCity , Phase-II,
GURGAON 122 002.
Shri Rajesh Sud Mr. Sanchit Maini Tel : 0124-2561717
Fax: 0124-2561764
8. PNB Metlife India Insurance
Co. Ltd.
Brigade Seshamahal, No.
5, Vani Vilas
Road , Basavanagudi, BANGA
LORE-560 004.
Mr Tarun Chugh
MD & CEO
P.K.Dinakar Tel : 080-26438638
Fax: 080-26521970
Toll Free No. 1800-425-6969
tchugh@pnbmetlife.com,
9. Kotak Mahindra Old Mutual
Life Insurance Limited
4th Floor, Vinay Bhavya
Complex,
159 A, CST Road,
Kalina, Santacruz (East),
Mumbai: 400098
Mr. G. Murlidhar Mr. Sunil Sharma Tel : 022-66057777
Fax:022-67425649/50
10. SBI Life Insurance Co. Ltd
Natraj, M.V.Road & Western
Express
Highway Junction, Andheri
(East), Mumbai-400069
Mr. Atanu Sen Mr. Sanjeev
Kumar Pujari
Tel : 022-61910011
Fax: 022-56621471
11. Tata AIA Life Insurance
Company Limited
14th Floor, TOWER – A,
Peninsula Business Park
Senapati Bapat Marg
Mumbai 400013
Mr. M. Suresh Mr. Heerak Basu Tel :022-66479000
Fax : 022-66550711
12 Reliance Life Insurance
Company Limited.
9th floor & 10th floor, Building
No. 2, R-Tech Park, Nirlon
Compound, Next to Hub Mall,
Behind I - Flex Building,
Goregaon (East), Mumbai - 400
063
Mr. Anup Rau
Velamuri
RAJESH
DALMIA
Tel : 022-30883434/ 30887261
Fax: 022-30886587
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 46
13 Aviva Life Insurance Company
India Limited
AvivaTower, Sector Road,
Opposit Golf Course,
DLF-Phase V, Sector-43,
Gurgaon - 122 003
Mr. T. R.
Ramachandran
Mr. Sanjeeb
Kumar
Tel: 0124-270 9000/01,
Fax: 0124-270 9007.
14 Sahara India Life Insurance Co,
Ltd.
#1, SaharaIndia Bhawan,
Kopoorthala Complex,
Lucknow 226024
Mr Sanjay
Agarwal,
MD & CEO
Mr. Pravir
Chandra
Tel: 0522-2329568
Fax: 0522-2332683
E-mail -
sanjay.agarwal@life.sahara.co.i
n
15 Shriram Life Insurance Co,
Ltd.
Ramky Selenium, Plot No 31 &
32
Beside Andhra Bank Training
Centre,
Financial District, Gachibowli,
Hyderabad – 500032
Mr Manoj Kumar
Jain
Mr. Nelius
Bezuidenhout
Board : +91 40 23009400
16 Bharti AXA Life Insurance
Company Ltd.
601-602 6th Floor,
Raheja Titanium
Off Western Express Highway
Goregaon (E)
Mumbai – 400 063
Mr. Sandeep
Ghosh
Mr. Rajeev Kumar Tel: 022 – 40306300/6301
Fax: 022 - 40306347
17 Future Generali India Life
Insurance Company Limited
6th Floor, Tower - 3, Indiabulls
Finance Centre, Senapati Bapat
Marg, Eliphinstone Road(W),
Mumbai - 400013.
Mr Munish
Sharda
MD & CEO
MAMATA
PANDEY
Tel No.:
022-40976802
Fax No.:
022-40976600
munish.sharda@futuregenerali.i
n
18 IDBI Federal Life
Insurance Company Ltd.,
Tradeview, 1st Floor,
Oasis Complex, Kamala City,
P.B. Marg,
Lower Panel (W),
Mumbai-400 013
Mr Vighnesh
Sahane
CEO
(Officiating)
MS. RUCHI
GOEL
Tel No.:
022- 66552836
Email:
vighnesh.shahane@idbifederal.c
om
19 Canara HSBC Oriental Bank of
Commerce Life Insurance
Mr. John David
Holden,
Mr. Chirag Shamji
Rathod
Tel: 0124 4535500
Fax: 0124 4535999
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 47
Company Ltd.
Augusta Point, 2nd Floor,
DLF Golf Course Road,
Sector-53, Gurgaon-Haryana
(INDIA) 122002
CEO & WTD
20 AEGON Religare Life
Insurance Company Limited.
Building No 3, Third floor, Unit
No.1
Nesco IT Park, Western Express
Highway,
Goregaon(E)
Mumbai - 400063
Mr K S
Gopalakrishnan
Patrick Curtin Tele No.-022 61180100
Fax No.- 022 67293333
Email: ks.gopalakrishnan@aego
nreligare.com
21 DHFL Pramerica Life Insurance
Co. Ltd.
4th Floor Tower B, Building
No.-9,
DLFCyberCity, Phase-III,
Gurgaon-122002.
Mr Anoop Kumar
Pabby
(MD & CEO)
Mr. Pradeep
Kumar Thapliyal
Ph. No.-
+91 124 4697000(Board)
Fax No.-
0124-4697100 / 200
anoop.pabby@dhflpramerica.co
m
22 Star Union Dai-ichi
Life Insurance Co. Ltd., Star
House, 3rd Floor, (West Wing),
C-5,Bandra-Kurla Complex,
Bandra (East),
Mumbai 400 051
Mr. Girish
Pandurang
Kulkarni
(MD & CEO)
Mr. I
SAMBASIVA
RAO
Phone: 022-39546211 e-mail:
ceo@sudlife.in
23 IndiaFirst Life Insurance
Company Limited
301, 'B' Wing, The Qube,
Infinity Park,
Dindoshi - Film City Road,
Malad (East), Mumbai - 400
097.
Dr. P.
Nandagopal
Mr. Chandan
Kumar Khasnobis
Phone: 022 39418700
Fax: 022 33259500
24
Edelweiss Tokio Life Insurance
Co. Ltd.
Edelweiss House,
off C.S.T. Road,
Kalina, Mumbai : 400 098
Mr. Deepak
Mittal Mr. Abhay Tewari
Tel No: 022 40636015
Fax No: 022 43428161
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 48
3.13 LIST OF SOME LIFE INSURANCE COMPANIES WORKS IN INDIA
3.13.1 Birla Sun Life Insurance Company:
Birla Sun Life Insurance Company Limited (BSLI) is a joint venture between the Aditya
Birla Group, a well known Indian conglomerate and Sun Life Financial Inc, one of the leading
international financial services organizations from Canada. With an experience of over a decade,
BSLI has contributed to the growth and development of the Indian life insurance industry and
currently is one of the leading life insurance companies in the country.
Foreign Partner:
Sun Life Financial is a leading international financial services organization providing a
diverse range of protection and wealth accumulation products and services to individuals and
corporate customers. Sun Life Financial and its partners have operations in key markets
worldwide, including Canada, the United States, the United Kingdom, Ireland, Hong Kong, the
Philippines, Japan, Indonesia, India, China, Australia, Singapore, Vietnam, Malaysia and
Bermuda. As of June 30, 2013, the Sun Life Financial group of companies had total assets under
management of $591 billion.
Sun Life Financial Inc. trades on the Toronto (TSX), New York (NYSE) and Philippine
(PSE) stock exchanges under the ticker symbol SLF.
3.13.2 HDFC- Standard Life:
HDFC Standard Life Insurance Company is a joint venture between India’s largest
housing finance provider, HDFC and Europe’s largest mutual life assurance company –The
Standard Life Assurance Company. HDFC Standard Life Insurance Company Limited is the
First Private Sector Life Insurance Company to be granted license.
HDFC Life continues to have one of the widest reaches among new insurance companies
with about 500 branches in India touching customers in over 900 cities and towns. The company
has also established a liaison office in Dubai. HDFC Life has a strong presence in its existing
markets with a strong base of Financial Consultants.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 49
Foreign Partner:
Established in 1825, Standard Life plc. is a leading provider of long term savings and
investments to around six million customers worldwide. Headquartered in Edinburgh, Standard
Life plc. has around 8,500 employees internationally.
The Standard Life plc. group includes savings and investments businesses, which operate
across the UK, Canada, Europe, Asia and Middle East; workplace pensions and benefits
businesses in the UK and Canada; Standard Life Investments, a global investment manager,
which manages over £179bn globally; and its Chinese and Indian Joint Venture businesses. At
the end of September 2013 the Group had total assets under administration of over £237bn. It is
one of the very few insurance companies in the world to have received ‘AAA’ rating from two of
the leading international credit rating agencies.
Standard Life plc is listed on the London Stock Exchange and has approximately 1.5
million individual shareholders in over 50 countries around the world. It is also listed in the Dow
Jones Sustainability World Index, ranking it among the top 10% of sustainable companies in the
world.
3.13.3 Life Insurance Corporation of India (LIC):
Life Insurance Corporation of India (LIC) is an Indian state-owned insurance group and
investment company headquartered in Mumbai. The Life Insurance Corporation of India was
established about 44 years ago with a view to provide an insurance cover against various risks in
life. A monolith then, the corporation, enjoyed a monopoly status and became synonymous with
life insurance. It is the largest insurance company in India with an estimated asset value of
1560481.84 crore (US$260 billion}). As of 2013 it had total life fund of Rs.1433103.14 crore
with total value of policies sold of 367.82 lakh that year. It’s main asset is its staff strength of
119,767 lakh employees (As on 31 March 2012) and 2,048 branches and over 6 lakh agency
force .LIC has hundred divisional offices and has established extensive training facilities at all
levels. At the apex, is the Management Development Institute, seven Zonal Training Centers and
35 sales Training Centers .At the industry level, along with the government and the GIC, has
helped establish the national insurance academy.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 50
It presently transacts individual life insurance businesses, group insurance businesses,
social security schemes and pensions, grants housing loans through its subsidiary; and markets
savings and investment products through its mutual fund .Its pays off about Rs 6,000 crore
annually to 5.6million policyholders.
3.13.4 Kotak Mahindra Life Insurance:
Kotak Mahindra Old Mutual Life Insurance Ltd is a 74:26 joint venture between Kotak
Mahindra Bank Ltd., its affiliates and Old Mutual plc. The company started operations in 2001,
and strives to offer its customers outstanding value through high customer empathy, consistent
and benchmarked service and a suite of products that leverage the combined prowess of
protection and long term savings. The company covers over 4 million lives and is one of the
fastest growing insurance companies in India.
Foreign Partner:
Old Mutual provides life assurance, asset management, banking and general insurance to
more than 14 million customers in Africa, the Americas, Asia and Europe. Originating in South
Africa in 1845, Old Mutual has been listed on the London and Johannesburg Stock Exchanges,
among others, since 1999. In the year ended 31 December 2012, the Group reported adjusted
operating profit before tax of £1.6 billion (on an IFRS basis) and had £262 billion of funds under
management from core operations.
3.13.4 Max Life insurance:
Max Life Insurance, one of the leading life insurers, is a joint venture between Max India
Ltd. and Mitsui Sumitomo Insurance Co. Ltd. Max India is a leading Indian multi-business
corporate, while Mitsui Sumitomo Insurance is a member of MS&AD Insurance Group, which is
amongst the top general insurers in the world. Max Life Insurance offers comprehensive life
insurance and retirement solutions for long-term savings and protection to thirty lakh customers.
It has a country-wide diversified distribution model including the country's leading agent
advisors, exclusive arrangement with Axis Bank and several other partners. Max Life Insurance
is a quality business focused on delivering excellence to customers through advice based sale
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 51
process, customer centric approach to business, financial stability & investment expertise and
strong human capital.
In the financial year 2012-13 Max Life Insurance ranked fourth among private life
insurers with a market share of 8.5%. The Company has been one of the fastest growing life
insurance companies with total revenue of Rs. 6,639 crore and enterprise profit before tax
of Rs. 860crore for the Financial Year 2012-13. The Company’s share capital of Rs. 2,127 crore
with a solvency margin of 521% is indicative of its financial strength and stability. As on 31st
March 2013, Max Life Insurance had assets under management of Rs. 20,458 crore.
Foreign Partner:
Mitsui Sumitomo Insurance Co., Ltd. (MSI) is a member of MS&AD Insurance Group
that was formed in April 2010 from the business integration of the Mitsui Sumitomo Insurance
Group Holdings, Inc. (MSIG), Aioi Insurance Co., Ltd. (Aioi) and Nissay Dowa General
Insurance Co., Ltd. (NDI) under the holding company MS&AD Insurance Group Holdings, Inc.
(MS&AD Holdings).
Headquartered in Tokyo, Japan, MS&AD Insurance Group has a presence in 39 markets
globally. In FY 2012-13, it reported a Total Assets of 15,914 billion yen (US$159 billion) and a
Consolidated Net Premium of 2,639 billion yen (US$ 26.4 billion).
3.13.5 Aviva Life Insurance India:
It is joint venture between Dabur, one of India ‘s oldest and largest groups of companies
and Aviva. Aviva plc is UK’s largest insurer .In accordance with government regulations, Aviva
holds a 26% stake in the new venture and Dabur holds a 74%share. In India, with a wide
distribution network of 134 branches spreading across nearly 1,000 towns and cities, we operate
in partnership with the Dabur Group.
Foreign Partner:
It is the world’s seventh –largest insurance group (based on gross worldwide premiums)
and the biggest in the UK . It is one of the leading providers of life and pensions products to
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 52
Europe and has substantial businesses elsewhere around the world .Its main activities are long
term savings, fund management and general insurance.
Aviva is UK’s largest and the world’s tenth largest insurance Group(based on asstes
hold). It is one of the leading providers of life and pensions products to Europe and has
substantial businesses elsewhere around the world. With a history dating back to 1696, Aviva has
a 30 million-customer base worldwide. It has more than £317 billion of assets under
management.
3.13.6 ING Vysya Life Insurance:
ING Vysya Life Insurance Company Limited is an established life insurance company
with over a decade of experience serving over 1 million customers in over 200 cities in India.
Headquartered in Bangalore, ING Vysya Life Insurance Company Limited is 100% owned by
Exide Industries Limited.
The company distributes its products through key channels like Tied Agency, Banc
assurance and Alliances. The Tied Agency channel comprises over 30,000 ING Vysya Life
Insurance Advisors, spread across the country. The Banc assurance and Alliances business
within ING Vysya Life Insurance is a fast growing distribution channel, and includes the Banc
assurance partner (ING Vysya Bank), Referral Partners, Corporate Agents and Brokers.
Foreign Partner:
Exide Industries Ltd - With eight manufacturing plants strategically located across the
country, Exide is India's largest producer of automotive and industrial batteries. Its range of
products covers everything from the smallest batteries required in motorcycles to the giant
batteries powering submarines.
It is the market leader in the organised sector in both the automotive and industrial
segments. 'EXIDE' and 'SF (Standard Furukawa)', the flagship brands of the Company, are also
the leading battery brands in the country.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 53
3.13.8 PNB Met Life Insurance :
PNB MetLife India Insurance Company Limited (PNB MetLife) is a joint venture
between MetLife International Holdings Inc. (MIHI), Punjab National Bank Limited (PNB),
Jammu & Kashmir Bank Limited (JKB), M. Pallonji and Company Private Limited and other
private investors, with MIHI and PNB being the majority shareholders. PNB MetLife was
previously known as MetLife India Insurance Company Limited (MetLife India) and has been
present in India since 2001.
PNB MetLife is present in over 150 locations across the country and serves customers in more
than 7,000 locations through its bank partnerships with PNB, JKB and Karnataka Bank Limited.
Met Life:
It ranked 38 on the fortune 500 list, Met Life, Inc is one of the worlds largest, strongest
and most respected financial organizations .Met Life, through its affiliates, is the number 1 life
insurer in the US with approximately $2.4 trillion of life insurance in force and has been
delivering reliable serve approximately 12 million individuals in the US as well as the employees
of 88 of the fortune 100 companies. Headquartered in New York, Met Life operates through its
affiliates and subsidiaries in 12 countries across the Americas, Europe and Asia.
3.13.9 Allianz Bajaj Life Insurance Company
Bajaj Allianz is a joint venture between Bajaj Finserv Limited and Allianz SE. Both enjoy a
reputation of expertise, stability and strength. This joint venture Company incorporates global
expertise with local experience. Bajaj Auto, one of the biggest 2 and 3 wheeler manufacturers in
the world. The comprehensive, innovative solutions combine the technical expertise and
experience of Allianz SE, and in-depth market knowledge and goodwill of "Bajaj" brand in
India. Competitive pricing and quick honest response have earned the Company the customer's
trust and market leadership in a very short time.
Foreign Partner:
I t is one of the world’s leading insurers and financial service providers. Founded in 1890
in Berlin, Allianz is now present in over 70 countries with almost 174,000 employees. At the top
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 54
of the international group is the holding company, Allianz AG, with its head office in Munich.
Allianz group provides its more than 60 million customers.
3.13.10 SBI Life Insurance Company Ltd
SBI Life Insurance Company Ltd is a joint venture between India’s largest banks, State
Bank Of India & Cardiff S A, a leading life insurance company in France. State Bank of India is
a household name, and it stands as the last word for financial strength and security in the
country. SBI’s illustrations background dates back to the year 1806 when it started business, as a
presidency bank, known as bank of Bengal Over the long journey, it has learnt to combine the
best of banking practices handed down from the imperial management with the more dynamic
ways of doing banking in the modern India. It has grown as a responsible giant in the banking
field over the years.
3.13.11 Tata AIA Life Insurance Company Limited
Tata AIA Life Insurance Company Limited (Tata AIA Life) is a joint venture company,
formed by Tata Sons and AIA Group Limited (AIA). Tata AIA Life combines Tata’s pre-
eminent leadership position in India and AIA’s presence as the largest, independent listed pan-
Asia life insurance group in the world spanning 17 markets in Asia Pacific. Tata Sons holds a
majority stake (74 per cent) in the company and AIA holds 26 per cent through an AIA Group
company. Tata AIA Life Insurance Company.
Foreign Partner:
AIA Group Limited and its subsidiaries (collectively "AIA" or "the Group") comprise the
largest independent publicly listed pan-Asian life insurance group. It has operations in 17
markets in Asia-Pacific – wholly-owned branches and subsidiaries in Hong Kong, Thailand,
Singapore, Malaysia, China, Korea, the Philippines, Australia, Indonesia, Taiwan, Vietnam, New
Zealand, Macau, Brunei, a 97 per cent subsidiary in Sri Lanka, a 26 per cent joint venture in
India and a representative office in Myanmar. It had total assets of US$147 billion as of 31 May
2013.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 55
3.14 THE MARKET SHARE OF LIFE INSURANCE COMPANIES
Apr 20
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 56
3.15 STATE BANK OF INDIA LIFE INSURANCE
SBI LIFE – a joint venture between
74% 26%
SBI Life Insurance is a joint venture between the State Bank of India and Cardiff SA of
France. SBI Life Insurance is registered with an authorized capital of Rs 2000 core and a paid up
capital of Rs 1000 carore. SBI owns 74% of the total capital and Cardiff the remaining 26% State
Bank of India enjoys the largest banking franchise in India. Along with its 7 Associate Banks,
SBI Group has the unrivalled strength of over 19,000 branches across the country, the largest in
the world. Cardif is a wholly owned subsidiary of BNP Paribas, which is The Euro Zone’s
leading Bank. BNP is one of the oldest foreign banks with a presence in India dating back to
1860. It has 9 branches in the metros and other major towns in the country. Cardif is a vibrant
insurance company specializing in personal lines such as long-term savings, protection products
and creditor insurance. Cardif has also been a pioneer in the art of selling insurance products
through commercial banks in France and 80 more countries.SBI Life Insurance’s mission is to
emerge as the leading company offering a comprehensive range of Life Insurance and pension
products at competitive prices, ensuring high standards of customer service and world class
operating efficiency. The company plans to make the insurance buying process quick, simple and
based on well-informed judgment. In 2004, SBI Life Insurance became the first company
amongst private insurance players to cover 30 lacks lives. The company expects to carve a niche
in the Indian insurance market through extensive product innovation and aims to provide the
highest standards of customer service through a technological interface. To facilitate this, call
centers have been already installed and help lines will be installed and customers will have
access to their accounts through the Internet or through SBI branches. The company proposes to
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 57
make available ready liquidity to its Life Insurance policies by way of loans at SBI counters.
This will make Life Insurance a liquid asset in the financial portfolio of households. SBI Life
Insurance is uniquely placed as a pioneer to usher bank assurance into India. The company hopes
to extensively utilize the SBI Group as a platform for cross-selling insurance products along with
its numerous banking product packages such as housing loans, personal loans and credit cards.
SBI’s access to over 100 million accounts provides a vibrant base to build insurance selling
across every region and economic strata in the country.
3.15.1 Group Corporate
SBI Life extensively leverages the SBI Group as a platform for cross-selling insurance
products along with its numerous banking product packages such as housing loans and personal
loans. SBI’s access to over 100 million accounts across the country provides a vibrant base for
insurance penetration across every region and economic strata in the country ensuring true
financial inclusion.
3.16 MANAGEMENT PHILOSOPHY
3.16.1 Mission
“To emerge as the leading company offering a comprehensive range of life insurance and
pension products at competitive prices, ensuring high standards of customer satisfaction and
world class operating efficiency, and become a model life insurance company in India in the post
liberalization period.”
3.16.2 Values
 Trustworthiness • Dynamism
 Excellence • Innovation
 Ambition
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 58
3.17 BOARD MEMBERS
The composition of the Board of Directors as on March 31, 2013 is as under:
TABLE 3.3
SR. No. Name of the Director Designation Category
1 Mr. Pratip Chaudhuri Chairman
Non–Executive Director / Non-Independent
Director
2 Mr. A. Krishna Kumar Director
Non–Executive Director / Non-Independent
Director
3 Mr. Atanu Sen MD & CEO
Executive Director / Non-Independent
Director
4 Mr. Eric Lombard Director
Non–Executive Director / Non-Independent
Director
5 Mr. Gerard Binet Director
Non–Executive Director / Non-Independent
Director
6 Mr. Nilesh Vikamsey Director
Non–Executive Director / Independent
Director
7 Mr. Ravi Rambabu Director
Non–Executive Director / Independent
Director
8 Mr. K. M. Bhattacharya Director
Non–Executive Director / Independent
Director
9
Mr. Raj Narain
Bhardwaj Director
Non–Executive Director / Independent
Director
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 59
3.18 KEY MILESTONES
Financial Year 11-12:
 Awarded the most coveted NDTV Profit Business Leadership Award, twice in a row, 2010 &
2011.
 Awarded ‘Most Trusted Life Insurance Brand - II By The Economic Times, Brand Equity
and Nielsen, Most Trusted Brands 2011.
 Globally topped the prestigious Million Dollar Round Table (MDRT) for having the
maximum number of MDRT members, for three years consecutively.
 CRISIL reaffirmed its AAA / Stable rating to SBI Life, indicating highest financial strength
to meet policyholder obligations.
 ICRA reaffirmed its iAAA rating indicating highest claims paying ability and a
fundamentally strong position.
 Won one of the most prestigious quality distinction, IMC Ramkrishna Bajaj National Quality
Awards 2011- "Certificate of Merit"
 Awarded Silver Shield by ICAI for Excellence in Financial Reporting for FY 2010 – 11
under the Insurance category.
 Won ’Best Presented Accounts Award‘ by The South Asian Federation of Accountants
(SAFA), in the Insurance Category for the Annual Report FY 2009-10.
Financial Year 10-11:
 SBI Life won the coveted Bloomberg UTV Financial Leadership Award 2011 - "Life
Insurer of the year".
 Won the most coveted NDTV Profit Business Leadership Award 2010.
 Globally topped the prestigious Million Dollar Round Table (MDRT) 2010 for having the
maximum number of MDRT members.
 Awarded the Gold Shield by Institute of Chartered Accountants of India (ICAI) for
Excellence in Financial Reporting.
 Won the ‘ICS Quality Champion Award 2010’ for Continual Quality Improvement.
 Adjudged Best Life Insurer 2010 - Runner Up by Outlook Money.
 Launched an innovative customer care initiative - SMS ‘SOLVE’ for prompt Grievance
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 60
Redressal.
 Appraised at Maturity level 3 of Capability Maturity Model Integration (CMMI) Version
1.2 for its ISG Division.
 ICRA reaffirmed ’iAAA’ rating to SBI Life, indicating highest claims paying ability and
meeting policyholders obligations.
 CRISIL, country’s leading rating agency, reaffirmed its highest financial rating
AAA/Stable to SBI Life.
Financial Year 09-10:
 Reported a robust Net Profit of Rs.276 Crores.
 Crossed Rs.10, 000 Crores in Gross Written Premium (GWP).
 Assets under Management (AUM) grew by 96% to Rs.28, 551 Crores.
 Globally topped the prestigious MDRT 2009 for having Maximum number of MDRT
Members.
 ICRA reaffirmed iAAA rating to SBI Life indicating highest claims paying ability.
 Awarded ISO Certification (ISO/IEC 27001:2005) for Information Security Management
System (ISMS).
 Retained ISO 9001:2000 certificate for superior claim settlement process.
Financial Year 08-09:
 Ranked among global top three in terms of number of Million Dollar Round Table
(MDRT) members
 Bagged the coveted personal finance award-Outlook Money NDTV Profit "Best Life
Insurer 2008".
 CRISIL, country’s leading rating agency, reaffirmed its highest financial rating
AAA/Stable to SBI Life. In 2007, SBI Life became the first life insurer in India to
receive this rating from CRISIL.
 ICRA assigned iAAA rating indicating highest claims paying ability to SBI Life
Insurance.
 Retained ISO 9001:2000 certificate for superior claim settlement process
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 61
Financial Year 07-08:
 Ranked amongst global top five life insurance companies in the number of MDRT
members.
 Rated as the ’The Most Trusted Private Life Insurer’ according to a survey conducted by
Brand Equity in association with AC Nielsen ORG-MARG and the Economic Times
Intelligence Bureau.
 Received the highest financial rating ’AAA’ from CRISIL.
 Forayed into micro insurance with the launch of ’Grameen Shakti’ in Bhubaneshwar,
Orissa for the economically underprivileged sections of society.
 Received ISO 9001: 2000 certification for superior claim settlement process.
 Received CMMI Level 3 certification for IT processes and software development
capabilities.
Financial Year 06-07:
 Second consecutive year of Profitability
 More than 6.40 Million lives covered
Financial Year 05-06:
 Reported a robust net profit of Rs. 2.02 Cr
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 62
3.19 FINANCIAL PERFORMANCE
SBI LIFE POSTS NET PROFIT OF Rs. 622 Crore, UP BY 12% Sustained impressive
All- round performance:
a) Individual NBP APE grows by 13.3%
b) AUM crosses Rs. 50,000 crore mark, increases by 11%
Mumbai, May 1, 2013: Reflecting on its sustained superior efficiency in business
operations, SBI Life Insurance posted a record profit of Rs. 622 Crores, during the financial year
ended on 31st March, 2013, an increase of 12% over the last financial year 2011-12.
Distinctively, the operational efficiency has been the key driver of SBI Life’s profitability. The
company ranks number one amongst private life insurers, in New Business Premium (NBP), for
the Financial Year 2012-13, as per the latest report from IRDA. Contrary to the continued
business decline faced by the life insurance industry, SBI Life’s regular new business premium
increased by 19 %, to Rs. 2,618 Cr during the FY 2012-13 from Rs. 2,193 Cr in FY 2011 -12.In
line with its focus on improving strategic business mix, the share of single premium from the
new business individual premium reduced to 16%, during the FY 2012-13 from 41% during the
FY 2011-12. Consequently, the individual new business premium APE grew by 13.3% to Rs.
2,388 Cr during FY 2012-13 from Rs. 2,108 Cr during FY 2011-12. The Asset Under
Management (AUM) jumped by 11 % to Rs. 51, 912 Cr from Rs. 46, 576 Cr as on 31st March,
2012.
Mr. Atanu Sen, MD & CEO, SBI Life Insurance said “Despite the continued tough
environment, we were able to change the business mix and sustain a profitable growth primarily
due to our brand strength, multi distribution model and high productivity of our retail channels.
We will further leverage our extensive Bancassurance network, Agency productivity and tap into
opportunities emanating from new technology usage.” Mr. Atanu Sen, MD & CEO, SBI Life
Insurance said “Despite the continued tough environment, we were able to change the business
mix and sustain a profitable growth primarily due to our brand strength, multi distribution model
and high productivity of our retail channels. We will further leverage our extensive
Bancassurance network, Agency productivity and tap into opportunities emanating from new
technology usage.” SBI Life maintains a low “Expense to GWP” ratio of 11%. The company has
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 63
garnered a market share of 17% amongst private players during the FY 2012 - 13 as per the latest
report from IRDA.23% of total policies of SBI Life are from rural segment which testifies the
company’s approach towards life insurance inclusion. Additionally, 68,714 lives covered by the
company are from the underprivileged social sector. Consequently, the company has
substantially exceeded the minimum social and rural regulatory norms. During the year, in line
with its customer - centric initiatives, the company undertook an extensive customer education
program reaching out to all socio-economic segments across the country. To cater to the
protection needs of younger audience whose internet usage is increasing, the company forayed
into online distribution by launching an online pure protection plan, e-Shield. Conveniently in
three steps, the policyholder can buy life insurance cover of Rs.1 Crore for annual premium of
Rs.6, 360 per year, subject to age, health profile, policy term and plan option chosen. During the
year, the company introduced several new products designed on variety of need-based platforms.
These include guaranteed income plan – Smart Income Protect, Pure Protection Plan - Smart
Income Shield, and Pension Plan - Saral Pension. SBI Life won the prestigious Indian Merchant
Chambers’ Ramkrishna Bajaj National Quality Award, 2012 in “Service Sector”. Further, SBI
Life was rated as the “Most Trusted” Private Life Insurer, 2012 by ET - Brand Equity Nielsen
Survey for second year in a row. Bagging the ISO 10002:2004 certification for efficient
Customer Complaint Management System and reaffirmation of CRISIL’s AAA and ICRA’s
"iAAA" indicating highest claim paying ability are other key distinctions achieved by the
company during FY 2012-13. Among many CSR initiatives undertaken during the financial year,
the company extended support towards education of physically disadvantaged children and
underprivileged girl children in remote parts of the country, through its CSR partners
Swayamsiddh and Project Nanhi Kali respectively.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 64
3.20 SWOT ANALYSIS
SWOT Analysis
Strength
1. Leverages SBI’s largest customer base for cross selling its
product
2. Multi layer Distribution channel
3. SBI life has over 7,000 on-roll employees and 75,000 agents
4. Strong Presence across India
5. SBI Life Insurance has an authorized capital of Rs2,000 crore
(US$405.6 million)and a paid up capital of Rs1,000 crore
(US$202.8 million
6. State Bank Group has the unrivalled strength of over 18,000
branches across the country
Weakness
1. Managing a huge number of people is a concern
2. Cases of fraud have tarnished image
Opportunity
1. Growing rural market potential
2. Group Insurance through large employers
3. People willing to invest more to secure their future
Threats
1. Economic crisis
2. Entry of new NBFCs in the sector
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 65
3.21 SBI LOCATION OF OFFICES
SBI has a huge network of offices for providing service related to Insurance all overthe
country.
Location:
Registered office:
SBI Life Insurance Co. Ltd. Central Processing Centre Kapas Bhawan, Sector 10, CBD Belapur,
Navi Mumbai 400614.Telephone No: 022-6645 6241
Email: info@sbilife.co.in
Corporate Office:
SBI Life Insurance Co. Ltd, "Natraj", M.V. Road & Western Express Highway Junction,
Andheri (East), Mumbai - 400 069
Summer training office location:
Branch office:
Sbi Life Insurance Co. Ltd. 3rd Floor, Alaknanda Tower, City Center. 474001. Gwalior (M.P)
Tel.0 751- 4024 497
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 66
3.22 PRODUCTS OFFERED BY STATE BANK OF INDIA LIFE
INSURANCE
State Bank Life Insurance offers a bouquet of insurance solutions to meet every need. It offers to
both, individuals as well as to companies looking to provide benefits to their employees. This
section gives details of all products with their features and benefits.
3.23 INDIVIDUAL PLANS
3.23.1 UNIT LINKED PLANS
1. SBI Life - Smart Wealth Builder
2. SBI Life - Smart Wealth Assure
3. SBI Life - Saral Maha Anand
4. SBI Life - Smart Scholar
5. SBI Life - Smart Elite
6. SBI Life - Smart Power Insurance
Unit Linked Insurance Plans are long term investment cum protection plans that offer an
opportunity of availing market linked returns while providing life insurance protection.
Depending on our risk appetite, we have the option of choosing from host of funds having varied
degree of risk exposure. Flexibility and transparency are some of the other attractive features that
make ULIPs an attractive long term investment option.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 67
3.23.1.1 SBI LIFE - SMART WEALTH BUILDER
(UIN: 111L095V01) (Product Code: 1K)
SBI Life definitely understands consumer’s financial & insurance needs. SBI Life - Smart
Wealth Builder, a unit linked, non participating, insurance plan is an attempt to meet all financial
& insurance needs through a single product. This can be using it the way we like. We can choose
our required life insurance cover subject to a minimum and a maximum level
Key features:
• Guaranteed Additions (Conditions Apply) up to 125% of one annual regular premium on a
regular premium policy, for a 30 year policy term, subject to the Policy being in force till the
maturity date.
• Guaranteed Additions starting as early as 10th policy year onwards.
• No Policy Administration fees for first 5 years for Regular and Limited Premium Paying
Term (LPPT) plans, thereby boosting our fund value
• No Premium Allocation Charge from 11th year onwards
• Enhanced investment opportunity through 7 varied Fund Options
• Life Insurance coverage, with minimum Sum Assured based on age
• Flexible product with an option to increase/decrease our Sum Assured from 6th policy year
onwards
Benefits:
1. Maturity Benefit: (Applicable only for in-force policies): On completion of Policy
Term, Fund Value will be paid.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 68
2. Death Benefit: (Applicable only for in-force policies): Higher of the Fund Value or Sum
Assured is payable; with a minimum of 105% of total basic premiums paid till the date of
intimation of death.
3. Tax Benefits:
• Tax deduction under Section 80 C is available. However in case the premium paid
during the financial year, exceeds 10% of the sum assured, the benefit will be limited up
to 10% of the sum assured.
• Tax exemption under Section 10(10D) is available at the time of maturity/surrender,
subject to the premium not exceeding 10% of the sum assured in any of the years during
the term of the policy. However, death proceeds are completely exempt.
3.23.1.2 SBI Life - Smart wealth assure
(UIN: 111L077V02) (Product Code: 55)
SBI Life - Smart Wealth Assure is a Unit Linked non-participating Life Insurance Plan. It is a
single premium plan, premium to be pay at once and continue to enjoy the benefits throughout
the policy term. The plan helps us to enjoy market related returns along with insurance cover,
with just a single premium
Key features:
• Option to choose a mix of funds providing Market Linked Returns
• Market Linked Returns provided through 2 funds – Bond Fund & Equity Fund to give the
best possible returns
• Pay only once and get the benefits throughout the Policy Term
• Liquidity through Partial Withdrawal(s)
• Option to customize the product with Accidental Death Benefit Option
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 69
Benefits:
• Maturity Benefit: On completion of Policy Term, Fund Value will be paid.
• Death Benefit: Higher of the Fund Value or Sum Assured## is payable; with a minimum
of 105% of Single premium paid.
• Accidental Death Benefit Option: Provides additional death benefit if the death occurs as
a result of an accident.
• Tax Benefits:
Tax deduction under Section 80 C is available. However in case the premium paid during the
financial year, exceeds 10% of the sum assured, the benefit will be limited up to 10% of the sum
assured.
3.23.1.3 SBI Life - Saral maha anand
(UIN: 111L070V02) Product Code: 50)
SBI Life - Saral Maha Anand is a unit linked, non participating life insurance plan, which lets us
to manage our investments according to our risk appetite, giving us the power to realise market
related returns on our policy. We can choose our required life insurance cover subject to a
minimum and a maximum level.
Key Features:
• No medical examination, Simple joining process
• Guaranteed Additions of up to 30% of one annual premium, for a 20 year policy term,
subject to the Policy being in force till the maturity date.
• 3 fund options, to enjoy market related returns as per our risk appetite.
• Option to customize the plan through SBI Life - Accidental Death Benefit Linked Rider
(UIN: 111A019V02)
• Twin Benefit of Market linked returns & insurance cover
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 70
Benefits:
• Maturity Benefit: On completion of Policy Term, Fund Value will be paid.
• Death Benefit: Higher of the Fund Value or Sum Assured is payable; with a minimum of
105% of total basic premiums paid till the time of death.
• Rider Benefits:
SBI Life - Accidental Death Benefit Linked Rider: Provides additional death benefit, if the death
occurs as a result of an accident.
• Tax Benefits
Tax deduction under Section 80 C is available. However in case the premium paid during the
financial year, exceeds 10% of the sum assured, the benefit will be limited up to 10% of the sum
assured.
3.23.1.4 SBI Life - Smart scholar
(UIN: 111L073V02) (Product Code: 51)
Life begins afresh when we become a parent. It’s a joy we never felt and a feeling we never
experienced. When our child takes baby steps towards us, nothing seems more blissful. With this
divine happiness comes a new sense of responsibility that’s close to our heart. We want to make
our child’s life a bed of roses or a tender cushion.
Features:
• Secure child’s future by gaining from the financial markets and much more.
• Payment of base Sum Assured and
• Inbuilt Premium Pay or Waiver benefit to ensure continuance of policy
• In addition, Accident Benefit which includes Accidental Death benefit and Accidental Total
and Permanent Disability (Accidental TPD) benefit, is an integral part of the plan
• Depending upon the term of the policy, Loyalty Additions would be paid periodically, for in-
force policies.
• Enhanced investment opportunity through 7 varied fund options
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 71
• Twin benefits of market linked return & insurance benefit
• Liquidity through partial withdrawal(s)
Benefits:
• Maturity Benefit: On completion of Policy Term, Fund Value will be paid
• Death Benefit:
• In the event of unfortunate death of life assured, a lump sum benefit equal to
higher of the Sum Assured or 105% of all premiums paid till date of death will be payable.
• The company continues to pay our future premium(s) on our behalf (inbuilt
Premium Payer Waiver Benefit) and the accumulated fund value will be paid at maturity
• In case of our unfortunate accidental death or accidental total and permanent
disability we pay:
✓ Additional benefit equal to Accident benefit Sum Assured
• The Accident Benefit and Premium Payer Waiver Benefit are not available in the
Single Premium policies.
• Tax Benefits
• Tax deduction under Section 80C is available.
• Tax exemption under Section 10(10D) is available at the time of maturity/surrender.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 72
3.23.1.5 SBI Life - Smart elite
(UIN: 111L072V02) (Product Code: 53)
SBI Life - Smart Elite is a Unit Linked Insurance plan - an exquisitely crafted product. It gives
flexibility to pay premium(s) for limited term or single premium, with the freedom to stay
invested and protected for long term.
Key Features:
• Pay premiums only for a limited term of 5, 8 or 10 years or a Single Payment, as per our need
and enjoy benefits throughout the chosen policy term.
• No Premium Allocation Charges from 6th policy year onwards, thereby enhancing fund
value
• Two protection options available: Gold Option & Platinum Option
• Invest in wide range of funds and manage them as per our convenience.
• Life Insurance coverage with minimum Sum Assured of 10 or 7 times of our Annual
Premium (AP), based on our age.
• Option to increase/decrease our Sum Assured from 6th policy year onwards.
• Accidental Death and Accidental Total and Permanent Disability (Accidental TPD) benefit
automatically comes as an integral part of the plan.
Benefits:
• Maturity Benefit: On completion of Policy Term, Fund Value will be paid.
• Death Benefit:
• For Gold Option: Higher of Fund Value or Sum Assured is payable; with a
minimum of 105% of total premiums paid till the time of death.
• For Platinum Option: Fund Value plus Sum Assured is payable; with a minimum
of 105% of total premiums paid till the time of death.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 73
• In-built Benefit:
Accidental Death and Accidental Total and Permanent Disability (Accident Benefit):
Provides an additional benefit for Accidental Death or Accidental TPD
Tax Benefits:
• Tax deduction under Section 80 C is available.
• Tax exemption under Section 10(10D) is available at the time of maturity/surrender.
3.23.1.6 SBI Life - Smart power insurance
(UIN: 111L090V01) (Product Code: 1C)
SBI Life - Smart Power Insurance, a non-participating unit linked insurance plan which takes
care of our insurance as well as investment needs. The product comes at reasonable premium and
is in tune with the current investment scenario. It is a flexible product, which also takes care of
our liquidity needs. Additional protection requirement, due to changing personal and/or financial
circumstances, is also taken care by the product.
Key Features:
• Two Plan Options to choose from:
Level Cover Option - Sum Assured chosen at inception remains the same throughout the
policy term
Increasing Cover Option - The initial Sum Assured increases by 10%, without any additional
underwriting, starting from 6th policy year and after every 5 years thereafter
• Advantage of Advancing the Policy Benefit to become Living Benefit, through Inbuilt
Accelerated Total & Permanent Disability (TPD) benefit.
• Two Fund options to choose from
• Trigger Fund Option - Advantage of ’Buying Low and Selling High.
• Smart Funds Option - Option to choose from 7 varied funds
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 74
• Flexibility through 2 free switches in a policy year.
Benefits:
•Maturity Benefit: On completion of Policy Term, Fund Value will be paid.
•Death Benefit: Higher of the Fund Value or Sum Assured# is payable; with a minimum of
105% of total basic premiums paid till the time of death
In-built Accelerated Total and Permanent Disability (TPD) Benefit: In case of TPD due to
Accident or Sickness, 100% of the Death Benefit (as defined above) will be paid immediately
and thereafter the policy would terminate.
Tax Benefits
•Tax deduction under Section 80 C is available.
•Tax exemption under Section 10(10D).
3.24 CHILD PLANS
As a caring parent always they are always want to do their very best to their children’s. To
ensure that fulfill of dreams financial planning for their secured future is very important.
At SBI Life, provide best plan for the children one that suits and child’s needs best.
Plans available in this
1. SBI Life - Smart Scholar
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 75
3.25 PENSION PLANS
Increasing life expectancy rate, rising health care costs, absence of social security system in India
and disintegration of joint family system are some of the key reasons that makes retirement
planning very critical. To help continue celebrating life post-retirement to the fullest, SBI Life
presents an array of pension plans which are simple and innovative.
1. SBI Life - Saral Pension
2. SBI Life - Retire Smart
3. SBI Life - Annuity Plus
3.25.1 SBI Life - Saral pension
(UIN: 111N088V02) (Product Code: 1E)
Retirement - means giving up work and continuing to Celebrate Life!
SBI Life - Saral Pension is an Individual, Participating, Non Linked, Traditional Pension Plan,
which offers complete safety from market volatility, by providing a secure future and a joyous
retirement.
• Guaranteed Bonus: Guaranteed simple reversionary Bonuses for first 5 years; @ 2.50%
for first three years and @2.75% for the next two years, of the Sum Assured. Guaranteed bonus
will be applicable only to in-force policies.
• Vesting (Maturity) benefit: Sum Assured plus vested simple reversionary bonuses plus
terminal bonus, if any. The sum assured carries an implicit guaranteed interest rate of at least
0.25% p.a. compounding annually on the total premiums.
• Death Benefit: Higher of total premiums paid accumulated at an interest rate of 0.25%
p.a. compounded annually plus vested reversionary bonus plus terminal bonuses, if any or 105%
of total premiums paid.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 76
• Life Cover: Option of additional life cover through SBI Life - Preferred Term Rider
(UIN: 111B014V02).
• Flexibility: we can defer the vesting date up to age of 70 years or extend the
accumulation / deferment* period of our policy.
Benefit:
 Death Benefit:
In an event of death of the policyholder, the death benefit proceed will be higher of total
premiums paid accumulated at an interest rate of 0.25% p.a. compounded annually plus vested
reversionary bonus plus terminal bonuses, if any, or 105% of total premiums will be paid to the
nominee.
 Tax Benefits:
•Premium paid under this policy is eligible for tax deduction u/s 80CCC of the Income Tax Act.
•Tax exemption under Section 10(10D)
•Tax exemption under Section 10(10A)
3.25.2 SBI Life - Retire smart
(UIN: 111L094V01
Due to higher disposable incomes and breakthrough in medical sciences, longevity has increased
to a great extent. We are all living longer after retirement.
Retirement may sound distant at the moment. However, it could span as long as one-fourth of
our lifetime and is ever increasing; and not many of us have really noticed or even thought about
that. Moreover, many people underestimate how much they need to save for retirement. Thus, for
creating a retirement corpus, systematic & disciplined investment is required during one’s
earning years.
SBI Life - Retire Smart, a non-participating unit linked pure pension plan, which guarantees us
minimum of 101% of all premiums paid, when policy is in force, on Maturity/Vesting; thus the
downside risk in the market is protected to a great extent.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 77
Features:
• Our Fund Value is boosted, through guaranteed additions of up-to 210%* of Annual
Premium (Conditions Apply)
• Guaranteed Additions of 10% of Annual Premium are paid regularly, starting from the end of
15th policy year and at the end of every year thereafter till the end of policy term.
• Get Terminal Additions of 1.5% of Fund Value, at maturity/vesting or on earlier death.
• No need to worry about investments, as the same is managed on our behalf by SBI Life
through ‘Advantage Plan’. This plan guarantees a minimum of 101% of all premiums paid at
maturity/vesting.
• Get a Guarantee of minimum 105% of all premiums paid on earlier death.
• Option to pay premiums regularly or for a limited period.
• Flexibility to postpone vesting age.
Benefits:
• Maturity/Vesting Benefit: On completion of policy term, we will receive the Higher of (Fund
Value plus Terminal Addition or 101% total premiums paid).
The following are options on Maturity / Vesting:
• To purchase immediate annuity, from the entire policy proceeds
• To purchase a single premium deferred pension product, from the entire policy
proceeds
• To purchase immediate annuity with an option to commute up-to one-third of the
policy proceeds, as per current Income Tax rules
To extend the accumulation period or defer the vesting date provided below age of 55
years at vesting. The maximum extended period will be up to age 80 years.
• Death Benefit:
In the unfortunate event of death of the Life Assured, Higher of (Fund Value plus Terminal
Addition or 105% of total premiums paid till the time of death), is payable.
• Tax Benefits:
• Premiums paid under the Policy are eligible for tax deduction u/s 80CCC of the Income
Tax Act, 1961.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 78
• On vesting or on surrender/discontinuance, the policyholder can currently commute up to
one third of the policy proceeds as per the Income Act Tax, 1961. This commuted value
is exempted from tax under section 10(10A) (iii) of the Income Tax Act 1961.
• Death benefit under this policy is tax exempt u/s 10 (10D) of the Income Tax Act, 1961.
3.25.3 SBI Life - Annuity plus
(UIN: 111N083V01)
SBI Life - Annuity Plus, a traditional, non-participating immediate annuity plan, which offers a
comprehensive range of annuity options along with inbuilt flexibilities. It provides an
opportunity to us to maintain our standard of living.
Key Features:
• Complete freedom to choose from a wide range of Annuity options
• Enjoy a regular income (“annuity payout”) from an early age of 40 years
• we have an option to have Lifetime Annuity payout for policy holder as well as a family
member
• Flexibility to choose frequency of annuity payouts as per our requirements - Monthly,
Quarterly, Half-yearly or Yearly
• Incentives of higher annuity rates for large premiums
• Flexibility to advance Annuity payouts
• Return of premium or balance premium
• SBI Life - Accidental Death Benefit Rider (UIN:111B015V02)
Wide Variety of Annuity Options available:
• Life Annuity (Single Life): Annuity payout at guaranteed rate, through-out the life of the
annuitant. We may choose from following options:
• Lifetime Income
• Lifetime Income with Capital1 Refund
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 79
• Lifetime Income with Capital1 refund in parts
• Lifetime income with Balance Capital2 Refund: Annuity is payable at a constant rate
throughout the life. On death, the Balance capital (in case positive) will be paid.
• Lifetime income with Annual Increase of 3% or 5%: Annuity payout increases at a
simple rate of 3% or 5% p.a. for each complete year and is payable throughout the life of the
annuitant. All future annuity payouts cease immediately on death and the contract terminates
• Lifetime income with certain period of 5, 10, 15 or 20 years and life thereafter:
• Annuity is payable at a constant rate for a minimum fixed period of 5, 10, 15 or
20 years; and for life thereafter.
• Life Annuity (Two lives): The annuity payout will continue at a guaranteed rate,
throughout the life of the annuitants. We may choose from below options:
• Life and Last Survivor - 50% or 100% Income without Capital Refund
• Life and Last Survivor - 50% or 100% Income with Capital Refund
Benefits:
• Annuity payable as per the annuity option chosen.
• SBI Life- Accidental Death Benefit Rider (UIN:111B015V02)
• Age at Entry (as on last birthday): Min - 40 years, Max - 60 years
• Rider Term (fixed): 10 years
• Maximum Age at maturity: 70 years
• Minimum Sum Assured: Rs. 25,000/-
• Maximum Sum Assured: Rs. 50, 00,000/-
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 80
3.26 PROTECTION PLANS
Protection Plans are low cost insurance plans which are specially designed to provide full
protection & financial stability in case of any unforeseen events.
SBI Life presents range of attractive protection plans so that can continue to celebrate life
without worrying about the uncertainties of life. .
1. SBI Life - Smart Shield
2. SBI Life - Saral Shield
3. SBI Life - eShield
4. SBI Life - Grameen Bima
3.26.1 SBI Life - Smart shield
(UIN: 111N067V02) (Product Code: 45)
SBI Life - Smart Shield is a traditional non-participating pure term plan, which is a one stop
solution that meets all our insurance needs. With Options and benefits specially tailored for those
who want best financial protection at an affordable cost, this is the perfect plan from our
preferred insurance provider. Now our family stays protected, even when we are not around.
Key Features:
• Establishes a solid foundation for a lifetime of financial security for our family.
• Rewards us for maintaining a healthy lifestyle.
• Wide variety of plan options to give us freedom from our liabilities.
• Large Sum Assured rebates.
• We can also customize our coverage by choosing from a wide range of additional benefits
such as SBI Life - Accidental Death Benefit Rider, SBI Life - Accidental Total and
Permanent Disability Benefit Rider and Accelerated Critical Illness cover option.
• Tax benefits* as per prevailing norms under the Income Tax Act, 1961.
• Benefits:
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 81
•Death Benefit: In case of the unfortunate demise of the life assured during the term of the
policy, the nominee will receive the benefits, depending on the plan option chosen
•Maturity Benefit: No survival benefit available at the end of the term.
•Other Benefits:
Cover Option
•Accelerated Critical Illness benefit: You have the option to further enhance Level Term
Assurance and Increasing Term Assurance by opting for the Accelerated Critical Illness benefit.
This option is available with Level Term Assurance and Increasing Term Assurance benefit.
Riders:
•SBI Life - Accidental Death Benefit Rider (UIN: 111B015V02)
In case of death due to an accident, the Rider Sum Assured is payable in addition to normal death
benefit.
•SBI Life - Accidental Total and Permanent Disability Benefit Rider (UIN: 111B016V02)
The Rider Sum Assured will be paid on the Life Assured being found eligible for the Total
Permanent Disability Benefit as defined in the policy document.
Tax Benefits
• Tax deduction under Section 80 C is available.
• Tax deduction under Section 80D is available for premiums paid for Accelerated Critical
Illness cover
• Tax exemption under Section 10(10D) is available at the time of maturity/surrender.
• Tax benefits, are as per the provisions of the Income Tax laws & are subject to change
from time to time.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 82
3.26.2 SBI Life - Saral shield
(UIN: 111N066V02) (Product Code: 47)
SBI Life - Saral Shield is a traditional non-participating pure term Insurance plan. At an
affordable cost, SBI Life Saral Shield provides cover for our family and ensures that a proper
safety net is created. Thus, it guarantees that there will be no compromise on our dreams and
ambitions for our loved ones.
Key Features:
• Hassle-free, convenient and easy issuance.
• Financial Security.
• Freedom from liability by choice on one of the following plan options:
• Level Term Assurance;
• Decreasing Term Assurance (Loan Protection);
• Decreasing Term Assurance (Family Income Protection)
• Special premium discounts for women
• Large sum assured rebates.
• Enhance protection by availing two riders-SBI Life- Accidental Death Benefit Rider and SBI
Life- Accidental Total and Permanent Disability Rider.
• Tax benefits as per prevailing norms under the Income Tax Act, 1961
Benefits:
• Death Benefit: In case of the unfortunate demise of the life assured during the term of the
policy, the nominee will receive the benefits, depending on the plan option chosen.
• Maturity Benefit: No survival benefit available at the end of the term.
Riders:
• SBI Life - Accidental Death Benefit Rider (UIN: 111B015V02)
In case of death due to an accident, the Rider Sum Assured is payable in addition to normal death
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 83
benefit.
• SBI Life - Accidental Total and Permanent Disability Benefit Rider (UIN:
111B016V02) The Rider Sum Assured will be paid on the Life Assured being found eligible for
the Total Permanent Disability Benefit as defined in the policy document.
Tax Benefits
• Tax deduction under Section 80 C is available.
• Tax exemption under Section 10(10D) is available at the time of maturity/surrender.
3.26.3 SBI Life - Eshield
(UIN: 111N089V01)
SBI Life - eShield is an Individual, Non Linked, Non Participating pure term plan, with options
and benefits specially tailored for those who want the best financial protection at an affordable
cost.
Key Features:
• Security for our family at an affordable premium.
• Easy and seamless online process for securing life cover.
• Rewards us for maintaining a healthy lifestyle.
• Wide variety of plan options, which has level and increasing cover.
• Additional benefit of Accidental Death Benefit.
• Tax benefits u/s 80C and 10(10D) of Income Tax Law, 1961.
Effective Sum Assured:
• Level Cover and Level Cover with Accidental Death Benefit: Effective Sum Assured on
any day is equal to the Basic Sum Assured.
• Increasing Cover and Increasing Cover with Accidental Death Benefit : Effective Sum
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 84
Assured on any day will be the Basic sum assured increased at the rate of 10% simple interest
after every 5th policy year without increasing the premium.
Benefits:
On Death:
• Depending upon the Plan option chosen, the nominee will receive the Effective sum assured at
the time of death.
• Death benefit will be paid provided all regular premiums are paid and the policy is in force as
on the date of claim.
On Maturity: No survival benefit available at the end of the term.
Other Benefits:
• Accidental Death Benefit: Inbuilt under plan options - Level Cover with Accidental Death
Benefit and Increasing Cover with Accidental Death Benefit.
• In case one of the above plan options is chosen, then in case of death of the life assured due
to accident during the policy term, Accidental Death Benefit will be paid to the beneficiary in
addition to the effective sum assured at the time of death.
• The Accidental Death Benefit will be equal to the Basic sum assured or Rs. 50 Lakhs
whichever is lower.
Tax Benefits:
• Tax deduction under Section 80(C) is available.
• Tax exemption under Section 10(10D) is available, subject to the premium not exceeding
10% of the sum assured in any of the years during the term of the policy.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 85
3.26.4 SBI Life - Grameen bima
(UIN: 111N087V01)
The objective of this product is to provide life cover to the deprived sections of the society at
affordable costs thereby aiding them tide over difficult times in case of an unforeseen event.
SBI Life - Grameen Bima is an individual, pure term, micro-insurance plan for the socially
deprived and economically vulnerable segments of the population.
Key Highlights:
• We can choose our premium; correspondingly our life insurance cover will be determined.
• Prompt Processing & Enrolment
• No medical examination, acceptance would be based on satisfactory health declarations in
the proposal form
• Registration based on a simple form
Benefits:
• Death Benefit: In the unfortunate event of death of the life assured during the policy
term, the nominee will receive the Sum Assured.
• Maturity Benefit: There is no maturity benefit under this plan.
• Surrender Benefit
• Surrender is allowed from 2nd year onwards.
• No surrender benefit is payable in the last year of the policy.
• Tax Benefits
Alongside other features, this product also offers the following tax benefits:
• U/s 80C of the Income Tax Act 1961 base premium.
• U/s 10 (10D) of the Income Tax Act 1961 on the death proceeds
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 86
3.27 SAVINGS PLANS
SBI Life’s plans will help investors to plan for savings, child’s wedding or education, buying a
house or that dream vacation.
1. SBI Life - Smart Money Back Gold
2. SBI Life - Shubh Nivesh
3. SBI Life - Saral Swadhan+
4. SBI Life - Flexi Smart Plus
3.27.1 SBI Life - Smart money back gold
(UIN: 111N096V01) (Product Code: 1N)
SBI Life - Smart Money Back Gold is a savings plan with added advantage of life cover and cash
inflow at regular intervals. It is a participating traditional money back insurance plan, meeting
various financial obligations at crucial junctures by its wide range of policy terms. Regular
payments of Survival benefits are made at different durations during the policy term. In the
unfortunate event of death at any time within the Policy Term, nominee would receive the full
Sum Assured plus Simple Reversionary Bonus & Terminal Bonus (if any), irrespective of
Survival Benefits already paid.
Key Features:
• Money Back options specially tailored to suit our requirements
• Fixed cash inflows which can meet various financial obligations
• Survival Benefit of 110% of Sum Assured paid till maturity
• Rebate on Large Sum Assured
• Customize our coverage through the wide range of additional benefits - SBI Life -Accidental
Death Benefit Rider (UIN: 111B015V02), SBI Life - Accidental Total & Permanent
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 87
Disability Benefit Rider (UIN: 111B016V02), SBI Life - Preferred Term Rider (UIN:
111B014V02) and SBI Life - Criti Care 13 Non-Linked Rider (UIN: 111B025V02)
Benefits:
• On survival:
▪ Before maturity: The survival benefit installments expressed as a fixed percentage
of basic sum assured payable at the end of specified durations during the policy term, as
explained above.
▪ At maturity: Final survival benefit installment + Vested simple reversionary
bonus + Terminal bonus, if any.
• On Death:
In the unfortunate event of death during the term of the plan, provided the policy is in-
force:
▪ Higher of A or B is paid to the nominee, where:
A = Sum Assured on death + Vested Simple Reversionary Bonuses + Terminal bonus, if any.
Sum Assured on death is higher of Basic Sum Assured or a multiple of annualised premium;
where multiple is
Policy Term Age at entry of Life Assured
less than 45 years
Age at entry of Life Assured
45 years or more
12, 15, 20 or 25 10 7
B = Minimum death benefit which is equal to 105% of all the premiums paid.
Tax Benefits:
• Tax deduction under Section 80 C is available.
• Tax deduction under Section 80(D) is available for premiums paid towards SBI Life -
Criti Care 13 Non Linked Rider.
• Tax exemption under Section 10(10D) is available at the time of maturity/surrender
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 88
3.27.2 SBI Life - Shubh nivesh
(UIN: 111N055V02) (Product Code: 35)
SBI Life - Shubh Nivesh is a non- linked, with profit Endowment Assurance product with an
option of Whole Life coverage. The basic purpose is to provide Savings, Income and Insurance
Cover. This policy not only save regularly for future needs but also have the flexibility to
receive the maturity amount as a lump sum or as a regular income for a chosen period, depending
upon needs.
Key Features:
• A savings plan with flexibility of availing whole life insurance as an add-on benefit
• Benefits including Wealth Creation, Insurance cover and Regular flow of income
• Flexibility to choose between Single or Regular premium payment
• Additional rider benefits at an affordable cost
• Option to receive the Basic Sum Assured at regular intervals over a stipulated time period of
5/10/15/20 years
• Comprehensive risk coverage through 3 Riders:
• SBI Life - Preferred Term Rider (UIN:111B014V02)
• SBI Life - Accidental Death Benefit Rider (UIN: 111B015V02)
• SBI Life - Accidental Total & Permanent Disability Benefit Rider (UIN: 111B016V02)
Benefit:
On maturity: Depending upon the plan option chosen
1. Endowment Option
▪ After completion of endowment term, the Basic Sum Assured + Vested Simple
Reversionary Bonuses + Terminal bonus, if any will be paid, provided the policy is in-force.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 89
2. Endowment with Whole Life Option
After completion of endowment term the Basic Sum Assured + Vested Simple Reversionary
Bonuses + Terminal bonus, if any will be paid, provided the policy is in-force.
Death Benefit: In the unfortunate death of the Life Assured, depending upon the plan option
chosen:
1. Endowment Option
Death before the completion of endowment term provided the policy is in-force :
For Regular Premium: Higher of A or B is paid to the nominee, where:
A. sum assured on death – vested simple reversionary bonus+terminal bonus
B. 105% of all the premiums paid.
2. Endowment with Whole Life Option
Death after completion of the endowment term and up to 100 years of age:
• Basic Sum Assured benefit will be paid to the nominee.
• Balance amount of Deferred Maturity Payment Option, if availed and if any, will be paid
to the nominee. However, the nominee has an option to take the remaining installments in lump
sum which will be equal to the discounted value of the remaining installments.
Three sets of riders
SBI Life - Preferred Term Rider (UIN:111B014V02): The Preferred Term rider Sum Assured
is payable in addition to normal death benefit.
SBI Life - Accidental Death Benefit Rider (UIN: 111B015V02): In case death due to an
accident, the rider Sum Assured is payable in addition to normal death benefit
SBI Life - Accidental Total & Permanent Disability Benefit Rider (111B016V02): The rider
Sum Assured will be paid on the Life Assured being found eligible for the Total Permanent
Disability Benefit as defined in the policy document.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 90
Tax Benefits:
• Tax deduction under Section 80(C) is available.
• Tax exemption under Section 10(10D) is available.
3.27.3 SBI Life - Saral swadhan+
(UIN: 111N092V01)
SBI Life - Saral Swadhan+ is an Individual, non-linked, non-participating, term assurance
product with return of premium. This product gives a fixed life cover throughout the policy term
along with a guaranteed maturity benefit.
Key Features:
• Protection at affordable cost.
• Value for money.
• Easy enrollment through simplified proposal form.
Benefits:
• On Maturity: On survival till the end of the policy term we get,
• Policy term 10 years - 100% of the total premiums paid
• Policy term 15 years - 115% of the total premiums paid
• Maturity benefit will be payable provided at least 3 annual premiums have been
paid
• Paid up value:
Any time during the policy term if the premiums are not paid within grace period, the policy
shall lapse.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 91
• A lapsed policy will acquire paid-up only if at least three year’s premiums have
been paid.
• On Death:
In case of death of life assured during the policy term, the nominee will receive Sum assured.
• Tax Benefits:
• Tax deduction under Section 80(C) is available.
• Tax exemption under Section 10(10D) is available at the time of
maturity/surrender.
3.27.4 SBI Life - Flexi smart plus
(UIN: 111N093V01) (Product Code: 1M)
SBI Life - Flexi Smart Plus is Individual, Participating, and variable Insurance Product. It also
gives us flexibility to adapt to our ever-changing needs, while assuring guaranteed benefits to
take care of our savings.
Key Features:
• Guaranteed Minimum Bonus Interest rate* Conditions apply
A minimum bonus interest rate of 1.00% p.a. is guaranteed for the whole term.
• Interim bonus interest rate
An Interim bonus interest rate will be declared at the beginning of each financial year which will
apply to the policies exiting during the financial year.
• Regular Bonus Interest rate
Regular Bonus interest rate will be declared at the end of every financial year.
• Terminal Bonus Interest rate
Terminal bonus interest rate may be credited to our policy account at the time of exit on account
of maturity, death or surrender.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 92
Our policy will be credited with the Regular Bonus interest rates and Terminal Bonus interest
rate, if any. Regular bonus interest rate once declared becomes guaranteed for the policy account.
• Two Protection option available: Gold Option and Platinum Option
• Partial Withdrawal
Partial withdrawals are allowed from the 6th policy year to cater to liquidity needs.
• Flexibility to increase or decrease chosen Sum assured
• Flexibility to increase our chosen policy term
Benefits:
• On Death
In case of unfortunate event of death of the Life Assured, the beneficiary will receive the
following benefit:
For Gold Option: Higher of Policy Account Value or Sum Assured^ / Paid-up Sum Assured^ as
applicable or 105% of total premiums paid as on the date of intimation of death claim.
Sum assured will be reduced to the extent of partial withdrawals made in the last 2 years for age
on death below 60 years and for age at death 60 years & above all partial withdrawals made from
58 years onwards.
For Platinum Option: Higher of Policy Account Value PLUS Sum Assured / Paid-up Sum
Assured as applicable or 105% of total premiums paid as on the date of intimation of death
claim.
• On Survival
Maturity Benefit on maturity, the policy holder will be entitled to policy account value including
Terminal Bonus interest rate if any, calculated on the maturity date and will be payable as a lump
sum on maturity.
• Tax Benefits
• Tax deduction under Section 80 C is available.
• Tax exemption under Section 10(10D) is available at the time of
maturity/surrender.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 93
• Tax benefits, are as per the provisions of the Income Tax laws & are subject to
change from time to time.
OTHER PRODUCTS
3.28 group products
SBI Life offers a wide range of employee benefit solutions which helps organizations to retain,
reward and encourage the best talent in the industry. It also provides a host of corporate solutions
to both statutory needs as well as voluntary needs of the employers and hence ensures to
strengthen the employer -employee relationship in the long run.
3.28.1 Retirement solutions
1. SBI Life - Kalyan ULIP Plus
2. SBI Life - CapAssure Gold
3. SBI life - Swarna Jeevan
4. SBI Life - Gaurav Jeevan
3.28.2 GROUP PROTECTION PLANS
1. SBI Life - Sampoorn Suraksha
3.28.3 GROUP LOAN PROTECTION PRODUCTS
1. SBI Life - RiNn Raksha
3.28.4 GROUP MICRO INSURANCE PLANS
1. SBI Life - Grameen Shakti
2. SBI Life - Grameen Super Suraksha
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 94
CHAPTER-4
DATA ANALYSIS AND INTERPRETATION
Analysis of data is a process of inspecting, cleaning, transforming, and modeling data
with the goal of highlighting useful information, suggesting, conclusions and supporting decision
making. The analysis of data requires a number of closely related operations such as
establishment of categories, the application of these categories to raw data through coding,
tabulation and then drawing statistical inferences. In brief, the researcher can analyze the
collected data with the help of the various statistical measures.
The data on “Consumer Perception on Life Insurance-A study on State Bank of India Life
Insurance in Krishnarajanagara” collected from consumers using a questionnaire. A sample of
125 existing customers of SBI Life insurance was chosen for the study and their responses have
been presented in the form of table for future analysis and interpretation.
The observation method and questionnaire are used as the research instrument and to
interpret statistical tool like bar graphs and pie chart are used.
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 95
TABLE 4.1: GENDER WISE DISTRIBUTION OF RESPONDENTS
Gender No. of respondents Percentage (%)
Male 84 68
Female 39 32
Total 123 100
Source: Primary data
CHART 4.1
Interpretation:
From the graph it is clear that, out of 123 respondents, majority (68.3%) of the
respondents were Men, 31.7 percent of the respondents were women. which shows male are
interested to invest in life insurance more than female. Because of family responsibility, opposite
circumstance.
Male
68%
Female
32%
GENDER WISE DISTRIBUTION
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 96
TABLE 4.2: AGE GROUP OF RESPONDENTS
Age group No. Of respondents Percentage (%)
Below 18 years 16 13
18-35 years 33 27
35-50 years 55 45
50 & above 19 15
Total 123 100
Source: Primary data
CHART 4.2
Interpretation:
From the graph it is clear that, out of 123 respondents, 16 respondents are falls in
the Age group of (below 18 ), 33 respondents are falls in the Age Group of (18 to 35), 55
respondents are falls in the Age Group of (36 to 50) and 19 respondents fall in the Age Group of
(50 & above). This shows that the interest in investing insurance is more for peoples aged
between age group of 35-50 years
13%
27%
45%
15%
AGE GROUP OF RESPONDENTS
Below 18
18 TO 35
36 TO 50
50 & Above
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 97
TABLE 4.3: EDUCATION KNOWLEDGE OF RESPONDENTS
Gender No. of respondents Percentage (%)
Literate 107 87
Illiterate 16 13
Total 123 100
Source: Primary data
CHART 4.3
Interpretation:
From the above table, it is clear that out of 123 respondents, majority (i.e. 107)
respondents are educated and only 13% of respondents are uneducated.
6%
94%
EDUCATION KNOWLEDGE OF RESPONDENTS
Literate Illiterate
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 98
TABLE 4.4: QUALIFICATION OF RESPONDENTS
Qualification Number of respondent Percentage(%)
Undergraduate 52 48
Graduate 31 29
Post graduate 21 20
Other 03 03
Total 107 100
Source: Primary data
CHART 4.4
Interpretation:
From the above table, it is clear that out of 123 respondents, majority (i.e. 52)
respondents are belong to Under Graduate which shows under graduates are more interested in
investing in life insurance, 31 respondents are belong to Graduate, 21 respondents are belong to
Post Graduate and 19 respondents belong to other categories, like professional course. This
shows their less interest in insurance investments. Based on the occupational level, respondents
were able to choose the suitable life insurance products.
0%
10%
20%
30%
40%
50%
60%
Undergraduate Graduate Post graduate Other
QUALIFICATION OF RESPONDENTS
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 99
TABLE 4.5: OCCUPATION OF RESPONDENTS
Occupation Number of respondents Percentage(%)
Agriculture 20 16
Government employee 20 16
Private employee 45 37
Business man 21 17
Others 17 14
Total 123 100
Source: Primary data
CHART 4.5
Interpretation:
From the graph it has been observed that, 20 out of 123 respondents are belong to
agriculture, 20 respondents are govt employees, 45 respondents are belong to Private Employee
are more interested in taking life insurance policy, 21 respondents belong to Businessmen, 17
respondents are belong to are belong to other categories, like students. This show their interest
for investing in life insurance is less than private employee respondents
0%
5%
10%
15%
20%
25%
30%
35%
40%
Agriculture
Govt. employee
Private employee
Businessmen
Others
Consumer Perception on Life Insurance
DOS IN COMMERCE, MANASAGANGOTRI, MYSORE 2013-2014 Page 100
TABLE 4.6: INCOME GROUP OF RESPONDENTS
Annual Income (Rs.) Number of respondents Percentage(%)
Not earning 05 04
less than 100000 29 24
100000 -300000 36 29
300000- 500000 32 26
500000 & above 21 17
Total 123 100
Source: Primary data
CHART 4.6
Interpretation:
The income level of the family of the respondents influences the choice of
insurance products. From the graph it has been observed that, out of 123 respondents, 36
respondents have the income between (100000 to 300000) which shows more interest in
investing in life insurance, 32 respondents have the income between (300000 to 500000) which
show they give moderate preference to life insurance investments, 29 respondents have the
Income (Less than 100000), 21 respondents have the income between (500000 & above) and 05
respondents not earning any income. This shows they give less preference for life insurance
investments.
4%
24%
29%
26%
17%
PERCENTAGE
Not earning
Less than 100000
100000 to 300000
300000 to 500000
500000 & Above