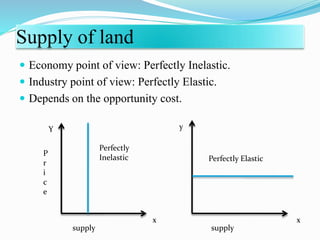
The document discusses theories of factor price determination. It begins by introducing the classical theory of distribution known as the marginal productivity theory. This theory states that in equilibrium, each factor of production will be rewarded according to its marginal productivity. The document then explains the marginal productivity theory in more detail and lists its assumptions. Finally, it introduces the modern theory of distribution, which says that factor prices are determined by the demand and supply of each factor, with the equilibrium price occurring at the intersection of the demand and supply curves.

 Most read

 Most read
 Most read