Q&Me is online market research provided by Asia Plus Inc. Asia Plus Inc.
How does the increase of modern channel change
purchase behaviors of mom?
Objective
Vietnam has seen an increase in the number
of modern stores such as supermarkets,
shopping malls and especially convenience
stores. How does the change affect the
shopping behaviors of Vietnamese moms,
especially on their traditional shopping
experience at GT channels?
We conducted a large scale survey on more
than 1,000 moms in the age of 20 - 39 in
Hanoi and Ho Chi Minh to understand the
differences in their shopping behaviors.
Retail types
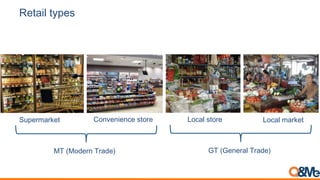
Supermarket Convenience store Local store Local market
MT (Modern Trade) GT (General Trade)
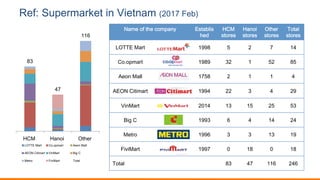
Ref: Supermarket in Vietnam (2017 Feb)
Name of the company Establis
hed
HCM
stores
Hanoi
stores
Other
stores
Total
stores
LOTTE Mart 1998 5 2 7 14
Co.opmart 1989 32 1 52 85
Aeon Mall 1758 2 1 1 4
AEON Citimart 1994 22 3 4 29
VinMart 2014 13 15 25 53
Big C 1993 6 4 14 24
Metro 1996 3 3 13 19
FiviMart 1997 0 18 0 18
Total 83 47 116 246
83
47
116
HCM Hanoi Other
LOTTE Mart Co.opmart Aeon Mall
AEON Citimart VinMart Big C
Metro FiviMart Total
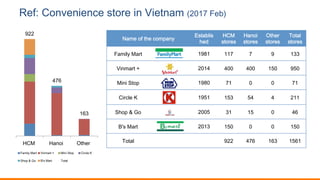
Ref: Convenience store in Vietnam (2017 Feb)
Name of the company
Establis
hed
HCM
stores
Hanoi
stores
Other
stores
Total
stores
Family Mart 1981 117 7 9 133
Vinmart + 2014 400 400 150 950
Mini Stop 1980 71 0 0 71
Circle K 1951 153 54 4 211
Shop & Go 2005 31 15 0 46
B's Mart 2013 150 0 0 150
Total 922 476 163 1561
922
476
163
HCM Hanoi Other
Family Mart Vinmart + Mini Stop Circle K
Shop & Go B's Mart Total
Mom’s shopping behaviors
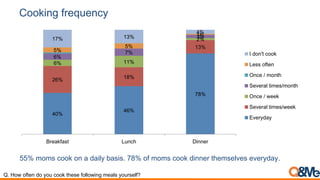
Cooking frequency
55% moms cook on a daily basis. 78% of moms cook dinner themselves everyday.
Q. How often do you cook these following meals yourself?
40%
46%
78%
26% 18%
13%
6% 11%
2%
6%
7%
3%
5%
5%
1%
17% 13%
4%
Breakfast Lunch Dinner
I don't cook
Less often
Once / month
Several times/month
Once / week
Several times/week
Everyday
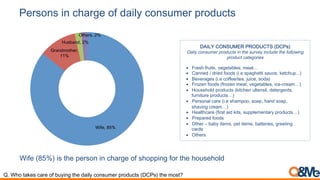
Persons in charge of daily consumer products
Wife (85%) is the person in charge of shopping for the household
Q. Who takes care of buying the daily consumer products (DCPs) the most?
Wife, 85%
Grandmother,
11%
Husband, 2%
Others, 2%
DAILY CONSUMER PRODUCTS (DCPs)
Daily consumer products in the survey include the following
product categories
•  Fresh fruits, vegetables, meat…
•  Canned / dried foods (i.e spaghetti sauce, ketchup...)
•  Beverages (i.e coffee/tea, juice, soda)
•  Frozen foods (frozen meat, vegetables, ice-cream…)
•  Household products (kitchen ultensil, detergents,
furniture products…)
•  Personal care (i.e shampoo, soap, hand soap,
shaving cream…)
•  Healthcare (first aid kits, supplementary products…)
•  Prepared foods
•  Other – baby items, pet items, batteries, greeting
cards
•  Others
Availability of modern channels
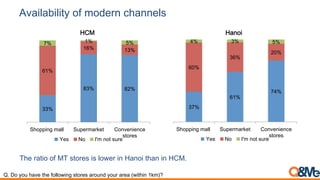
The ratio of MT stores is lower in Hanoi than in HCM.
Q. Do you have the following stores around your area (within 1km)?
33%
83% 82%
61%
16% 13%
7% 1% 5%
Shopping mall Supermarket Convenience
stores
HCM
Yes No I'm not sure
37%
61%
74%
60%
36%
20%
4% 3% 5%
Shopping mall Supermarket Convenience
stores
Hanoi
Yes No I'm not sure
What stores do they use for DCPs shopping?
60% 58%
40%
25%
14%
1%
74%
57%
32%
24%
13%
1%
48%
59%
48%
28%
15%
1%
Supermarket Local market Local store Convenience stores Shopping mall Others
All HCM Hanoi
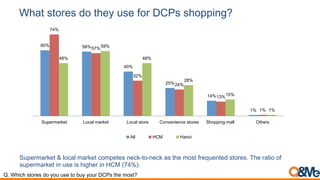
Supermarket & local market competes neck-to-neck as the most frequented stores. The ratio of
supermarket in use is higher in HCM (74%).
Q. Which stores do you use to buy your DCPs the most?
What stores do they use for DCPs shopping? (by location)
60% 58%
40%
25%
14%
1% 1%
73%
56%
37%
32%
16%
1% 0%
24%
68%
47%
6% 7%
1% 0%
Supermarket Local market Local store Convenience
stores
Shopping mall Others Others
All Those who have MT near their area Those who do not have MTs near their area
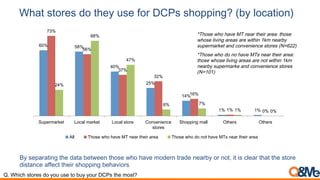
*Those who have MT near their area: those
whose living areas are within 1km nearby
supermarket and convenience stores (N=622)
*Those who do no have MTs near their area:
those whose living areas are not within 1km
nearby supermarke and convenience stores
(N=101)
By separating the data between those who have modern trade nearby or not, it is clear that the store
distance affect their shopping behaviors
Q. Which stores do you use to buy your DCPs the most?
Modern trade that moms use for DCP purchase
52%
48%
32%
30%
20%
18%
14%
11% 11% 10% 9% 8% 8%
5% 5% 4% 3% 3% 2% 1%
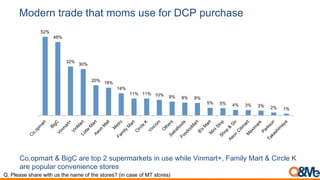
Co.opmart & BigC are top 2 supermarkets in use while Vinmart+, Family Mart & Circle K
are popular convenience stores
Q. Please share with us the name of the stores? (in case of MT stores)
Reasons to select modern trade
A variety
of
products
Location
Good
quality of
products
Good
pricing
Good
promotio
ns
Fresh
foods
Quick
shopping
duration
Members
hip
Support
of a
variety of
promotio
n method
I can buy
products
in large
quantity
Good
parking
slots
The
location
has
many
other
entertain
ment
Good
delivery
service
Good
atmosph
ere
Opening
hours
Pricing
are
negotiabl
e
Good
relations
hips with
the
vendors
Others
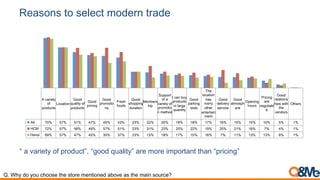
All 70% 57% 51% 47% 45% 43% 23% 22% 20% 18% 18% 17% 16% 15% 15% 10% 5% 1%
HCM 72% 57% 56% 49% 57% 51% 23% 31% 23% 20% 22% 19% 25% 21% 16% 7% 4% 1%
Hanoi 69% 57% 47% 45% 35% 37% 23% 15% 18% 17% 15% 16% 7% 11% 13% 13% 6% 1%
“ a variety of product”, “good quality” are more important than “pricing”
Q. Why do you choose the store mentioned above as the main source?
Shopping behaviors difference between MT and GT
Shopping frequency
Every day
4-6 times
a week
2-3 times
a week
Once a
week
Several
times /
month
Once /
month
Less
ofthen
than that
I don't
shop here
Others
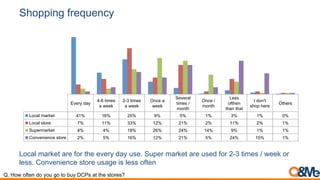
Local market 41% 16% 25% 9% 5% 1% 3% 1% 0%
Local store 7% 11% 33% 12% 21% 2% 11% 2% 1%
Supermarket 4% 4% 18% 26% 24% 14% 9% 1% 1%
Convenience store 2% 5% 16% 12% 21% 5% 24% 15% 1%
Local market are for the every day use. Super market are used for 2-3 times / week or
less. Convenience store usage is less often
Q. How often do you go to buy DCPs at the stores?
Transportation to stores
82%
27%
4% 2% 1%
52%
44%
3%
0% 0%
92%
8% 6% 5%
1%
72%
25%
0% 0% 2%
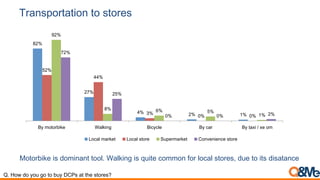
By motorbike Walking Bicycle By car By taxi / xe om
Local market Local store Supermarket Convenience store
Motorbike is dominant tool. Walking is quite common for local stores, due to its disatance
Q. How do you go to buy DCPs at the stores?
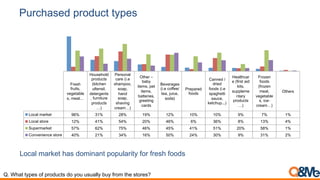
Purchased product types
Fresh
fruits,
vegetable
s, meat…
Household
products
(kitchen
ultensil,
detergents
, furniture
products
…)
Personal
care (i.e
shampoo,
soap,
hand
soap,
shaving
cream…)
Other –
baby
items, pet
items,
batteries,
greeting
cards
Beverages
(i.e coffee/
tea, juice,
soda)
Prepared
foods
Canned /
dried
foods (i.e
spaghetti
sauce,
ketchup...)
Healthcar
e (first aid
kits,
suppleme
ntary
products
…)
Frozen
foods
(frozen
meat,
vegetable
s, ice-
cream…)
Others
Local market 96% 31% 28% 19% 12% 10% 10% 9% 7% 1%
Local store 12% 41% 54% 20% 46% 6% 36% 8% 13% 4%
Supermarket 57% 62% 75% 46% 45% 41% 51% 20% 58% 1%
Convenience store 40% 21% 34% 16% 50% 24% 30% 9% 31% 2%
Local market has dominant popularity for fresh foods
Q. What types of products do you usually buy from the stores?
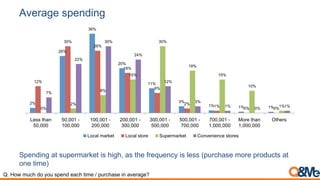
Average spending
2%
26%
36%
20%
11%
3%
1% 1% 1%
12%
30%
28%
18%
9%
2%
1%
0% 0%0%
2%
8%
15%
30%
19%
15%
10%
1%
7%
22%
30%
24%
12%
3%
1%
0%
1%
Less than
50,000
50,001 -
100,000
100,001 -
200,000
200,001 -
300,000
300,001 -
500,000
500,001 -
700,000
700,001 -
1,000,000
More than
1,000,000
Others
Local market Local store Supermarket Convenience stores
Spending at supermarket is high, as the frequency is less (purchase more products at
one time)
Q. How much do you spend each time / purchase in average?
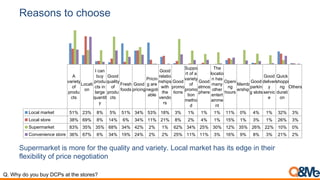
Reasons to choose
A
variety
of
produ
cts
Locati
on
I can
buy
produ
cts in
large
quantit
y
Good
quality
of
produ
cts
Fresh
foods
Good
pricing
Pricin
g are
negoti
able
Good
relatio
nships
with
the
vendo
rs
Good
promo
tions
Suppo
rt of a
variety
of
promo
tion
metho
d
Good
atmos
phere
The
locatio
n has
many
other
entert
ainme
nt
Openi
ng
hours
Memb
ership
Good
parkin
g slots
Good
deliver
y
servic
e
Quick
shoppi
ng
durati
on
Others
Local market 51% 23% 8% 5% 51% 34% 53% 18% 3% 1% 1% 1% 11% 0% 4% 1% 32% 3%
Local store 38% 69% 8% 14% 6% 34% 11% 21% 8% 2% 4% 1% 15% 1% 3% 1% 26% 3%
Supermarket 83% 35% 35% 68% 34% 42% 2% 1% 62% 34% 25% 30% 12% 35% 26% 22% 10% 0%
Convenience store 36% 67% 6% 34% 19% 24% 2% 2% 25% 11% 11% 3% 16% 9% 8% 3% 21% 2%
Supermarket is more for the quality and variety. Local market has its edge in their
flexibility of price negotiation
Q. Why do you buy DCPs at the stores?
Modern trade impact on GT sales
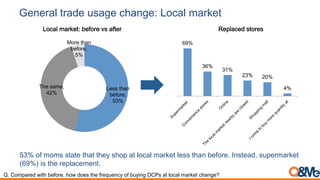
General trade usage change: Local market
53% of moms state that they shop at local market less than before. Instead, supermarket
(69%) is the replacement.
69%
36%
31%
23% 20%
4%
Replaced stores
Less than
before,
53%
The same,
42%
More than
before,
5%
Local market: before vs after
Q. Compared with before, how does the frequency of buying DCPs at local market change?
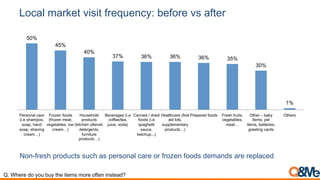
Local market visit frequency: before vs after
50%
45%
40%
37% 36% 36% 36% 35%
30%
1%
Personal care
(i.e shampoo,
soap, hand
soap, shaving
cream…)
Frozen foods
(frozen meat,
vegetables, ice-
cream…)
Household
products
(kitchen ultensil,
detergents,
furniture
products…)
Beverages (i.e
coffee/tea,
juice, soda)
Canned / dried
foods (i.e
spaghetti
sauce,
ketchup...)
Healthcare (first
aid kits,
supplementary
products…)
Prepared foods Fresh fruits,
vegetables,
meat…
Other – baby
items, pet
items, batteries,
greeting cards
Others
Non-fresh products such as personal care or frozen foods demands are replaced
Q. Where do you buy the items more often instead?
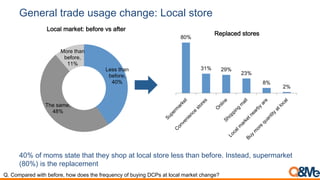
General trade usage change: Local store
40% of moms state that they shop at local store less than before. Instead, supermarket
(80%) is the replacement
Q. Compared with before, how does the frequency of buying DCPs at local market change?
Less than
before,
40%
The same,
48%
More than
before,
11%
Local market: before vs after
80%
31% 29%
23%
8%
2%
Replaced stores
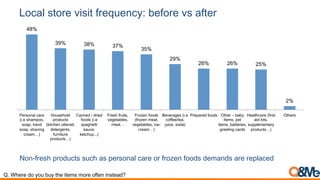
Local store visit frequency: before vs after
48%
39% 38% 37%
35%
29%
26% 26% 25%
2%
Personal care
(i.e shampoo,
soap, hand
soap, shaving
cream…)
Household
products
(kitchen ultensil,
detergents,
furniture
products…)
Canned / dried
foods (i.e
spaghetti
sauce,
ketchup...)
Fresh fruits,
vegetables,
meat…
Frozen foods
(frozen meat,
vegetables, ice-
cream…)
Beverages (i.e
coffee/tea,
juice, soda)
Prepared foods Other – baby
items, pet
items, batteries,
greeting cards
Healthcare (first
aid kits,
supplementary
products…)
Others
Non-fresh products such as personal care or frozen foods demands are replaced
Q. Where do you buy the items more often instead?
Potentiality of online shopping
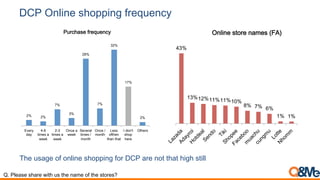
DCP Online shopping frequency
The usage of online shopping for DCP are not that high still
43%
13%12%11%11%10%
8% 7% 6%
1% 1%
Online store names (FA)
2% 2%
7%
3%
28%
7%
32%
17%
2%
Every
day
4-6
times a
week
2-3
times a
week
Once a
week
Several
times /
month
Once /
month
Less
ofthen
than that
I don't
shop
here
Others
Purchase frequency
Q. Please share with us the name of the stores?
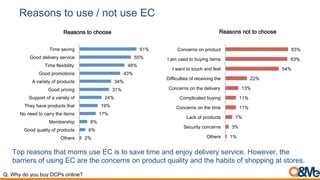
Reasons to use / not use EC
Top reasons that moms use EC is to save time and enjoy delivery service. However, the
barriers of using EC are the concerns on product quality and the habits of shopping at stores.
Q. Why do you buy DCPs online?
2%
6%
8%
17%
19%
24%
31%
34%
43%
48%
55%
61%
Others
Good quality of products
Membership
No need to carry the items
They have products that
Support of a variety of
Good pricing
A variety of products
Good promotions
Time flexibility
Good delivery service
Time saving
Reasons to choose
1%
3%
7%
11%
11%
13%
22%
54%
63%
63%
Others
Security concerns
Lack of products
Concerns on the time
Complicated buying
Concerns on the delivery
Difficulties of receiving the
I want to touch and feel
I am used to buying items
Concerns on product
Reasons not to choose
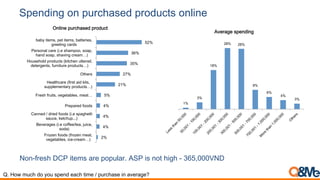
Spending on purchased products online
Non-fresh DCP items are popular. ASP is not high - 365,000VND
1%
3%
18%
28% 28%
9%
6%
4%
3%
Average spending
Q. How much do you spend each time / purchase in average?
2%
4%
4%
4%
5%
21%
27%
35%
36%
52%
Frozen foods (frozen meat,
vegetables, ice-cream…)
Beverages (i.e coffee/tea, juice,
soda)
Canned / dried foods (i.e spaghetti
sauce, ketchup...)
Prepared foods
Fresh fruits, vegetables, meat…
Healthcare (first aid kits,
supplementary products…)
Others
Household products (kitchen ultensil,
detergents, furniture products…)
Personal care (i.e shampoo, soap,
hand soap, shaving cream…)
baby items, pet items, batteries,
greeting cards
Online purchased product
Summary
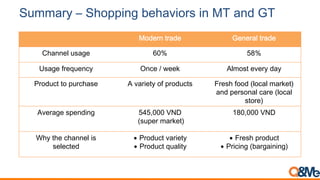
Summary – Shopping behaviors in MT and GT
Modern trade General trade
Channel usage 60% 58%
Usage frequency Once / week Almost every day
Product to purchase A variety of products Fresh food (local market)
and personal care (local
store)
Average spending 545,000 VND
(super market)
180,000 VND
Why the channel is
selected
• Product variety
• Product quality
• Fresh product
• Pricing (bargaining)
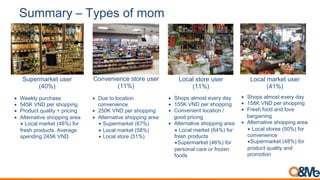
Summary – Types of mom
Supermarket user
(40%)
Convenience store user
(11%)
Local store user
(11%)
Local market user
(41%)
•  Shops almost every day
•  158K VND per shopping
•  Fresh food and love
bargaining
•  Alternative shopping area
• Local stores (50%) for
convenience
• Supermarket (48%) for
product quality and
promotion
•  Shops almost every day
•  155K VND per shopping
•  Convenient location /
good pricing
•  Alternative shopping area
• Local market (64%) for
fresh products
• Supermarket (46%) for
personal care or frozen
foods
•  Weekly purchase
•  545K VND per shopping
•  Product quality + pricing
•  Alternative shopping area
• Local market (48%) for
fresh products. Average
spending 245K VND
•  Due to location
convenience
•  250K VND per shopping
•  Alternative shopping area
• Supermarket (67%)
• Local market (58%)
• Local store (51%)
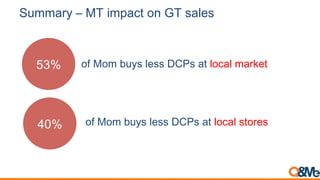
Summary – MT impact on GT sales
of Mom buys less DCPs at local market53%
40% of Mom buys less DCPs at local stores
Appendix: Analysis via district
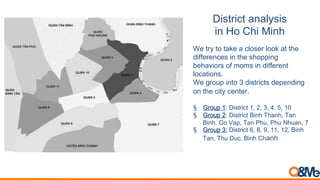
District analysis 

in Ho Chi Minh
We try to take a closer look at the
differences in the shopping
behaviors of moms in different
locations.
We group into 3 districts depending
on the city center.
§  Group 1: District 1, 2, 3, 4, 5, 10
§  Group 2: District Binh Thanh, Tan
Binh, Go Vap, Tan Phu, Phu Nhuan, 7
§  Group 3: District 6, 8, 9, 11, 12, Binh
Tan, Thu Duc, Binh Chanh
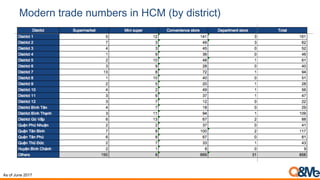
Modern trade numbers in HCM (by district)
As of June 2017
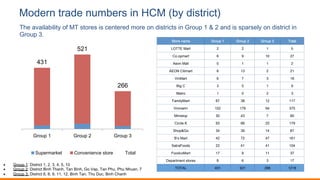
Modern trade numbers in HCM (by district)
Store name Group 1 Group 2 Group 3 Total
LOTTE Mart 2 2 1 5
Co.opmart 6 9 10 27
Aeon Mall 0 1 1 2
AEON Citimart 6 13 2 21
VinMart 6 7 3 16
Big C 3 5 1 9
Metro 1 0 2 3
FamilyMart 67 38 12 117
Vinmart+ 102 179 94 375
Ministop 30 43 7 80
Circle K 93 66 20 179
Shop&Go 34 39 14 87
B’s Mart 42 72 47 161
SatraFoods 22 41 41 104
FoodcoMart 17 9 11 37
Department stores 8 6 3 17
TOTAL 431 521 266 1218
431
521
266
Group 1 Group 2 Group 3
Supermarket Convenience store Total
•  Group 1: District 1, 2, 3, 4, 5, 10
•  Group 2: District Binh Thanh, Tan Binh, Go Vap, Tan Phu, Phu Nhuan, 7
•  Group 3: District 6, 8, 9, 11, 12, Binh Tan, Thu Duc, Binh Chanh
The availability of MT stores is centered more on districts in Group 1 & 2 and is sparsely on district in
Group 3.
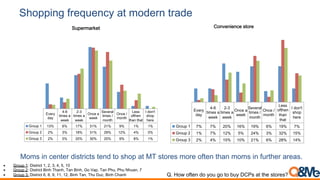
Shopping frequency at modern trade
Moms in center districts tend to shop at MT stores more often than moms in further areas.
Q. How often do you go to buy DCPs at the stores?
Every
day
4-6
times a
week
2-3
times a
week
Once a
week
Several
times /
month
Once /
month
Less
ofthen
than that
I don't
shop
here
Group 1 13% 6% 17% 31% 21% 9% 1% 1%
Group 2 2% 3% 18% 31% 29% 12% 4% 0%
Group 3 2% 5% 20% 30% 25% 9% 8% 1%
Supermarket
Every
day
4-6
times a
week
2-3
times a
week
Once a
week
Several
times /
month
Once /
month
Less
ofthen
than
that
I don't
shop
here
Group 1 7% 7% 20% 16% 19% 6% 19% 7%
Group 2 1% 7% 12% 5% 24% 3% 32% 15%
Group 3 2% 4% 15% 10% 21% 6% 28% 14%
Convenience store
•  Group 1: District 1, 2, 3, 4, 5, 10
•  Group 2: District Binh Thanh, Tan Binh, Go Vap, Tan Phu, Phu Nhuan, 7
•  Group 3: District 6, 8, 9, 11, 12, Binh Tan, Thu Duc, Binh Chanh
Audience profile
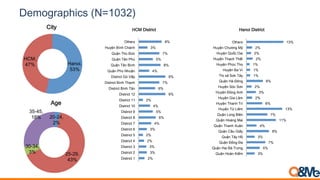
Demographics (N=1032)
Hanoi,
53%
HCM,
47%
City
2%
3%
3%
2%
2%
3%
4%
6%
5%
4%
2%
9%
6%
7%
9%
4%
8%
5%
7%
3%
8%
District 1
District 2
District 3
District 4
District 5
District 6
District 7
District 8
District 9
District 10
District 11
District 12
District Bình Tân
District Bình Thạnh
District Gò Vấp
Quận Phú Nhuận
Quận Tân Bình
Quận Tân Phú
Quận Thủ Đức
Huyện Bình Chánh
Others
HCM District
3%
5%
7%
3%
8%
4%
11%
7%
13%
6%
2%
3%
2%
6%
1%
1%
1%
2%
2%
2%
13%
Quận Hoàn Kiếm
Quận Hai Bà Trưng
Quận Đống Đa
Quận Tây Hồ
Quận Cầu Giấy
Quận Thanh Xuân
Quận Hoàng Mai
Quận Long Biên
Huyện Từ Liêm
Huyện Thanh Trì
Huyện Gia Lâm
Huyện Đông Anh
Huyện Sóc Sơn
Quận Hà Đông
Thị xã Sơn Tây
Huyện Ba Vì
Huyện Phúc Thọ
Huyện Thạch Thất
Huyện Quốc Oai
Huyện Chương Mỹ
Others
Hanoi District
20-24,
2%
25-29,
43%
30-34,
3%
35-45,
18%
Age
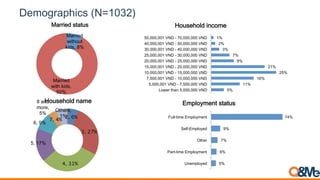
Demographics (N=1032)
5%
11%
16%
25%
21%
9%
7%
3%
2%
1%
Lower than 5,000,000 VND
5,000,001 VND - 7,500,000 VND
7,500,001 VND - 10,000,000 VND
10,000,001 VND - 15,000,000 VND
15,000,001 VND - 20,000,000 VND
20,000,001 VND - 25,000,000 VND
25,000,001 VND - 30,000,000 VND
30,000,001 VND - 40,000,000 VND
40,000,001 VND - 50,000,000 VND
50,000,001 VND - 70,000,000 VND
Household income
Married
without
kids, 8%
Married
with kids,
92%
Married status
2, 6%
3, 27%
4, 31%
5, 17%
6, 9%
7, 4%
8 and
more,
5%
Others,
1%
Household name
5%
6%
7%
9%
74%
Unemployed
Part-time Employment
Other
Self-Employed
Full-time Employment
Employment status
Q&Me – About Online Market Research Services
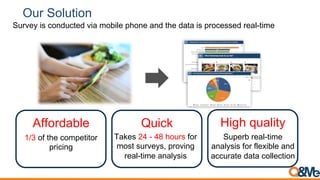
Survey is conducted via mobile phone and the data is processed real-time
Affordable Quick High quality
Takes 24 - 48 hours for
most surveys, proving
real-time analysis
Superb real-time
analysis for flexible and
accurate data collection
1/3 of the competitor
pricing
Our Solution
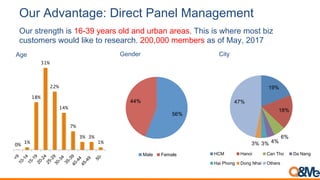
Our strength is 16-39 years old and urban areas. This is where most biz
customers would like to research. 200,000 members as of May, 2017
0%
1%
18%
31%
22%
14%
7%
3% 3%
1%
Age
19%
18%
6%
4%3%3%
47%
HCM Hanoi Can Tho Da Nang
Hai Phong Dong Nhai Others
56%
44%
Male Female
Gender City
Our Advantage: Direct Panel Management
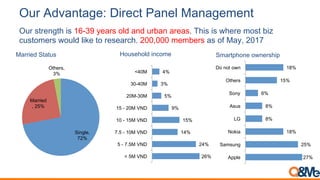
Our strength is 16-39 years old and urban areas. This is where most biz
customers would like to research. 200,000 members as of May, 2017
Married Status Household income Smartphone ownership
Single,
72%
Married
, 25%
Others,
3%
26%
24%
14%
15%
9%
5%
3%
4%
< 5M VND
5 - 7.5M VND
7.5 - 10M VND
10 - 15M VND
15 - 20M VND
20M-30M
30-40M
<40M
27%
25%
18%
8%
8%
6%
15%
18%
Apple
Samsung
Nokia
LG
Asus
Sony
Others
Do not own
Our Advantage: Direct Panel Management
Contact Us
URL: http://www.qandme.net
Contact: info@qandme.net
Q&Me is operated by Asia Plus Inc.
Asia Plus Inc.
Floor 1 25/7A Nguyen Binh Khiem str., Ben Nghe ward, District 1, HCMC,
Vietnam
Tel. +84 839 100 043