PRINCIPLES OF INSURANCE


                PRESENTED BY:

                  CHAITHRA.G
                   CHAITRA.M.
                  CHANDNI.K.
                  DEVIKA.B.Z.
                 NIVEDITHA.C.
INSURANCE

              Insurance is a form of risk management
primarily used to hedge against the risk of a
contingent, uncertain loss. Insurance is defined as the
equitable transfer of the risk of a loss, from one entity to
another, in exchange for payment.
 An insurer is a company selling the insurance.
 The insured, or policyholder, is the person or entity buying
  the insurance policy.
 The amount to be charged for a certain amount of
  insurance coverage is called the premium.
Insurance governed acts

1) The insurance Act, 1938


2) The life insurance corporation Act, 1956


3) The Marine Insurance Act, 1963


4) The General Insurance Business Act, 1972
Contract of Insurance

            Is a contract whereby the insurer
undertakes to make good the loss of another called the
insured by payment of some money to him on the
happening of a specific event.
Terminologies used

 Insurer
 Insured
 Premium
 Policy
 Subject matter
 Insurable interest
 Insurable risk
Insurable Risk

 The law of large number.


 The loss produced by the risk must be definite.


 The loss must be fortuitous or accidental.


 The loss must not be catastrophic.
Criteria of determination of whether a risk can be
                  insured or not

 The risk must arise out of the ordinary course of
  business and it should not be artificially created by
  parties.
 The risk must be common enough to justify its
  spreading at a nominal cost.
 There must be an element of uncertainty as to the
  occurrence of risk or the time of the occurrence.
 The party must have some real interest in avoiding
  the risk.
Types of insurance

1) Personal or Life insurance


2) Property insurance


3) Liability insurance


4) Guarantee insurance
Fundamental principles of insurance


1) Essential elements of a valid contract.
    There must be contract between two parties i.e. insurer
     and insured.
    The contract must be in writing.
    The insurance policy is printed, stamped, signed my the
     insurer and handed over to the insured.
    It should have a valid offer, acceptance and
     consideration.
    There should be a lawful object.
Contd…


2) Principle of co-operation and probability.
3) Utmost good faith.
4) Indemnity.
5) Contingent contract.
6) Insurable interest.
7) Aleatory contract.
8) Term of policy.
Contd…


9) Commencement of risk.
10) Premium.
11) Causa proxima.
12) Mitigation of loss.
13) Contribution.
14) Subrogation.
15) Reinsurance.
16) Double insurance.
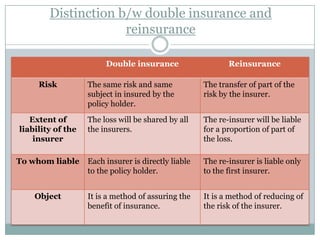
Distinction b/w double insurance and
                     reinsurance

                        Double insurance                    Reinsurance

     Risk          The same risk and same            The transfer of part of the
                   subject in insured by the         risk by the insurer.
                   policy holder.
   Extent of       The loss will be shared by all    The re-insurer will be liable
liability of the   the insurers.                     for a proportion of part of
    insurer                                          the loss.

To whom liable     Each insurer is directly liable   The re-insurer is liable only
                   to the policy holder.             to the first insurer.


    Object         It is a method of assuring the    It is a method of reducing of
                   benefit of insurance.             the risk of the insurer.
Wager

       The meaning of ‘wagering’ is staking something of
value upon the result of some future uncertain event, such
as a horse race, or upon the ascertainment of the truth
concerning some past or present event.

 An agreement under which each bettor pledges a certain
  amount to the other depending on the outcome of an
  unsettled matter.
 A matter bet on; a gamble.
 Something staked on an uncertain outcome.
 A pledge of personal combat to resolve an issue or case.
Ingredients of a wager contract

1) It can relate to part, present or future act or event.


2) One party is to win and the other party is to lose
   upon the determination of the event.

3) There shall be two persons either to whom stands
   to win or lose

4) Stake is the only interest between the two parties.
   They have no real interest in the subject matter.
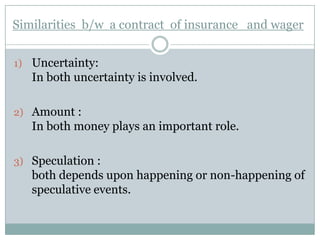
Similarities b/w a contract of insurance and wager


1) Uncertainty:
   In both uncertainty is involved.

2) Amount :
   In both money plays an important role.

3) Speculation :
   both depends upon happening or non-happening of
   speculative events.
Return of premium

      There are circumstances which make the contract
of insurance void or even voidable. The contract of
insurance is voidable when the affected party has opted
to avoid the contract. This usually happens when the
consideration has failed.
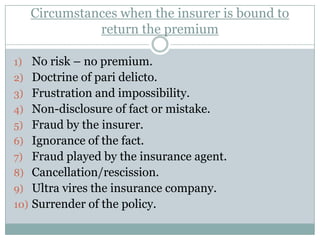
Circumstances when the insurer is bound to
             return the premium

1) No risk – no premium.
2) Doctrine of pari delicto.
3) Frustration and impossibility.
4) Non-disclosure of fact or mistake.
5) Fraud by the insurer.
6) Ignorance of the fact.
7) Fraud played by the insurance agent.
8) Cancellation/rescission.
9) Ultra vires the insurance company.
10) Surrender of the policy.
Principles  of  insurance