The new pathways to purchase in  the world of networked consumers Henry Assael  - lecture at NYU October 6,  2011 Lee Rainie: Director, Pew Internet Project Email:  [email_address] Twitter: @Lrainie
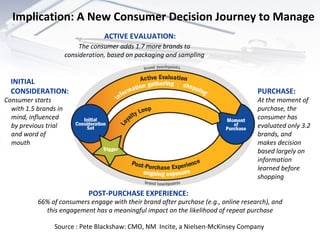
Implication: A New Consumer Decision Journey to Manage INITIAL CONSIDERATION: PURCHASE: POST-PURCHASE EXPERIENCE: ACTIVE EVALUATION: Consumer starts with 1.5 brands in mind, influenced by previous trial and word of mouth At the moment of purchase, the consumer has evaluated only 3.2 brands, and makes decision based largely on information learned before shopping  66% of consumers engage with their brand after purchase (e.g., online research), and this engagement has a meaningful impact on the likelihood of repeat purchase The consumer adds 1.7 more brands to consideration, based on packaging and sampling Source : Pete Blackshaw: CMO, NM  Incite, a Nielsen-McKinsey Company
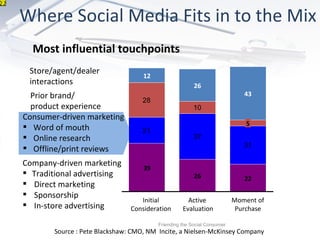
Where Social Media Fits in to the Mix  3 22 Friending the Social Consumer Most influential touchpoints Company-driven marketing  Traditional advertising Direct marketing Sponsorship In-store advertising Consumer-driven marketing Word of mouth Online research Offline/print reviews Prior brand/ product experience Store/agent/dealer  interactions Moment of Purchase 22 5 43 Active Evaluation 26 26 Initial Consideration 39 12 Source : Pete Blackshaw: CMO, NM  Incite, a Nielsen-McKinsey Company
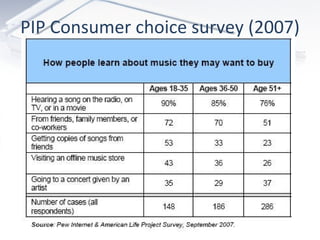
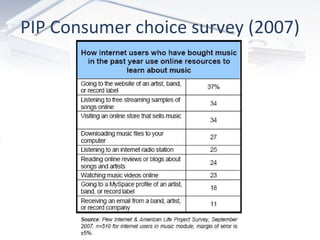
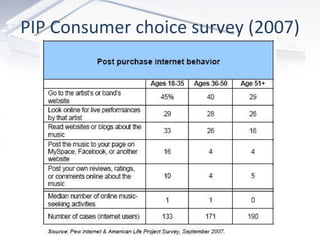
Your experiences -1  Smaller scale / impulse buys Piece of music  App  Something off the shelf Pew Internet findings in 2007 among music buyers: 83% find out about music from the radio, TV, or in a movie; 64% find out about music from family, friends, or co-workers.
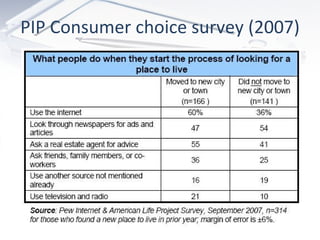
PIP Consumer choice survey (2007)
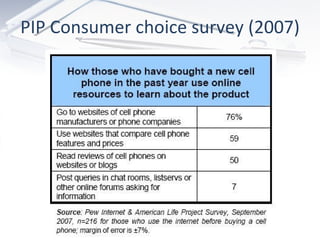
Your experiences -2  Mid-scale products Cell phone Clothes Pew Internet findings in 2007 among cell buyers: 59% ask an expert of salesperson for advice; 46% go to one or more cell phone stores.
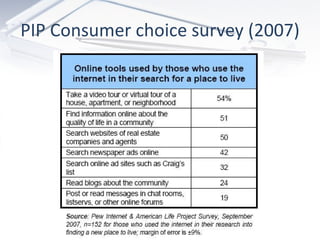
PIP Consumer choice survey (2007)
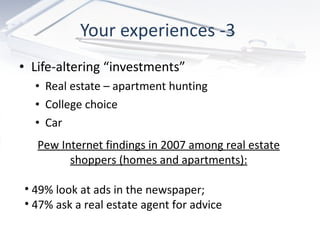
Your experiences -3  Life-altering “investments” Real estate – apartment hunting College choice Car  Pew Internet findings in 2007 among real estate shoppers (homes and apartments): 49% look at ads in the newspaper; 47% ask a real estate agent for advice
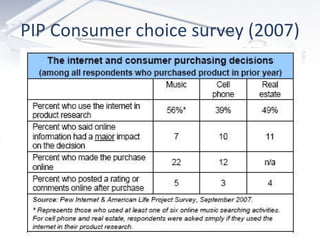
PIP Consumer choice survey (2007)
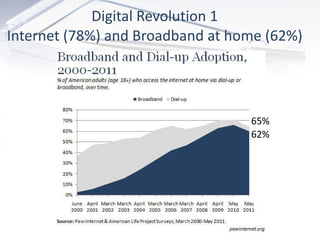
Digital Revolution 1 Internet (78%) and Broadband at home (62%) 65%  62%
Networked creators among internet users 65% are social networking site users 55% share photos 37% contribute rankings and ratings 33% create content tags  30% share personal creations  26% post comments on sites and blogs 15% have personal website 15% are content remixers  14% are bloggers 13% use Twitter 6% location services – 9% allow location awareness from social media – 23% maps etc.
Impact on shopping  Shopping is a “full contact” sport throughout its phases: Research phase 60% of all Americans do research online about products Purchase phase 55% of all Americans made e-purchases; 51% travel reservations After-purchase phase 37% rankings and ratings; another quarter describe their shopping experiences
So what for brands? The Bermuda Triangle Markets are fractured Marketplace is roiled Metrics haven’t kept pace Too much noise Brands are co-owned by advocates /acolytes Best of times - sanctuaries Worst of times - #fail
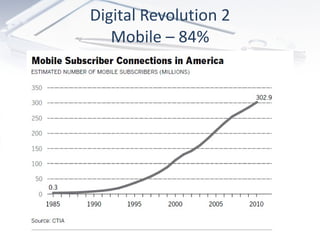
Digital Revolution 2 Mobile – 84%
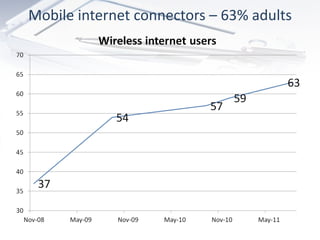
Mobile internet connectors – 63% adults
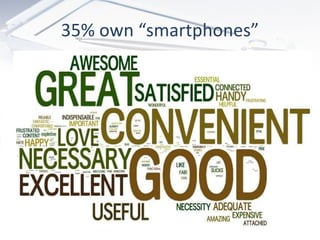
35% own “smartphones”
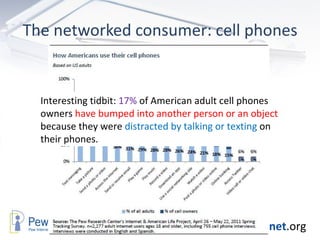
The networked consumer: cell phones Interesting tidbit:  17%  of American adult cell phones owners  have bumped into another person or an object  because they were  distracted by talking or texting  on their phones.
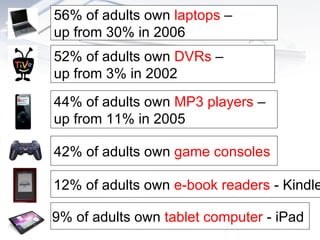
56% of adults own  laptops  –  up from 30% in 2006 44% of adults own  MP3 players  –  up from 11% in 2005 52% of adults own  DVRs  –  up from 3% in 2002 42% of adults own  game consoles 12% of adults own  e-book readers  - Kindle 9% of adults own  tablet computer  - iPad
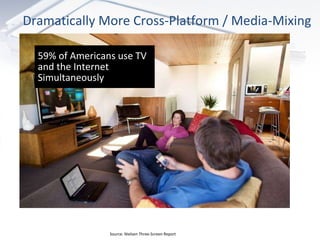
59% of Americans use TV and the Internet Simultaneously Dramatically More Cross-Platform / Media-Mixing Source: Nielsen Three-Screen Report
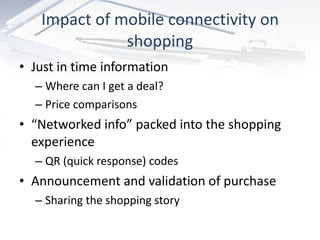
Impact of mobile connectivity on shopping Just in time information  Where can I get a deal? Price comparisons “ Networked info” packed into the shopping experience QR (quick response) codes Announcement and validation of purchase Sharing the shopping story
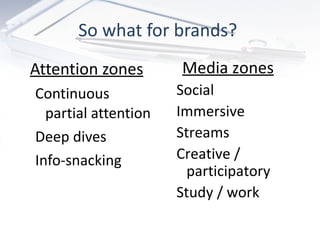
So what for brands?  Attention zones Continuous partial attention Deep dives Info-snacking Media zones Social Immersive Streams Creative / participatory Study / work
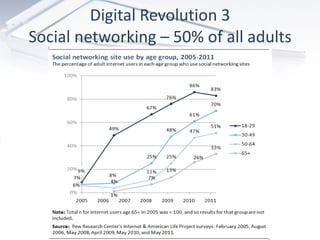
Digital Revolution 3 Social networking – 50% of all adults
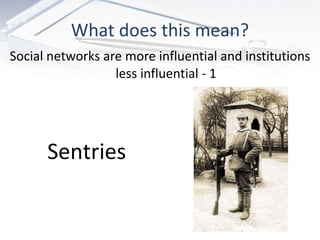
What does this mean? Social networks are more influential and institutions less influential - 1 Sentries
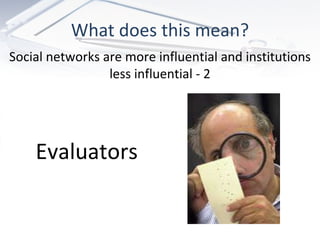
What does this mean? Evaluators Social networks are more influential and institutions less influential - 2
What does this mean? Social networks are more influential and institutions less influential - 3 Audience = New media are the new neighborhood
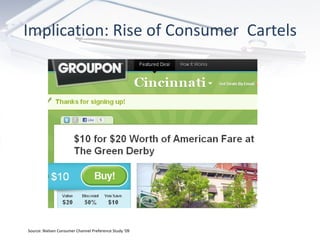
Impact of SNS on shopping Purchasing can be group activity “ Consumer cartels” arise (Groupon, Living Social)
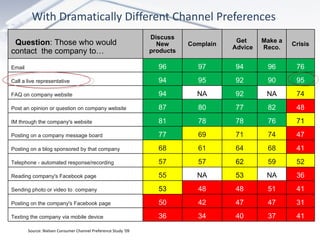
With Dramatically Different Channel Preferences Source: Nielsen Consumer Channel Preference Study ‘09    Question : Those who would contact  the company to… Discuss New products Complain Get Advice Make a Reco. Crisis Email 96 97 94 96 76 Call a live representative 94 95 92 90 95 FAQ on company website 94 NA 92 NA 74 Post an opinion or question on company website 87 80 77 82 48 IM through the company's website 81 78 78 76 71 Posting on a company message board 77 69 71 74 47 Posting on a blog sponsored by that company 68 61 64 68 41 Telephone - automated response/recording 57 57 62 59 52 Reading company's Facebook page 55 NA 53 NA 36 Sending photo or video to  company 53 48 48 51 41 Posting on the company's Facebook page 50 42 47 47 31 Texting the company via mobile device 36 34 40 37 41
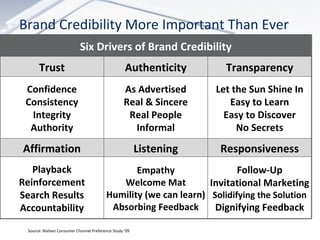
24 Brand Credibility More Important Than Ever Source: Nielsen Consumer Channel Preference Study ‘09 Six Drivers of Brand Credibility Trust Authenticity Transparency Confidence Consistency Integrity Authority As Advertised Real & Sincere Real People Informal Let the Sun Shine In Easy to Learn Easy to Discover No Secrets Affirmation Listening Responsiveness Playback Reinforcement Search Results Accountability Empathy Welcome Mat Humility (we can learn) Absorbing Feedback Follow-Up Invitational Marketing Solidifying the Solution Dignifying Feedback
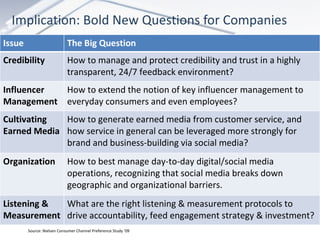
Implication: Bold New Questions for Companies Source: Nielsen Consumer Channel Preference Study ‘09 Issue The Big Question Credibility How to manage and protect credibility and trust in a highly transparent, 24/7 feedback environment? Influencer Management How to extend the notion of key influencer management to everyday consumers and even employees? Cultivating Earned Media How to generate earned media from customer service, and how service in general can be leveraged more strongly for brand and business-building via social media? Organization How to best manage day-to-day digital/social media operations, recognizing that social media breaks down geographic and organizational barriers.  Listening & Measurement What are the right listening & measurement protocols to  drive accountability, feed engagement strategy & investment?
Social Commerce Ecosystems  Implication: Death (or erosion) of Web Sites
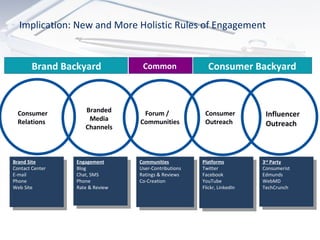
Consumer Relations Branded Media Channels Forum / Communities Consumer Outreach Influencer Outreach Brand Backyard Consumer Backyard Common Brand Site Contact Center E-mail  Phone Web Site Engagement Blog Chat, SMS Phone Rate & Review Communities User-Contributions  Ratings & Reviews  Co-Creation Platforms Twitter Facebook YouTube Flickr, LinkedIn 3 rd  Party Consumerist Edmunds WebMD TechCrunch 43 Implication: New and More Holistic Rules of Engagement
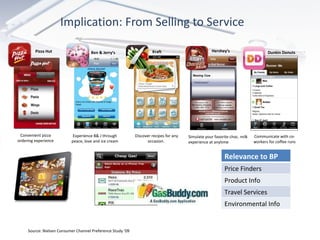
Implication: From Selling to Service  Pizza Hut Convenient pizza ordering experience Experience B& J through peace, love and ice cream Discover recipes for any occasion.  Communicate with co-workers for coffee runs Simulate your favorite choc. milk experience at anytime Ben & Jerry’s Kraft Hershey’s Dunkin Donuts Source: Nielsen Consumer Channel Preference Study ‘09 Relevance to BP Price Finders Product Info Travel Services Environmental Info
Implication: Rise of Consumer  Cartels Source: Nielsen Consumer Channel Preference Study ‘09
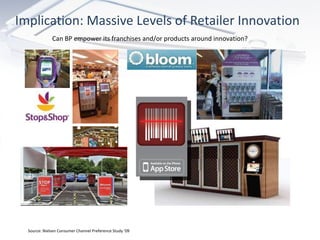
Implication: Massive Levels of Retailer Innovation Source:  Company websites; Progressive Grocer &  Pittsburgh Post-Gazette Can BP empower its franchises and/or products around innovation? Source: Nielsen Consumer Channel Preference Study ‘09
Implication: The Rise of Real-Time Source: Nielsen Consumer Channel Preference Study ‘09 24/7 Real-Time War Room 24/7 Engagement  Listening Beyond Borders All aspects of integrated, brand-monitored social media Deliberate effort to shape and manage messaging Listening tools cover multiple languages & regions
Looking Ahead Source: Nielsen
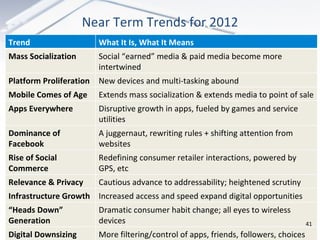
What’s Ahead / Next? Near Term Trends for 2012 Trend What It Is, What It Means Mass Socialization Social “earned” media & paid media become more intertwined Platform Proliferation New devices and multi-tasking abound Mobile Comes of Age Extends mass socialization & extends media to point of sale Apps Everywhere Disruptive growth in apps, fueled by games and service utilities Dominance of Facebook A juggernaut, rewriting rules + shifting attention from websites Rise of Social Commerce Redefining consumer retailer interactions, powered by GPS, etc Relevance & Privacy Cautious advance to addressability; heightened scrutiny Infrastructure Growth Increased access and speed expand digital opportunities “ Heads Down” Generation  Dramatic consumer habit change; all eyes to wireless devices  Digital Downsizing More filtering/control of apps, friends, followers, choices
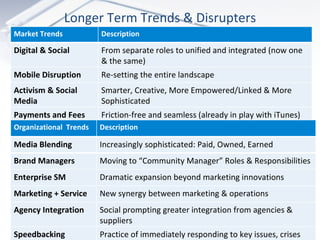
What’s Ahead / Next? Longer Term Trends & Disrupters Market Trends Description Digital & Social  From separate roles to unified and integrated (now one & the same) Mobile Disruption Re-setting the entire landscape Activism & Social Media Smarter, Creative, More Empowered/Linked & More Sophisticated  Payments and Fees Friction-free and seamless (already in play with iTunes) Globalization of Social  Creating huge opportunities….and huge operational challenges  Organizational  Trends Description Media Blending Increasingly sophisticated: Paid, Owned, Earned  Brand Managers Moving to “Community Manager” Roles & Responsibilities Enterprise SM Dramatic expansion beyond marketing innovations Marketing + Service New synergy between marketing & operations  Agency Integration Social prompting greater integration from agencies & suppliers  Speedbacking Practice of immediately responding to key issues, crises
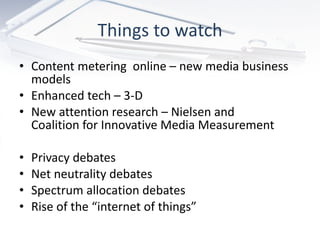
Things to watch Content metering  online – new media business models Enhanced tech – 3-D New attention research – Nielsen and  Coalition for Innovative Media Measurement Privacy debates Net neutrality debates  Spectrum allocation debates  Rise of the “internet of things”
Thank you!