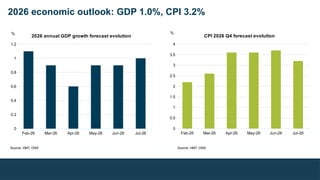
Office for National Statistics (ONS) Economic Forum: 20 July 2026
July’s Economic Forum showcased the latest economic and social developments from a wide range of analytical topics, including artificial intelligence in UK businesses and family spending in the UK.
Office for National Statistics (ONS) Economic Forum: 20 July 2026
1.
20 July 2026
Welcometo the
ONS Economic Forum
Chair – Sumit Dey-Chowdhury
Deputy Director
Economic and Microdata Insights
Office for National Statistics
#ONSEconForum
2.
Agenda
09:30 Welcome andintroduction
Sumit Dey-Chowdhury, Deputy Director, Economic and Microdata Insights, Office for National Statistics
09:35 State of the UK economy
Amy Ditchfield, Office for National Statistics
09:50 AI in UK businesses
Alexander Hewitt, Office for National Statistics
10:00 Family spending in the UK
Lee Colvin, Office for National Statistics
10:10 Question and Answer
10:25 Closing remarks
Sumit Dey-Chowdhury, Deputy Director, Economic and Microdata Insights, Office for National Statistics
#ONSEconForum
3.
State of theUK
Economy
Amy Ditchfield
Head of Economic Analysis – Prices and GDP
Office for National Statistics
#ONSEconForum
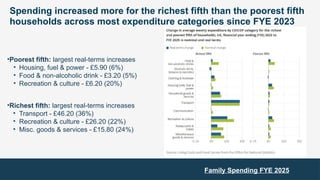
4.
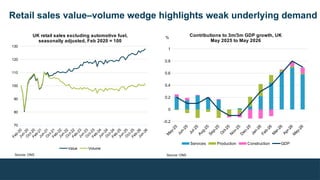
Retail sales value–volumewedge highlights weak underlying demand
Source: ONS
Feb-20
Jun-20
O
ct-20
Feb-21
Jun-21
O
ct-21
Feb-22
Jun-22
O
ct-22
Feb-23
Jun-23
O
ct-23
Feb-24
Jun-24
O
ct-24
Feb-25
Jun-25
O
ct-25
Feb-26
Jun-26
70
80
90
100
110
120
130
UK retail sales excluding automotive fuel,
seasonally adjusted, Feb 2020 = 100
Value Volume
Source: ONS
M
ay-25
Jun-25
Jul-25
Aug-25
Sep-25
O
ct-25
N
ov-25
D
ec-25
Jan-26
Feb-26
M
ar-26
Apr-26
M
ay-26
-0.2
0
0.2
0.4
0.6
0.8
1
Contributions to 3m/3m GDP growth, UK
May 2025 to May 2026
Services Production Construction GDP
%
5.
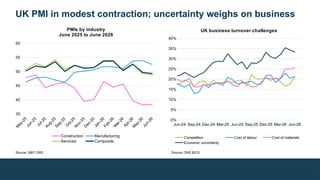
UK PMI inmodest contraction; uncertainty weighs on business
M
ay-25
Jun-25
Jul-25
Aug-25
Sep-25
O
ct-25
N
ov-25
D
ec-25
Jan-26
Feb-26
M
ar-26
Apr-26
M
ay-26
Jun-26
35
40
45
50
55
60
PMIs by industry
June 2025 to June 2026
Construction Manufacturing
Services Composite
Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 Sep-25 Dec-25 Mar-26 Jun-26
0%
5%
10%
15%
20%
25%
30%
35%
40%
UK business turnover challenges
Competition Cost of labour Cost of materials
Economic uncertainty
Source: ONS BICS
Source: S&P, ONS
6.
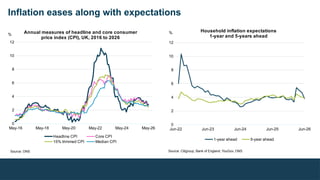
Inflation eases alongwith expectations
Source: ONS
May-16 May-18 May-20 May-22 May-24 May-26
0
2
4
6
8
10
12
Annual measures of headline and core consumer
price index (CPI), UK, 2016 to 2026
Headline CPI Core CPI
15% trimmed CPI Median CPI
%
Jun-22 Jun-23 Jun-24 Jun-25 Jun-26
0
2
4
6
8
10
12
Household inflation expectations
1-year and 5-years ahead
1-year ahead 5-year ahead
%
Source: Citigroup, Bank of England, YouGov, ONS
7.
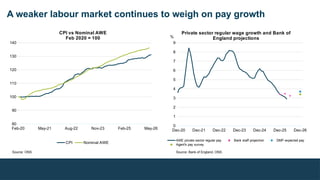
A weaker labourmarket continues to weigh on pay growth
Feb-20 May-21 Aug-22 Nov-23 Feb-25 May-26
80
90
100
110
120
130
140
CPI vs Nominal AWE
Feb 2020 = 100
CPI Nominal AWE
Dec-20 Dec-21 Dec-22 Dec-23 Dec-24 Dec-25 Dec-26
0
1
2
3
4
5
6
7
8
9
Private sector regular wage growth and Bank of
England projections
AWE private sector regular pay Bank staff projection DMP expected pay
Agent's pay survey
%
Source: ONS Source: Bank of England, ONS
8.
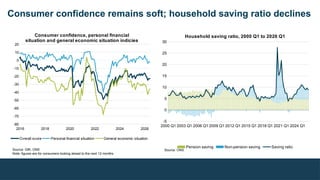
Consumer confidence remainssoft; household saving ratio declines
Source: GfK, ONS
Note: figures are for consumers looking ahead to the next 12 months
2016 2018 2020 2022 2024 2026
-80
-70
-60
-50
-40
-30
-20
-10
0
10
20
Consumer confidence, personal financial
situation and general economic situation indicies
Overall score Personal financial situation General economic situation
2000 Q1 2003 Q1 2006 Q1 2009 Q1 2012 Q1 2015 Q1 2018 Q1 2021 Q1 2024 Q1
-5
0
5
10
15
20
25
30
Household saving ratio, 2000 Q1 to 2026 Q1
Pension saving Non-pension saving Saving ratio
Source: ONS
9.
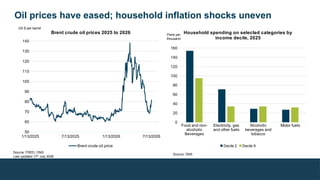
Oil prices haveeased; household inflation shocks uneven
1/13/2025 7/13/2025 1/13/2026 7/13/2026
50
60
70
80
90
100
110
120
130
140
Brent crude oil prices 2025 to 2026
Brent crude oil price
US $ per barrel
Food and non-
alcoholic
Beverages
Electricity, gas
and other fuels
Alcoholic
beverages and
tobacco
Motor fuels
0
20
40
60
80
100
120
140
160
Household spending on selected categories by
income decile, 2025
Decile 2 Decile 9
Source: ONS
Parts per
thousand
Source: FRED, ONS
Last updated 17th
July 2026
10.
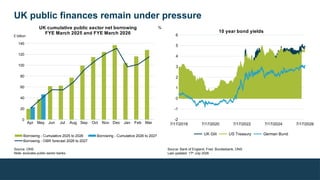
UK public financesremain under pressure
Apr May Jun Jul Aug Sep Oct Nov Dec Jan Feb Mar
0
20
40
60
80
100
120
140
UK cumulative public sector net borrowing
FYE March 2025 and FYE March 2026
Borrowing - Cumulative 2025 to 2026 Borrowing - Cumulative 2026 to 2027
Borrowing - OBR forecast 2026 to 2027
£ billion
Source: Bank of England, Fred, Bundesbank, ONS
Last updated: 17th
July 2026
%
7/17/2018 7/17/2020 7/17/2022 7/17/2024 7/17/2026
-2
-1
0
1
2
3
4
5
6
10 year bond yields
UK Gilt US Treasury German Bund
Source: ONS
Note: excludes public sector banks
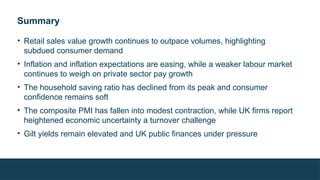
Summary
• Retail salesvalue growth continues to outpace volumes, highlighting
subdued consumer demand
• Inflation and inflation expectations are easing, while a weaker labour market
continues to weigh on private sector pay growth
• The household saving ratio has declined from its peak and consumer
confidence remains soft
• The composite PMI has fallen into modest contraction, while UK firms report
heightened economic uncertainty a turnover challenge
• Gilt yields remain elevated and UK public finances under pressure
Background
• Growing AIuse across UK businesses has raised interest in adoption
patterns, business applications, barriers to uptake, and impacts on business
activity and the labour market.
• Measurement of AI is an evolving area in the UK and internationally.
This analysis focuses on three questions:
1. How widespread is AI adoption among businesses?
2. How are businesses using AI in practice, and what impacts is AI
beginning to have on business activity and the labour market?
3. What factors are preventing or delaying AI adoption, and how are
businesses responding to AI skills needs?
15.
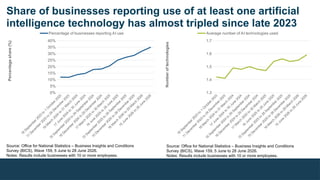
Share of businessesreporting use of at least one artificial
intelligence technology has almost tripled since late 2023
18
Septem
ber 2023
to
1
O
ctober 2023
11
Decem
ber 2023
to
24
Decem
ber 2023
18
M
arch
2024
to
31
M
arch
2024
17
June
2024
to
30
June
2024
16
Septem
ber 2024
to
29
Septem
ber 2024
16
Decem
ber 2024
to
29
Decem
ber 2024
17
M
arch
2025
to
30
M
arch
2025
16
June
2025
to
29
June
2025
15
Septem
ber 2025
to
28
Septem
ber 2025
15
Decem
ber 2025
to
28
Decem
ber 2025
16
M
arch
2026
to
29
M
arch
2026
15
June
2026
to
28
June
2026
0%
5%
10%
15%
20%
25%
30%
35%
40%
Percentage of businesses reporting AI use
Percentage
share
(%)
18
Septem
ber 2023
to
1
O
ctober 2023
11
Decem
ber 2023
to
24
Decem
ber 2023
18
M
arch
2024
to
31
M
arch
2024
17
June
2024
to
30
June
2024
16
Septem
ber 2024
to
29
Septem
ber 2024
16
Decem
ber 2024
to
29
Decem
ber 2024
17
M
arch
2025
to
30
M
arch
2025
16
June
2025
to
29
June
2025
15
Septem
ber 2025
to
28
Septem
ber 2025
15
Decem
ber 2025
to
28
Decem
ber 2025
16
M
arch
2026
to
29
M
arch
2026
15
June
2026
to
28
June
2026
1.3
1.4
1.5
1.6
1.7
Average number of AI technologies used
Number
of
technologies
Source: Office for National Statistics – Business Insights and Conditions
Survey (BICS), Wave 159, 5 June to 28 June 2026.
Notes: Results include businesses with 10 or more employees.
Source: Office for National Statistics – Business Insights and Conditions
Survey (BICS), Wave 159, 5 June to 28 June 2026.
Notes: Results include businesses with 10 or more employees.
16.
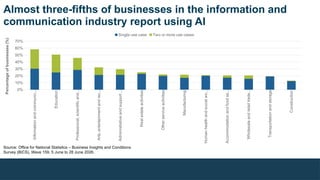
Almost three-fifths ofbusinesses in the information and
communication industry report using AI
Information
and
communic...
Education
Professional,
scientific
and...
Arts,
entertainment
and
rec...
Administrative
and
support
...
Real
estate
activities
Other
service
activities
Manufacturing
Human
health
and
social
wo...
Accommodation
and
food
se...
Wholesale
and
retail
trade...
Transportation
and
storage
Construction
0%
10%
20%
30%
40%
50%
60%
70%
Single use case Two or more use cases
Percentage
of
businesses
(%)
Source: Office for National Statistics – Business Insights and Conditions
Survey (BICS), Wave 159, 5 June to 28 June 2026.
17.
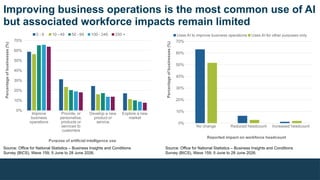
Improving business operationsis the most common use of AI
but associated workforce impacts remain limited
Improve
business
operations
Provide, or
personalise,
products or
services to
customers
Develop a new
product or
service
Explore a new
market
0%
10%
20%
30%
40%
50%
60%
70%
0 - 9 10 - 49 50 - 99 100 - 249 250 +
Purpose of artificial intelligence use
Percentage
of
businesses
(%)
No change Reduced headcount Increased headcount
0%
10%
20%
30%
40%
50%
60%
70%
Uses AI to improve business operations Uses AI for other purposes only
Reported impact on workforce headcount
Percentage
of
businesses
(%)
Source: Office for National Statistics – Business Insights and Conditions
Survey (BICS), Wave 159, 5 June to 28 June 2026.
Source: Office for National Statistics – Business Insights and Conditions
Survey (BICS), Wave 159, 5 June to 28 June 2026.
18.
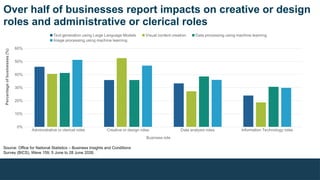
Over half ofbusinesses report impacts on creative or design
roles and administrative or clerical roles
Administrative or clerical roles Creative or design roles Data analysis roles Information Technology roles
0%
10%
20%
30%
40%
50%
60%
Text generation using Large Language Models Visual content creation Data processing using machine learning
Image processing using machine learning
Business role
Percentage
of
businesses
(%)
Source: Office for National Statistics – Business Insights and Conditions
Survey (BICS), Wave 159, 5 June to 28 June 2026.
19.
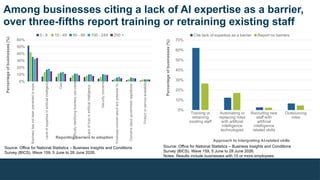
Among businesses citinga lack of AI expertise as a barrier,
over three-fifths report training or retraining existing staff
Business
has
not
been
prevented
or
expe...
Level
of
expertise
in
artificial
intelligence
Cost
Difficulty
identifying
business
use
cases
Lack
of
trust
in
artificial
intelligence
...
Security
concerns
Employee
concern
about
any
potential
im...
Concerns
about
government
regulations...
Product
or
service
availability
0%
10%
20%
30%
40%
50%
60%
0 - 9 10 - 49 50 - 99 100 - 249 250 +
Reporting barriers to adoption
Percentage
of
businesses
(%)
Training or
retraining
existing staff
Automating or
replacing roles
with artificial
intelligence
technologies
Recruiting new
staff with
artificial
intelligence
related skills
Outsourcing
roles
0%
10%
20%
30%
40%
50%
60%
70%
Cite lack of expertise as a barrier Report no barriers
Approach to intergrating AI-related skills
Percentage
of
businesses
(%)
Source: Office for National Statistics – Business Insights and Conditions
Survey (BICS), Wave 159, 5 June to 28 June 2026.
Source: Office for National Statistics – Business Insights and Conditions
Survey (BICS), Wave 159, 5 June to 28 June 2026.
Notes: Results include businesses with 10 or more employees.
20.
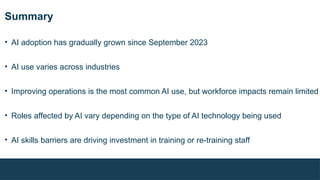
Summary
• AI adoptionhas gradually grown since September 2023
• AI use varies across industries
• Improving operations is the most common AI use, but workforce impacts remain limited
• Roles affected by AI vary depending on the type of AI technology being used
• AI skills barriers are driving investment in training or re-training staff
21.
Family Spending
in theUK
Lee Colvin
Head of Household Income & Expenditure Analysis
Household Resilience Division
22.
Recently at ONS...
Publications
•Family Spending FYE 2025
• OSR Compliance Review of Family
Spending Statistics
• ONS surveys and economic statistics
improvement plan quarterly progress
update provided overview of Household
Finance Recovery Plans
Survey developments
• Ongoing quality work to better align
accredited household income and
expenditure statistics
Processes and methods
• In FYE 2025, equivalisation
was updated in Family
Spending to use the modified
OECD two-person reference
household instead of a single-
person approach
23.
Looking ahead..
Survey developments
•Implementation of OSR
recommendations
• Focus on delivery of 3-year
quality recovery plan
Processes
• Continuing to improve
production pipelines
• Improving cross-cutting insights
for household income and
expenditure
Statistical publications
• Family Spending in the UK
FYE 26, Spring 2027
• Aiming to bring closer to the
12-month target between data
collection and publication, as
recommended by OSR
Stakeholder engagement
• Stakeholder Engagement
Strategy Published
• Engagement mechanisms for
income and expenditure under
review
24.
Office for StatisticsRegulation Review
• Compliance review of Family Spending statistics published 10 February 2026
• Recognised the challenges we face in our data collection in the Living Costs and Food
Survey (the Family Spending data source) and acknowledged the range of interventions and
developments we have in place
• Conclusions:
“While there have been growing issues around achieved sample size and timeliness,
considering the positive user feedback, and the current and planned improvements to the
survey, these statistics remain of sufficient value and quality to meet users’ needs.”
• Confirmed Family Spending statistics continue to comply with the Code of Practice for
Statistics and can continue to be published as accredited official statistics.
• Three recommendations made on variable continuity information, timeliness and quality
reporting.
Family Spending inthe UK FYE 2025: Overview
Highlights from ONS Family Spending publication FYE 2025
• What are households spending the most on?
• How is expenditure changing across the distribution?
• Compared with FYE 2023 how has the spending between the top and bottom fifth of
households changed?
Unless otherwise stated, both absolute and relative year-on-year changes in spending presented in this
bulletin are adjusted for inflation and are presented in real terms.
Achieved sample approximately 5000 households
27.
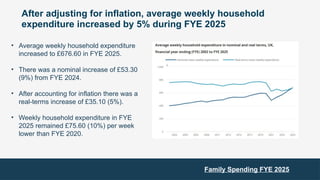
After adjusting forinflation, average weekly household
expenditure increased by 5% during FYE 2025
• Average weekly household expenditure
increased to £676.60 in FYE 2025.
• There was a nominal increase of £53.30
(9%) from FYE 2024.
• After accounting for inflation there was a
real-terms increase of £35.10 (5%).
• Weekly household expenditure in FYE
2025 remained £75.60 (10%) per week
lower than FYE 2020.
Family Spending FYE 2025
28.
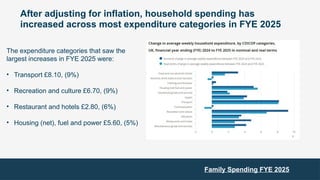
After adjusting forinflation, household spending has
increased across most expenditure categories in FYE 2025
The expenditure categories that saw the
largest increases in FYE 2025 were:
• Transport £8.10, (9%)
• Recreation and culture £6.70, (9%)
• Restaurant and hotels £2.80, (6%)
• Housing (net), fuel and power £5.60, (5%)
Family Spending FYE 2025
29.
Housing (net), fueland power, and transport continued to
account for the highest household spending in FYE 2025
The categories had the largest share of total
weekly expenditure in FYE 2025 were:
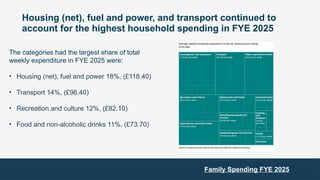
• Housing (net), fuel and power 18%, (£118.40)
• Transport 14%, (£96.40)
• Recreation and culture 12%, (£82.10)
• Food and non-alcoholic drinks 11%, (£73.70)
Family Spending FYE 2025
30.
The difference inreal term weekly expenditure between the
richest and poorest fifth of households has widened in FYE 2025
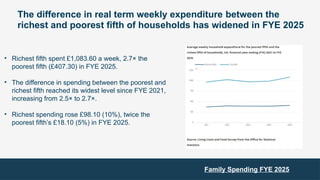
• Richest fifth spent £1,083.60 a week, 2.7× the
poorest fifth (£407.30) in FYE 2025.
• The difference in spending between the poorest and
richest fifth reached its widest level since FYE 2021,
increasing from 2.5× to 2.7×.
• Richest spending rose £98.10 (10%), twice the
poorest fifth’s £18.10 (5%) in FYE 2025.
Family Spending FYE 2025
31.
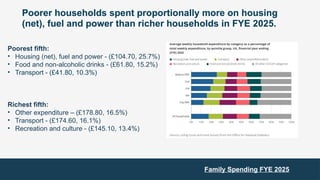
Poorer households spentproportionally more on housing
(net), fuel and power than richer households in FYE 2025.
Poorest fifth:
• Housing (net), fuel and power - (£104.70, 25.7%)
• Food and non-alcoholic drinks - (£61.80, 15.2%)
• Transport - (£41.80, 10.3%)
Richest fifth:
• Other expenditure – (£178.80, 16.5%)
• Transport - (£174.60, 16.1%)
• Recreation and culture - (£145.10, 13.4%)
Family Spending FYE 2025
32.
How has spendingpatterns changed since FYE 2023?
• In early 2021 UK inflation rates began increasing, as the global economy reopened from
the COVID-19 pandemic; by October 2022 supply chain disruptions and surging energy
costs pushed CPI and CPIH inflation rates to levels last seen over 40 years ago
• Analysis for the FYE 2025 Family spending publication, showed that household spending
patterns had changed since the FYE 2023.
• Since the FYE 2023 inflation peak, spending shifted unevenly between the poorest and
richest fifths.
33.
Spending increased morefor the richest fifth than the poorest fifth
households across most expenditure categories since FYE 2023
•Poorest fifth: largest real-terms increases
• Housing, fuel & power - £5.90 (6%)
• Food & non-alcoholic drink - £3.20 (5%)
• Recreation & culture - £6.20 (20%)
•Richest fifth: largest real-terms increases
• Transport - £46.20 (36%)
• Recreation & culture - £26.20 (22%)
• Misc. goods & services - £15.80 (24%)
Family Spending FYE 2025
34.
Thank you foryour time.
Contact details if you have any questions or queries:
Family.spending@ons.gov.uk
ONS economic statistics:our latest progress
update
We published our third quarterly update alongside an accompanying blog on the improvement work
underway in the ONS for surveys and economic statistics on the 15 July.
The update reflects refined priorities, reset milestones and clarity about where activity must wait until
constraints are resolved.
Key progress includes:
• Early data from the Transformed Labour Force Survey (TLFS), following the implementation in April
of the final elements of agreed design improvements, indicates improved response rates, particularly
in later waves, and fewer partial returns. This sets the scene for an assessment that we will publish
in August of our readiness to transition to the TLFS as the headline measure for labour market
statistics in 2027.
• The Statistical Business Register (SBR) has moved to a stronger, iterative delivery model, with early
benefits already being deployed through enhanced search capability within the ONS. The new
approach releases value to users earlier and allows us to gather feedback.
37.
ONS economic statistics:our latest progress
update – continued
Key progress includes:
• In National Accounts, the IMF has accredited UK statistics as meeting Special Data Dissemination
Standard Plus – their highest tier internationally – strengthening the transparency and comparability
of our financial statistics
• Business Enterprise Research and Development statistics are now accredited by the Office for
Statistics Regulation as official statistics.
• We have published a broader information package on how we assess GDP for residual seasonality
and completed the move of the remaining Annual Survey of Hours and Earnings to digital-first
collection, reducing operational cost and risk, and speeding up data processing.
38.
ONS Business EngagementSurvey
On the 17 July we published the findings from our recent business surveys consultation, which explored
organisations’ experiences of completing ONS business surveys and identified opportunities to
strengthen engagement and improve the support available to businesses.
The feedback highlighted the importance of clear communications, responsive support and continued
efforts to reduce the burden of survey completion, while also recognising positive progress in areas
such as service improvements, survey modernisation and data quality.
Alongside insight gathered through our regular engagement channels, these findings will help shape
ongoing improvements through our Business Surveys Transformation Programme.
39.
Upcoming ONS economicanalysis
• 20 July – AI in UK Businesses
• 21 July – Labour Market Theme Day
• 22 July – Prices Theme Day
• 24 July – Retail sales, Great Britain: June 2026; UK trade in services by partner country: January to March
2026; UK trade, quarterly goods and services: January to March 2026; UK manufacturers' sales by product
• 29 July – Workless households for regions across the UK: 2025
All information on upcoming analysis can be found via the ONS website
40.
Upcoming events
22 July2026 – Inflation day stakeholder briefing
Please join us our stakeholder briefing session to coincide with the release of June’s inflation data.
These 30-minute sessions will take place on the day of publication, giving you the chance to ask questions
about the latest published data, seek clarification on any points, and explore anything you'd like to understand in
more depth. To make the most of the time available, we ask that questions focus on the published data and
findings rather than methodology.
All our events can be found via eventbrite.co.uk/o/the-office-for-national-statistics-33407052803
41.
Thank you forattending the
ONS Economic Forum
You can keep up to date on all upcoming events on our
Eventbrite page.
If you have any feedback please email economic.engagement@ons.gov.uk