IDENTITY, PAYMENTS &
DATA EMPOWERMENT
Nandan Nilekani, 2019
1 2 3The Three
Challenges
of Financial
Inclusion
Access Retention
Bring population
in the financial system
Keep them
in the system
Data sharing without
compromising privacy
Data
Empowerment
2
1
Part 1
Solving the
Access
Challenge
Access
Bring population
in the financial system
3
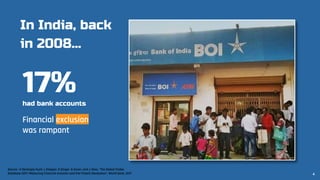
In India, back
in 2008…
Financial exclusion
was rampant
17%had bank accounts
Source : A Demirgüç-Kunt, L Klapper, D Singer, S Ansar, and J Hess, “The Global Findex
Database 2017: Measuring Financial Inclusion and the Fintech Revolution”, World Bank, 2017 4
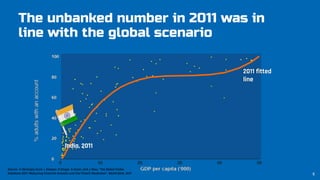
The unbanked number in 2011 was in
line with the global scenario
2011 fitted
line
India, 2011
Source : A Demirgüç-Kunt, L Klapper, D Singer, S Ansar, and J Hess, “The Global Findex
Database 2017: Measuring Financial Inclusion and the Fintech Revolution”, World Bank, 2017 5
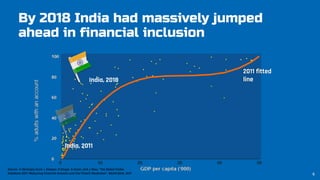
By 2018 India had massively jumped
ahead in financial inclusion
2011 fitted
lineIndia, 2018
India, 2011
Source : A Demirgüç-Kunt, L Klapper, D Singer, S Ansar, and J Hess, “The Global Findex
Database 2017: Measuring Financial Inclusion and the Fintech Revolution”, World Bank, 2017 6
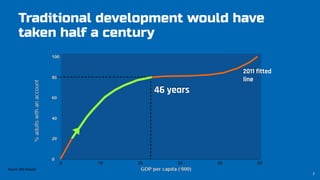
Traditional development would have
taken half a century
46 years
2011 fitted
line
Source : BIS Analysis
7
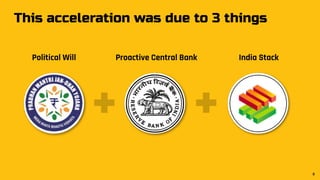
This acceleration was due to 3 things
India StackPolitical Will Proactive Central Bank
8
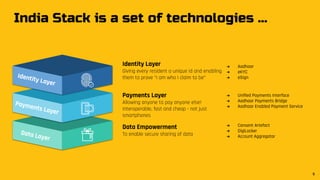
India Stack is a set of technologies ...
Identity Layer
Giving every resident a unique id and enabling
them to prove “I am who I claim to be”
Payments Layer
Allowing anyone to pay anyone else!
interoperable, fast and cheap - not just
smartphones
Data Empowerment
To enable secure sharing of data
➔ Unified Payments Interface
➔ Aadhaar Payments Bridge
➔ Aadhaar Enabled Payment Service
➔ Aadhaar
➔ eKYC
➔ eSign
➔ Consent Artefact
➔ DigiLocker
➔ Account Aggregator
9
Identity Layer
Payments Layer
Data Layer
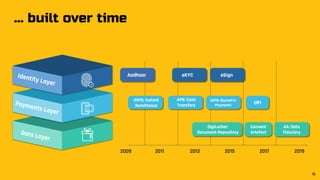
… built over time
AA: Data
Fiduciary
DigiLocker:
Document Repository
Consent
Artefact
2009 2011 2013 2015 2017 2019
Aadhaar eKYC eSign
IMPS: Instant
Remittance
UPI
APB: Cash
Transfers
AEPS: Biometric
Payments
10
Identity Layer
Payments Layer
Data Layer
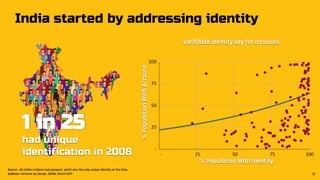
India started by addressing identity
Verifiable identity key for inclusion
1 in 25
had unique
identification in 2008
Source : 40 million Indians had passport, which was the only unique identity at the time.
Aadhaar: Inclusive by Design, GSMA, March 2017
% Population With Identity
%PopulationWithAccount
11
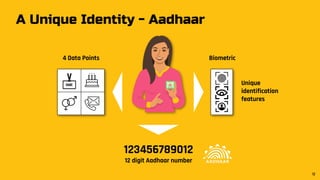
Unique
identification
features
Biometric
123456789012
12 digit Aadhaar number
4 Data Points
A Unique Identity - Aadhaar
12
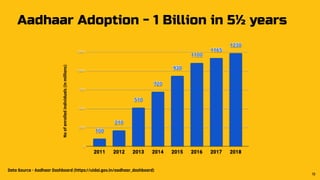
Aadhaar Adoption - 1 Billion in 5½ years
Data Source - Aadhaar Dashboard (https://uidai.gov.in/aadhaar_dashboard)
Noofenrolledindividuals(inmillions)
13
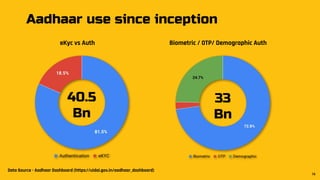
Aadhaar use since inception
eKyc vs Auth Biometric / OTP/ Demographic Auth
Data Source - Aadhaar Dashboard (https://uidai.gov.in/aadhaar_dashboard)
40.5
Bn
33
Bn
14
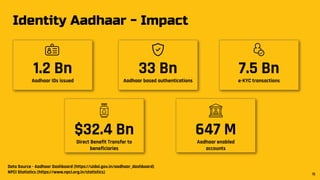
Identity Aadhaar - Impact
1.2 Bn
Aadhaar IDs issued
33 Bn
Aadhaar based authentications
7.5 Bn
e-KYC transactions
$32.4 Bn
Direct Benefit Transfer to
beneficiaries
647 M
Aadhaar enabled
accounts
Data Source - Aadhaar Dashboard (https://uidai.gov.in/aadhaar_dashboard)
NPCI Statistics (https://www.npci.org.in/statistics) 15
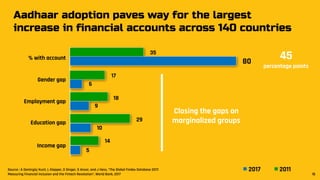
Aadhaar adoption paves way for the largest
increase in financial accounts across 140 countries
45
percentage points
2017 2011
Income gap
14
5
Education gap
29
10
Closing the gaps on
marginalized groups
35
% with account
80
Gender gap
17
6
Employment gap
18
9
Source : A Demirgüç-Kunt, L Klapper, D Singer, S Ansar, and J Hess, “The Global Findex Database 2017:
Measuring Financial Inclusion and the Fintech Revolution”, World Bank, 2017 16
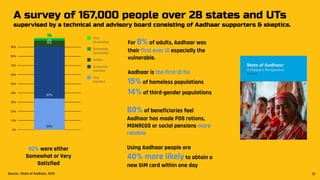
A survey of 167,000 people over 28 states and UTs
supervised by a technical and advisory board consisting of Aadhaar supporters & skeptics.
Source : State of Aadhaar, 2019 17
For 8% of adults, Aadhaar was
their first ever ID especially the
vulnerable.
Aadhaar is the first ID for
15% of homeless populations
14% of third-gender populations
92% were either
Somewhat or Very
Satisfied
80% of beneficiaries feel
Aadhaar has made PDS rations,
MGNREGS or social pensions more
reliable
Using Aadhaar people are
40% more likely to obtain a
new SIM card within one day
2
Part 2
Addressing
the Payments
Challenge
Retention
Keep them
in the system
18
People are seeking digital ways to transact
Users are looking for a MAGICAL
payment experience.
Mobile-First,
Anytime,
Global,
Instant,
Convenient,
Assured Safe,
Low-cost
19
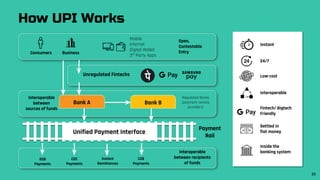
How UPI Works
Open,
Contestable
Entry
Mobile
Internet
Digital Wallet
3rd
Party Apps
Consumers Business
Bank A
Regulated Banks
(payment service
providers)
Payment
Rail
Interoperable
between
sources of funds
Interoperable
between recipients
of funds
Unified Payment Interface
C2C
Payments
Instant
Remittances
C2B
Payments
Bank B
B2B
Payments
Unregulated Fintechs
Instant
24/7
Interoperable
Low-cost
Fintech/ Bigtech
Friendly
Settled in
fiat money
Inside the
banking system
20
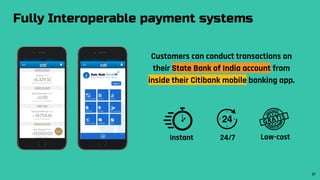
Customers can conduct transactions on
their State Bank of India account from
inside their Citibank mobile banking app.
Fully Interoperable payment systems
Instant 24/7 Low-cost
21
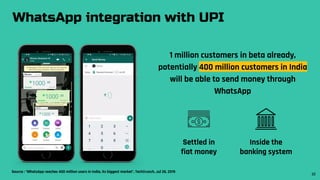
WhatsApp integration with UPI
1 million customers in beta already,
potentially 400 million customers in India
will be able to send money through
WhatsApp
Settled in
fiat money
Inside the
banking system
Source : “WhatsApp reaches 400 million users in India, its biggest market”, TechCrunch, Jul 26, 2019
22
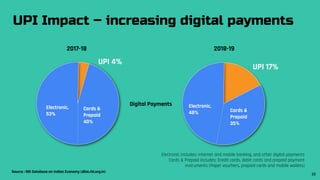
Digital Payments
2017-18 2018-19
UPI 4%
UPI 17%
Electronic,
53%
Electronic,
48%
Cards &
Prepaid
40%
Cards &
Prepaid
35%
Electronic includes: Internet and mobile banking, and other digital payments
Cards & Prepaid includes: Credit cards, debit cards and prepaid payment
instruments (Paper vouchers, prepaid cards and mobile wallets)
UPI Impact – increasing digital payments
Source : RBI Database on Indian Economy (dbie.rbi.org.in)
23
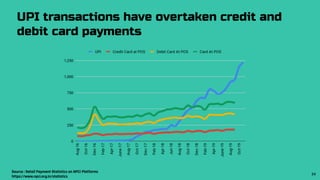
UPI transactions have overtaken credit and
debit card payments
Source : Retail Payment Statistics on NPCI Platforms
https://www.npci.org.in/statistics
24
3
Part 3
Addressing
Data Sharing &
Privacy Challenges
Data sharing without
compromising privacy
Data
Empowerment
25
User Data is being appropriated
Internet Platforms gather and retain
user data in proprietary silos.
The problem is not simply that companies are
benefiting from this data.
The problem is that the people aren’t
Account Aggregators rebalance that equation
26
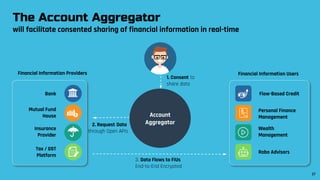
The Account Aggregator
will facilitate consented sharing of financial information in real-time
Bank
Mutual Fund
House
Insurance
Provider
Tax / GST
Platform
Flow-Based Credit
Personal Finance
Management
Wealth
Management
Robo Advisors
Financial Information Providers Financial Information Users
Account
Aggregator
3. Data Flows to FIUs
End-to-End Encrypted
1. Consent to
share data
2. Request Data
through Open APIs
27
The Account Aggregator is a
Consent Manager
000101
AAs enable consumers to
selectively share & even revoke
data once shared. The AAs have
a fiduciary duty to consumers
100111
0
1 0
0
1 1
AAs cannot read consumer data.
They cannot resell consumer data.
28
7 AAs have in-principle approval.
1 AA has operational license
10 FIU/FIPs from leading banks and NBFCs
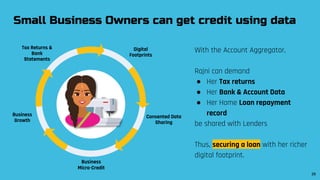
Digital
Footprints
Consented Data
Sharing
Business
Micro-Credit
Business
Growth
Tax Returns &
Bank
Statements
With the Account Aggregator,
Rajni can demand
● Her Tax returns
● Her Bank & Account Data
● Her Home Loan repayment
record
be shared with Lenders
Thus, securing a loan with her richer
digital footprint.
Small Business Owners can get credit using data
29
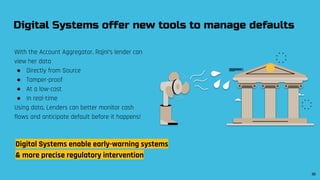
With the Account Aggregator, Rajni’s lender can
view her data
● Directly from Source
● Tamper-proof
● At a low-cost
● In real-time
Using data, Lenders can better monitor cash
flows and anticipate default before it happens!
Digital Systems offer new tools to manage defaults
Digital Systems enable early-warning systems
& more precise regulatory intervention
30
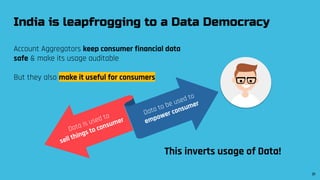
Account Aggregators keep consumer financial data
safe & make its usage auditable
But they also make it useful for consumers
India is leapfrogging to a Data Democracy
Data is used to
sell things to consumer
Data to be used to
empower consumer
This inverts usage of Data!
31
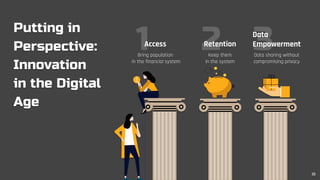
1 2 3
Putting in
Perspective:
Innovation
in the Digital
Age
Access Retention
Bring population
in the financial system
Keep them
in the system
Data
Empowerment
Data sharing without
compromising privacy
32
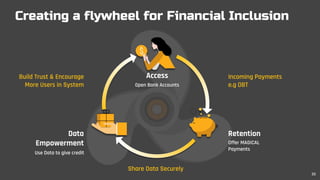
Creating a flywheel for Financial Inclusion
Access
Open Bank Accounts
Retention
Offer MAGICAL
Payments
Use Data to give credit
Data
Empowerment
Incoming Payments
e.g DBT
Share Data Securely
Build Trust & Encourage
More Users in System
33
Platforms not Pipes
The old way of innovating
was to build end-to-end
solutions
In the digital world, the
method of innovation are
platforms
34
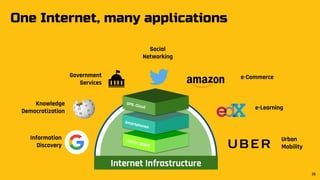
Information
Discovery
Knowledge
Democratization
Government
Services
Social
Networking
e-Commerce
e-Learning
Urban
Mobility
One Internet, many applications
Internet Infrastructure
35
TCP/IP, WWW
GPS, Cloud
Smartphones
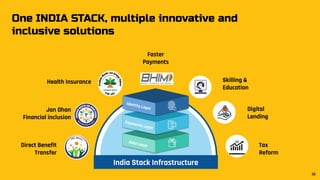
One INDIA STACK, multiple innovative and
inclusive solutions
Direct Benefit
Transfer
Jan Dhan
Financial inclusion
Health Insurance
Faster
Payments
Skilling &
Education
Digital
Lending
Tax
Reform
India Stack Infrastructure
36
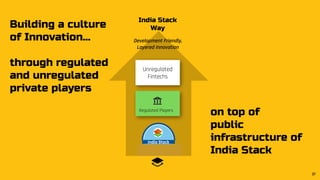
Identity Layer
Payments Layer
Data Layer
Unregulated
Fintechs
Regulated Players
India Stack
on top of
public
infrastructure of
India Stack
India Stack
Way
Development Friendly,
Layered Innovation
Building a culture
of Innovation...
through regulated
and unregulated
private players
37
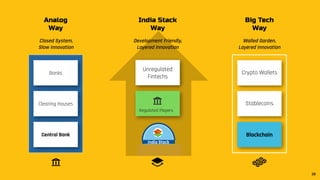
Banks
Clearing Houses
Central Bank
Analog
Way
Closed System,
Slow Innovation
Unregulated
Fintechs
Regulated Players
India Stack
Way
Development Friendly,
Layered Innovation
Crypto Wallets
Stablecoins
Blockchain
Big Tech
Way
Walled Garden,
Layered Innovation
India Stack
38
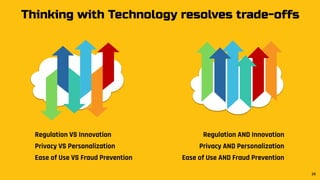
Thinking with Technology resolves trade-offs
Regulation VS Innovation
Privacy VS Personalization
Ease of Use VS Fraud Prevention
Regulation AND Innovation
Privacy AND Personalization
Ease of Use AND Fraud Prevention
39
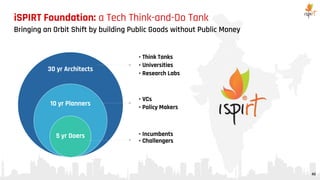
30 yr Architects
10 yr Planners
5 yr Doers
• Think Tanks
• Universities
• Research Labs
• VCs
• Policy Makers
• Incumbents
• Challengers
iSPIRT Foundation: a Tech Think-and-Do Tank
Bringing an Orbit Shift by building Public Goods without Public Money
40
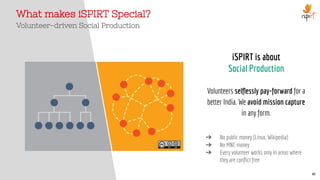
What makes iSPIRT Special?
Volunteer-driven Social Production
iSPIRT is about
Social Production
Volunteers selflessly pay-forward for a
better India. We avoid mission capture
in any form.
➔ No public money (Linux, Wikipedia)
➔ No MNC money
➔ Every volunteer works only in areas where
they are conflict free
41
Start Small
Start Anywhere
Start Today
A Stack-like approach is accessible
by everyone
42
THANK YOU