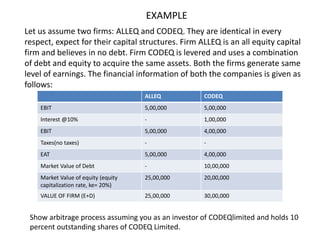
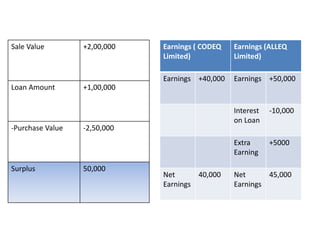
Modigliani and Miller initially developed their capital structure approach in 1958 without considering taxes. They argued that a firm's value and cost of capital are independent of its capital structure. In 1963, they revised their approach to include taxes. When taxes are considered, firm value increases with leverage as interest expenses are tax deductible, creating a tax shield. The value of a levered firm exceeds an unlevered firm by the amount of debt multiplied by the tax rate.

 Most read
 Most read
 Most read


