Definition
M.N. Mishra, defineslife insurance as
a contract in which the insurer
promises to pay a specified sum of
money upon the occurrence of a
certain event (such as the death of
the insured or upon reaching a
certain age) in exchange for the
premiums paid by the insured over
time.
3.
Definition
George E. Rejda,defines life insurance
as a financial contract that provides
a predetermined sum of money to
beneficiaries upon the death of the
insured. Rejda emphasizes that life
insurance is a tool for managing the
risk of financial loss due to death,
primarily designed to offer economic
security to the insured's dependents
or other beneficiaries.
5.
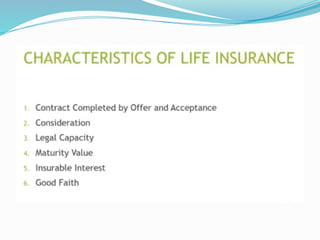
Offer and Acceptance
Offer:
Anoffer in life insurance is typically
initiated by the applicant (proposer) when
they submit a completed application form
to the insurance company.
The offer includes the applicant's intent to
buy a specific policy and the premium
amount they are willing to pay.
This offer may also be conditional,
depending on the applicant's health or
other risk factors evaluated by the insurer.
6.
Offer and Acceptance
Acceptance:
•The insurance company evaluates the offer
through assessing the applicant's risk
profile, which includes medical history, age,
lifestyle, and other factors.
• If the insurer is willing to cover the
applicant at the proposed premium, it issues
a policy document, marking acceptance.
• In some cases, the insurer may modify the
terms (e.g., a higher premium or additional
exclusions), making a counteroffer that the
applicant must accept.
7.
Consideration
• For alife insurance policy, consideration is
provided by both parties: the insured pays
premiums, and the insurer promises to pay a
specified sum (death benefit or maturity benefit)
upon the occurrence of a specified event.
• The primary consideration from the
policyholder’s side is the regular payment of
premiums.
• The insurer’s consideration is its commitment to
pay a specified benefit to the beneficiaries upon
the death of the insured or upon maturity of the
policy, subject to the terms and conditions.
8.
Legal Capacity
• Boththe insurer and the insured must have
the legal ability to enter into a contract. This
includes having the mental and legal
competency to understand the nature of the
contract.
• For the insured, legal capacity typically means
being of sound mind and of legal age as
defined by law.
• The insurance company must be legally
licensed and authorized to sell life insurance
in the relevant jurisdiction. If an insurer is not
licensed, the policy may be considered invalid.
9.
Maturity Value
• Maturityvalue is the sum paid by the insurer
to the policyholder if the policyholder survives
the entire policy term.
• It represents the contractual benefit payable at
the end of the policy period, including any
bonuses or additional amounts, if applicable.
• Bonuses and additions vary depending on the
policy type, insurer, and policy performance.
10.
Insurable Interest
• Familymembers often have an automatic
insurable interest. This includes spouses,
parents, children, and, in some cases, siblings
or other close relatives.
• Business relationships can also create insurable
interest. For example, business partners can
have insurable interest in each other.
• Financial dependence or a legal obligation,
such as debts or contractual relationships, can
also establish insurable interest.
11.
Good Faith
• UtmostGood Faith requires both parties in a
life insurance contract—the insurer and the
insured—to act honestly and disclose all
relevant information that may affect the
contract.
• The insured must disclose all material facts
about their health, lifestyle, occupation, and
any other factors that could impact the risk
level of the policy.
• The insurer is also obligated to provide clear,
accurate information about the policy terms,
exclusions, benefits, and any conditions
associated with the life insurance contract.
14.
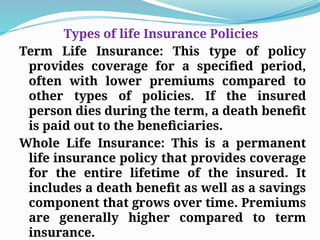
Types of lifeInsurance Policies
Term Life Insurance: This type of policy
provides coverage for a specified period,
often with lower premiums compared to
other types of policies. If the insured
person dies during the term, a death benefit
is paid out to the beneficiaries.
Whole Life Insurance: This is a permanent
life insurance policy that provides coverage
for the entire lifetime of the insured. It
includes a death benefit as well as a savings
component that grows over time. Premiums
are generally higher compared to term
insurance.
15.
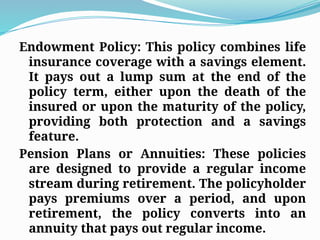
Endowment Policy: Thispolicy combines life
insurance coverage with a savings element.
It pays out a lump sum at the end of the
policy term, either upon the death of the
insured or upon the maturity of the policy,
providing both protection and a savings
feature.
Pension Plans or Annuities: These policies
are designed to provide a regular income
stream during retirement. The policyholder
pays premiums over a period, and upon
retirement, the policy converts into an
annuity that pays out regular income.