Japan's Semiconductor Ecosystem: Strategy, Value Chain, and Future Outlook
1.
J A PAN S E M I C O N D U C T O R E C O S Y S T E M
Value Chain Participation, National Strategy
and the Road Back to the Leading Edge
Materials & equipment dominance | Rapidus 2 nm | TSMC-JASM, Micron, Kioxia | ¥10T+ policy push
Research briefing • July 2026 • All figures sourced and dated
2.
E X EC U T I V E S U M M A R Y
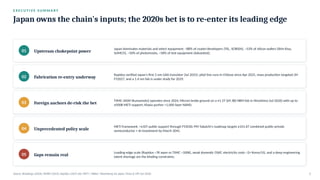
Japan owns the chain's inputs; the 2020s bet is to re-enter its leading edge
01 Upstream chokepoint power
Japan dominates materials and select equipment: ~88% of coater/developers (TEL, SCREEN), ~53% of silicon wafers (Shin-Etsu,
SUMCO), ~50% of photoresists, ~58% of test equipment (Advantest).
02 Fabrication re-entry underway
Rapidus verified Japan's first 2 nm GAA transistor (Jul 2025); pilot line runs in Chitose since Apr 2025, mass production targeted 2H
FY2027, and a 1.4 nm fab is under study for 2029.
03 Foreign anchors de-risk the bet
TSMC-JASM (Kumamoto) operates since 2024; Micron broke ground on a ¥1.5T ($9.3B) HBM fab in Hiroshima (Jul 2026) with up to
¥500B METI support; Kioxia pushes >1,000-layer NAND.
04 Unprecedented policy scale
METI framework: >¥10T public support through FY2030; PM Takaichi's roadmap targets ¥101.6T combined public-private
semiconductor + AI investment by March 2041.
05 Gaps remain real
Leading-edge scale (Rapidus ~7K wpm vs TSMC ~100K), weak domestic OSAT, electricity costs ~2× Korea/US, and a deep engineering
talent shortage are the binding constraints.
Source: Brookings (2024); AMRO (2025); Rapidus (2025-26); METI / Nikkei / Bloomberg via Japan Times & UPI (Jul 2026) 2
3.
H I ST O R I C A L A R C
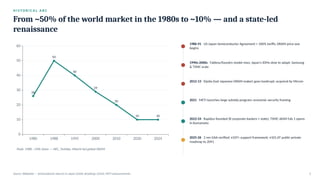
From ~50% of the world market in the 1980s to ~10% — and a state-led
renaissance
1980 1988 1995 2000 2010 2020 2024
0
10
20
30
40
50
60
26
50
40
29
20
10 10
Peak: 1988, ~50% share — NEC, Toshiba, Hitachi led global DRAM
1986-91 US-Japan Semiconductor Agreement + 100% tariffs; DRAM price war
begins
1990s-2000s Fabless/foundry model rises; Japan's IDMs slow to adapt; Samsung
& TSMC scale
2012-13 Elpida (last Japanese DRAM maker) goes bankrupt; acquired by Micron
2021 METI launches large subsidy program; economic security framing
2022-24 Rapidus founded (8 corporate backers + state); TSMC-JASM Fab 1 opens
in Kumamoto
2025-26 2 nm GAA verified; ¥10T+ support framework; ¥101.6T public-private
roadmap to 2041
Source: Wikipedia — Semiconductor industry in Japan (2026); Brookings (2024); METI announcements 3
4.
VA L UE C H A I N M A P
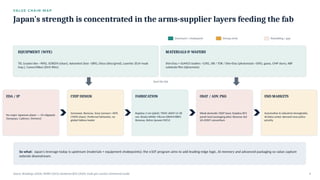
Japan's strength is concentrated in the arms-supplier layers feeding the fab
Dominant / chokepoint Strong niche Rebuilding / gap
EQUIPMENT (WFE)
TEL (coater/dev ~90%), SCREEN (clean), Advantest (test ~58%), Disco (dice/grind), Lasertec (EUV mask
insp.), Canon/Nikon (DUV litho)
MATERIALS & WAFERS
Shin-Etsu + SUMCO (wafers ~53%), JSR / TOK / Shin-Etsu (photoresist ~50%), gases, CMP slurry, ABF
substrate film (Ajinomoto)
feed the fab
EDA / IP
No major Japanese player — US oligopoly
(Synopsys, Cadence, Siemens)
CHIP DESIGN
Socionext, Renesas, Sony (sensors >40%
CMOS share), Preferred Networks; no
global fabless leader
FABRICATION
Rapidus 2 nm (pilot); TSMC-JASM 12-28
nm; Kioxia NAND; Micron DRAM/HBM;
Renesas, Rohm (power/MCU)
OSAT / ADV. PKG
Weak domestic OSAT base; Rapidus RCS
panel-level packaging pilot; Resonac-led
US-JOINT consortium
END MARKETS
Automotive & industrial strongholds;
AI/data-center demand now policy
priority
So what: Japan's leverage today is upstream (materials + equipment chokepoints); the ¥10T program aims to add leading-edge logic, AI memory and advanced packaging so value capture
extends downstream.
Source: Brookings (2024); AMRO (2025); kantenna/SEAJ (2026); trade.gov Country Commercial Guide 4
5.
U P ST R E A M D O M I N A N C E
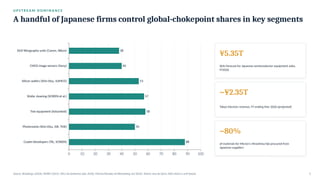
A handful of Japanese firms control global-chokepoint shares in key segments
Coater/developers (TEL, SCREEN)
Photoresists (Shin-Etsu, JSR, TOK)
Test equipment (Advantest)
Wafer cleaning (SCREEN et al.)
Silicon wafers (Shin-Etsu, SUMCO)
CMOS image sensors (Sony)
DUV lithography units (Canon, Nikon)
0 10 20 30 40 50 60 70 80 90 100
88
50
58
57
53
40
38
¥5.35T
SEAJ forecast for Japanese semiconductor equipment sales,
FY2026
~¥2.35T
Tokyo Electron revenue, FY ending Mar 2026 (projected)
~80%
of materials for Micron's Hiroshima fab procured from
Japanese suppliers
Source: Brookings (2024); AMRO (2025); SEAJ via kantenna (Apr 2026); Micron/Nosaka via Bloomberg (Jul 2026). Shares vary by basis; litho share is unit-based. 5
6.
T H EB U I L D - O U T
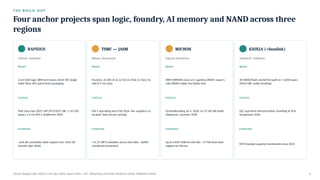
Four anchor projects span logic, foundry, AI memory and NAND across three
regions
RAPIDUS
Chitose, Hokkaido
WHAT
2 nm GAA logic (IBM tech base); short-TAT single-
wafer flow; RCS panel-level packaging
STATUS
Pilot since Apr 2025; MP 2H FY2027 (6K → 20-25K
wpm); 1.4 nm IIM-2 studied for 2029
FUNDING
~$16.3B cumulative state support incl. ¥631.5B
tranche (Apr 2026)
TSMC — JASM
Kikuyo, Kumamoto
WHAT
Foundry: 22/28 nm & 12/16 nm (Fab 1); Fab 2 to
add 6/7 nm-class
STATUS
Fab 1 operating since Feb 2024; 44+ suppliers co-
located; Sony sensor synergy
FUNDING
~¥1.2T METI subsidies across two fabs; ~$20B+
combined investment
MICRON
Higashi-Hiroshima
WHAT
HBM (HBM4E-class) on 1-gamma DRAM; Japan's
only DRAM maker (ex-Elpida site)
STATUS
Groundbreaking Jul 4, 2026; ¥1.5T ($9.3B) build;
shipments ~summer 2028
FUNDING
Up to ¥500-536B for this fab; ~¥775B total state
support to Micron
KIOXIA (+Sandisk)
Yokkaichi / Kitakami
WHAT
3D NAND flash; world-first path to >1,000 layers
(MSA-CBA, wafer bonding)
STATUS
QLC operation demonstrated; unveiling at VLSI
Symposium 2026
FUNDING
METI-backed capacity investments since 2021
Source: Rapidus (Apr 2026); ic-pcb (Apr 2026); Japan Times / UPI / Bloomberg (Jul 2026); kantenna (2026); Wikipedia (2026) 6
7.
R A PI D U S D E E P D I V E
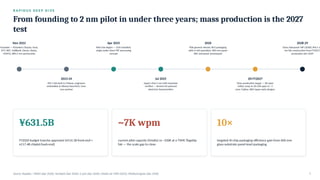
From founding to 2 nm pilot in under three years; mass production is the 2027
test
Nov 2022
Founded — 8 backers (Toyota, Sony,
NTT, NEC, SoftBank, Denso, Kioxia,
MUFG); IBM 2 nm partnership
2023-24
IIM-1 fab built in Chitose; engineers
embedded at Albany NanoTech; imec
core partner
Apr 2025
Pilot line begins — EUV installed;
single-wafer short-TAT processing
concept
Jul 2025
Japan's first 2 nm GAA transistor
verified — devices hit planned
electrical characteristics
2026
PDK general release; RCS packaging
pilot in full operation; 600 mm panel
RDL interposer prototyped
2H FY2027
Mass production target — 6K wpm
initial, ramp to 20-25K wpm in ~1
year; Fujitsu, IBM Japan early designs
2028-29
Glass interposer MP (2028); IIM-2 1
nm fab construction from FY2027,
production aim 2029
¥631.5B
FY2026 budget tranche approved (¥514.1B front-end +
¥117.4B chiplet/back-end)
~7K wpm
current pilot capacity (Omdia) vs ~100K at a TSMC flagship
fab — the scale gap to close
10×
targeted AI-chip packaging efficiency gain from 600 mm
glass-substrate panel-level packaging
Source: Rapidus / NEDO (Apr 2026); TechSpot (Apr 2026); ic-pcb (Apr 2026); Omdia via TSPA (2025); Medium/ogata (Apr 2026) 7
8.
P O LI C Y A R C H I T E C T U R E
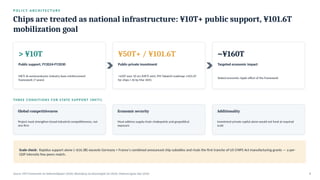
Chips are treated as national infrastructure: ¥10T+ public support, ¥101.6T
mobilization goal
> ¥10T
Public support, FY2024-FY2030
METI AI-semiconductor industry base reinforcement
framework (7 years)
¥50T+ / ¥101.6T
Public-private investment
>¥50T over 10 yrs (METI aim); PM Takaichi roadmap: ¥101.6T
for chips + AI by Mar 2041
~¥160T
Targeted economic impact
Stated economic ripple effect of the framework
THREE CONDITIONS FOR STATE SUPPORT (METI)
Global competitiveness
Project must strengthen broad industrial competitiveness, not
one firm
Economic security
Must address supply-chain chokepoints and geopolitical
exposure
Additionality
Investment private capital alone would not fund at required
scale
Scale check: Rapidus support alone (~$16.3B) exceeds Germany + France's combined announced chip subsidies and rivals the first tranche of US CHIPS Act manufacturing grants — a per-
GDP intensity few peers match.
Source: METI framework via helloworldjapan (2026); Bloomberg via bloomingbit (Jul 2026); Medium/ogata (Apr 2026) 8
9.
C O NS T R A I N T S
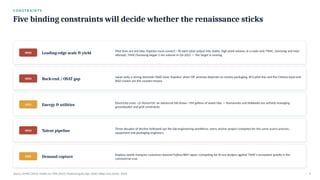
Five binding constraints will decide whether the renaissance sticks
HIGH Leading-edge scale & yield
Pilot lines are not fabs: Rapidus must convert ~7K wpm pilot output into stable, high-yield volume at a node only TSMC, Samsung and Intel
attempt; TSMC/Samsung began 2 nm volume in Q4 2025 — the target is moving.
HIGH Back-end / OSAT gap Japan lacks a strong domestic OSAT base; Rapidus' short-TAT promise depends on nearby packaging. RCS pilot line and the Chitose back-end
R&D cluster are the counter-moves.
MED Energy & utilities Electricity costs ~2× Korea/US; an advanced fab draws ~5M gallons of water/day — Kumamoto and Hokkaido are actively managing
groundwater and grid constraints.
HIGH Talent pipeline
Three decades of decline hollowed out the fab-engineering workforce; every anchor project competes for the same scarce process,
equipment and packaging engineers.
MED Demand capture Rapidus needs marquee customers beyond Fujitsu/IBM Japan; competing for AI-era designs against TSMC's ecosystem gravity is the
commercial crux.
Source: AMRO (2025); Omdia via TSPA (2025); Medium/ogata (Apr 2026); Nikkei Asia (Satoh, 2024) 9
10.
O U TL O O K & I M P L I C AT I O N S
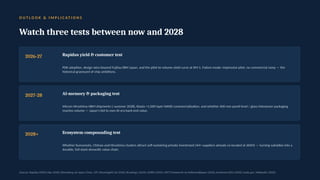
Watch three tests between now and 2028
2026-27 Rapidus yield & customer test
PDK adoption, design wins beyond Fujitsu/IBM Japan, and the pilot-to-volume yield curve at IIM-1. Failure mode: impressive pilot, no commercial ramp — the
historical graveyard of chip ambitions.
2027-28 AI-memory & packaging test
Micron Hiroshima HBM shipments (~summer 2028), Kioxia >1,000-layer NAND commercialization, and whether 600 mm panel-level / glass-interposer packaging
reaches volume — Japan's bid to own AI-era back-end value.
2028+ Ecosystem compounding test
Whether Kumamoto, Chitose and Hiroshima clusters attract self-sustaining private investment (44+ suppliers already co-located at JASM) — turning subsidies into a
durable, full-stack domestic value chain.
Sources: Rapidus/NEDO (Apr 2026); Bloomberg via Japan Times, UPI, bloomingbit (Jul 2026); Brookings (2024); AMRO (2025); METI framework via helloworldjapan (2026); kantenna/SEAJ (2026); trade.gov; Wikipedia (2026).