Download to read offline

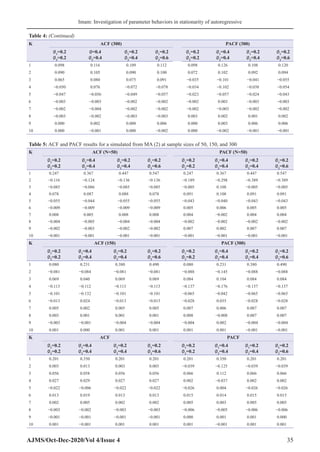
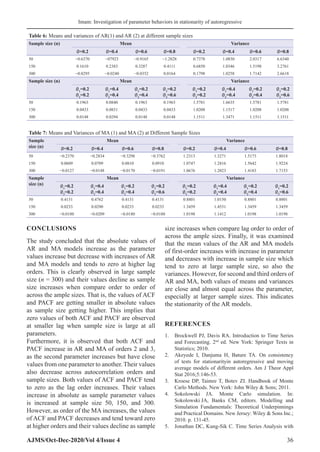
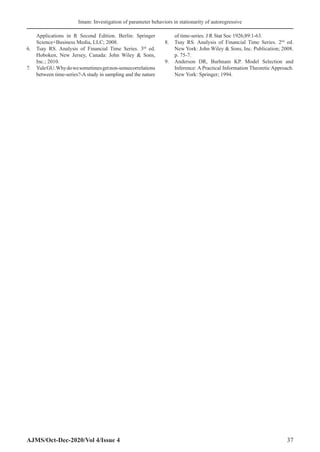

This study investigates the behavior of parameters in the stationarity of autoregressive (AR) and moving average (MA) models through simulations using R statistical software. It finds that the autocorrelation function (ACF) and partial autocorrelation function (PACF) of AR and MA models increase with parameter values but decrease with higher orders, tending to zero at larger sample sizes. The research underscores the significance of understanding stationarity in time series for accurate economic and industrial predictions.


