Financial Protection against Disasters 
Is it worth your money? 
Benedikt Signer 
Disaster Risk Financing and Insurance Program 
The World Bank - GFDRR 
5th International Disaster and Risk Conference 
Special Panel, Is Financial Protection Worth It? 
August 28, 2014 
With support from
Outline 
1. Disaster Risk Financing and Insurance at the 
World Bank 
2. Sovereign DRFI Impact Appraisal Project 
3. Initial findings – 
“Characteristics of Financial Resilience”
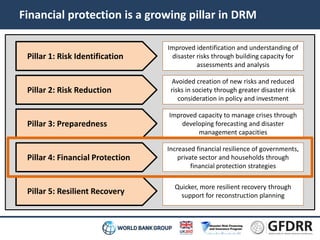
Financial protection is a growing pillar in DRM 
Pillar 1: Risk Identification 
Pillar 2: Risk Reduction 
Pillar 3: Preparedness 
Pillar 4: Financial Protection 
Pillar 5: Resilient Recovery 
Improved identification and understanding of 
disaster risks through building capacity for 
assessments and analysis 
Avoided creation of new risks and reduced 
risks in society through greater disaster risk 
consideration in policy and investment 
Improved capacity to manage crises through 
developing forecasting and disaster 
management capacities 
Increased financial resilience of governments, 
private sector and households through 
financial protection strategies 
Quicker, more resilient recovery through 
support for reconstruction planning
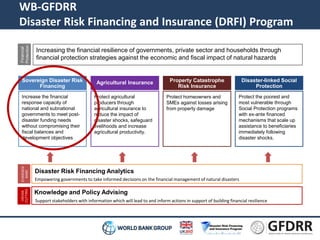
WB-GFDRR 
Disaster Risk Financing and Insurance (DRFI) Program 
Sovereign Disaster Risk 
Financing 
Agricultural Insurance Property Catastrophe 
Disaster Risk Financing Analytics 
Risk Insurance 
Disaster-linked Social 
Protection 
Increase the financial 
response capacity of 
national and subnational 
governments to meet post-disaster 
funding needs 
without compromising their 
fiscal balances and 
development objectives 
Protect agricultural 
producers through 
agricultural insurance to 
reduce the impact of 
disaster shocks, safeguard 
livelihoods and increase 
agricultural productivity. 
Protect homeowners and 
SMEs against losses arising 
from property damage 
Protect the poorest and 
most vulnerable through 
Social Protection programs 
with ex-ante financed 
mechanisms that scale up 
assistance to beneficiaries 
immediately following 
disaster shocks. 
Empowering governments to take informed decisions on the financial management of natural disasters 
Financial 
Protection 
Increasing the financial resilience of governments, private sector and households through 
financial protection strategies against the economic and fiscal impact of natural hazards 
PILLAR 3 PILLAR 4 PILLAR 5 
CROSS 
CUTTING 
Knowledge and Policy Advising 
EVIDENCE 
BASE 
Support stakeholders with information which will lead to and inform actions in support of building financial resilience
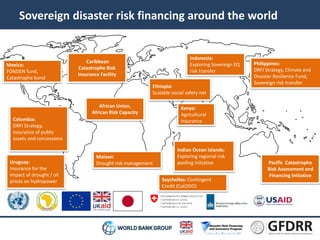
Sovereign disaster risk financing around the world 
Caribbean 
Catastrophe Risk 
Insurance Facility 
Mexico: 
FONDEN fund, 
Catastrophe bond 
Colombia: 
DRFI Strategy, 
Insurance of public 
assets and concessions 
Pacific Catastrophe 
Risk Assessment and 
Financing Initiative 
African Union, 
African Risk Capacity 
Indonesia: 
Exploring Sovereign EQ 
risk transfer 
Ethiopia: 
Scalable social safety net 
Indian Ocean Islands: 
Exploring regional risk 
pooling initiative 
Philippines: 
DRFI Strategy, Climate and 
Disaster Resilience Fund, 
Sovereign risk transfer 
Kenya: 
Agricultural 
Insurance 
Malawi: 
Uruguay: Drought risk management 
Insurance for the 
impact of drought / oil 
prices on hydropower Seychelles: Contingent 
Credit (CatDDO)
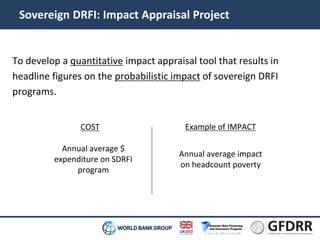
Sovereign DRFI: Impact Appraisal Project 
To develop a quantitative impact appraisal tool that results in 
headline figures on the probabilistic impact of sovereign DRFI 
programs. 
COST Example of IMPACT 
Annual average $ 
expenditure on SDRFI 
program 
Annual average impact 
on headcount poverty
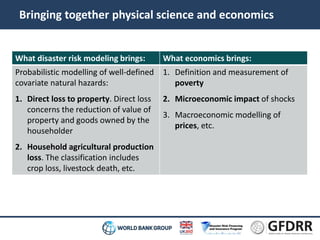
Bringing together physical science and economics 
What disaster risk modeling brings: What economics brings: 
Probabilistic modelling of well-defined 
covariate natural hazards: 
1. Direct loss to property. Direct loss 
concerns the reduction of value of 
property and goods owned by the 
householder 
2. Household agricultural production 
loss. The classification includes 
crop loss, livestock death, etc. 
1. Definition and measurement of 
poverty 
2. Microeconomic impact of shocks 
3. Macroeconomic modelling of 
prices, etc.
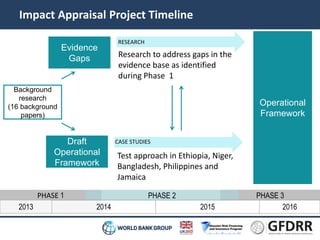
Impact Appraisal Project Timeline 
Background 
research 
(16 background 
papers) 
Evidence 
Gaps 
Draft 
Operational 
Framework 
Operational 
Framework 
RESEARCH 
Research to address gaps in the 
evidence base as identified 
during Phase 1 
CASE STUDIES 
Test approach in Ethiopia, Niger, 
Bangladesh, Philippines and 
Jamaica 
PHASE 1 PHASE 2 PHASE 3 
2013 2014 2015 2016
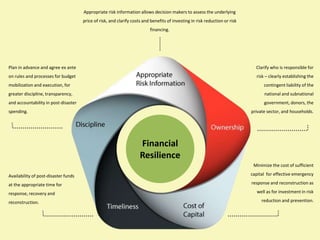
Financial 
Resilience 
Plan in advance and agree ex ante 
on rules and processes for budget 
mobilization and execution, for 
greater discipline, transparency, 
and accountability in post-disaster 
spending. 
Availability of post-disaster funds 
at the appropriate time for 
response, recovery and 
reconstruction. 
Clarify who is responsible for 
risk – clearly establishing the 
contingent liability of the 
national and subnational 
government, donors, the 
private sector, and households. 
Minimize the cost of sufficient 
capital for effective emergency 
response and reconstruction as 
well as for investment in risk 
reduction and prevention. 
Appropriate risk information allows decision makers to assess the underlying 
price of risk, and clarify costs and benefits of investing in risk reduction or risk 
financing.
Thank you to all our project partners 
“all models are wrong, but 
some are useful” 
George E. P. Box