CONFIDENTIAL & LEGALLY PRIVILEGED
Adiyanth Analytics
Introduction to approaches in Fraud Analytics
+91 888 494 8072Info.blr@adiyanth.com madirajua
Page 2© adiyanth – Distribution Restricted
Transaction
data
Application
data
Credit Bureau
Data
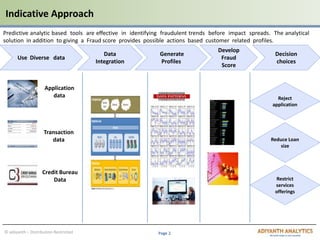
Use Diverse data
Data
Integration
Generate
Profiles
Decision
choices
Develop
Fraud
Score
Indicative Approach
Reject
application
Reduce Loan
size
Restrict
services
offerings
Predictive analytic based tools are effective in identifying fraudulent trends before impact spreads. The analytical
solution in addition to giving a Fraud score provides possible actions based customer related profiles.
Page 3© adiyanth – Distribution Restricted
Indicative Outputs
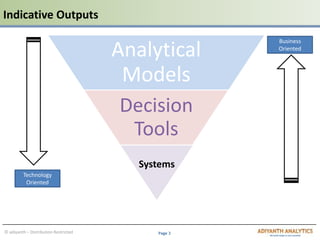
Analytical
Models
Decision
Tools
Systems
Business
Oriented
Technology
Oriented
Page 4© adiyanth – Distribution Restricted
Fraud Analytics
Credit Card
Analytics
Fraud Analytics as a Program
- Economics
- Driver Analysis
- Competency
Page 5© adiyanth – Distribution Restricted
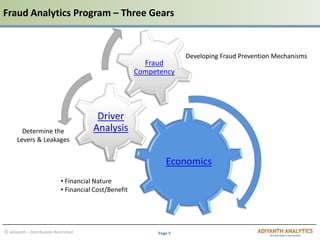
Fraud Analytics Program – Three Gears
Economics
Driver
Analysis
Fraud
Competency
Developing Fraud Prevention Mechanisms
• Financial Nature
• Financial Cost/Benefit
Determine the
Levers & Leakages
Page 6© adiyanth – Distribution Restricted
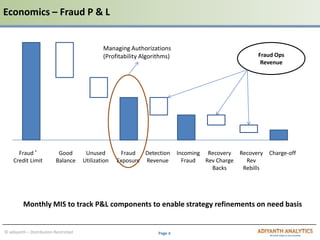
Economics – Fraud P & L
Fraud *
Credit Limit
Good
Balance
Unused
Utilization
Fraud
Exposure
Detection
Revenue
Incoming
Fraud
Recovery
Rev Charge
Backs
Recovery
Rev
Rebills
Charge-off
Fraud Ops
Revenue
Monthly MIS to track P&L components to enable strategy refinements on need basis
Managing Authorizations
(Profitability Algorithms)
Page 7© adiyanth – Distribution Restricted
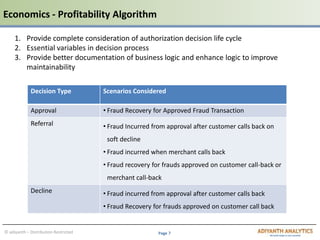
Decision Type Scenarios Considered
Approval • Fraud Recovery for Approved Fraud Transaction
Referral • Fraud Incurred from approval after customer calls back on
soft decline
• Fraud incurred when merchant calls back
• Fraud recovery for frauds approved on customer call-back or
merchant call-back
Decline • Fraud incurred from approval after customer calls back
• Fraud Recovery for frauds approved on customer call back
1. Provide complete consideration of authorization decision life cycle
2. Essential variables in decision process
3. Provide better documentation of business logic and enhance logic to improve
maintainability
Economics - Profitability Algorithm
Page 8© adiyanth – Distribution Restricted
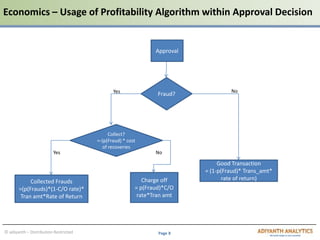
Economics – Usage of Profitability Algorithm within Approval Decision
Fraud?
Approval
Good Transaction
= (1-p(Fraud)* Trans_amt*
rate of return)
Collect?
=-(p(Fraud) * cost
of recoveries
Charge off
= p(Fraud)*C/O
rate*Tran amt
Collected Frauds
=(p(Frauds)*(1-C/O rate)*
Tran amt*Rate of Return
Yes No
Yes No
Page 9© adiyanth – Distribution Restricted
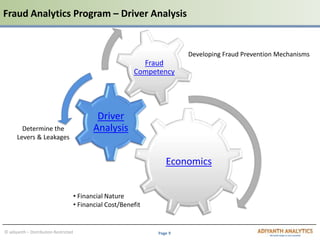
Fraud Analytics Program – Driver Analysis
Economics
Driver
Analysis
Fraud
Competency
Developing Fraud Prevention Mechanisms
• Financial Nature
• Financial Cost/Benefit
Determine the
Levers & Leakages
Page 10© adiyanth – Distribution Restricted
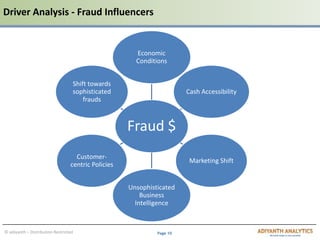
Driver Analysis - Fraud Influencers
Fraud $
Economic
Conditions
Cash Accessibility
Marketing Shift
Unsophisticated
Business
Intelligence
Customer-
centric Policies
Shift towards
sophisticated
frauds
Page 11© adiyanth – Distribution Restricted
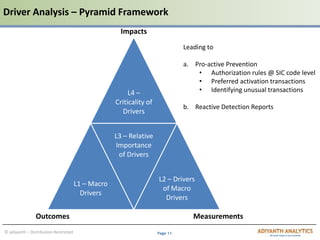
Driver Analysis – Pyramid Framework
L4 –
Criticality of
Drivers
L1 – Macro
Drivers
L3 – Relative
Importance
of Drivers
L2 – Drivers
of Macro
Drivers
Outcomes Measurements
Impacts
Leading to
a. Pro-active Prevention
• Authorization rules @ SIC code level
• Preferred activation transactions
• Identifying unusual transactions
b. Reactive Detection Reports
Page 12© adiyanth – Distribution Restricted
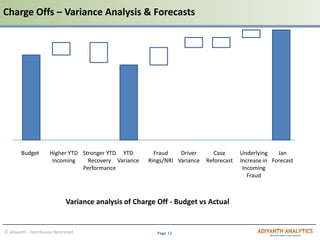
Charge Offs – Variance Analysis & Forecasts
Budget Higher YTD
Incoming
Stronger YTD
Recovery
Performance
YTD
Variance
Fraud
Rings/NRI
Driver
Variance
Case
Reforecast
Underlying
Increase in
Incoming
Fraud
Jan
Forecast
Variance analysis of Charge Off - Budget vs Actual
Page 13© adiyanth – Distribution Restricted
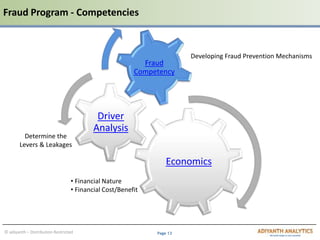
Fraud Program - Competencies
Economics
Driver
Analysis
Fraud
Competency
Developing Fraud Prevention Mechanisms
• Financial Nature
• Financial Cost/Benefit
Determine the
Levers & Leakages
Page 14© adiyanth – Distribution Restricted
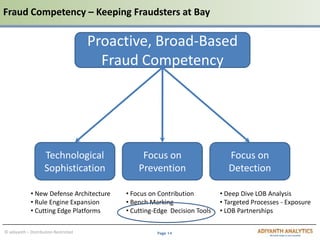
Fraud Competency – Keeping Fraudsters at Bay
Proactive, Broad-Based
Fraud Competency
Technological
Sophistication
Focus on
Prevention
Focus on
Detection
• New Defense Architecture
• Rule Engine Expansion
• Cutting Edge Platforms
• Focus on Contribution
• Bench Marking
• Cutting-Edge Decision Tools
• Deep Dive LOB Analysis
• Targeted Processes - Exposure
• LOB Partnerships
Page 15© adiyanth – Distribution Restricted
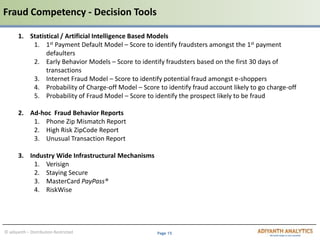
Fraud Competency - Decision Tools
1. Statistical / Artificial Intelligence Based Models
1. 1st Payment Default Model – Score to identify fraudsters amongst the 1st payment
defaulters
2. Early Behavior Models – Score to identify fraudsters based on the first 30 days of
transactions
3. Internet Fraud Model – Score to identify potential fraud amongst e-shoppers
4. Probability of Charge-off Model – Score to identify fraud account likely to go charge-off
5. Probability of Fraud Model – Score to identify the prospect likely to be fraud
2. Ad-hoc Fraud Behavior Reports
1. Phone Zip Mismatch Report
2. High Risk ZipCode Report
3. Unusual Transaction Report
3. Industry Wide Infrastructural Mechanisms
1. Verisign
2. Staying Secure
3. MasterCard PayPass®
4. RiskWise
Page 16© adiyanth – Distribution Restricted
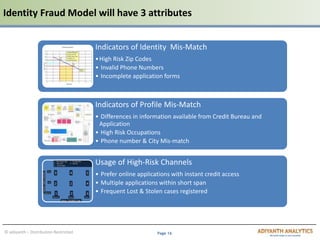
Identity Fraud Model will have 3 attributes
Indicators of Identity Mis-Match
•High Risk Zip Codes
• Invalid Phone Numbers
• Incomplete application forms
Indicators of Profile Mis-Match
• Differences in information available from Credit Bureau and
Application
• High Risk Occupations
• Phone number & City Mis-match
Usage of High-Risk Channels
• Prefer online applications with instant credit access
• Multiple applications within short span
• Frequent Lost & Stolen cases registered
Page 17© adiyanth – Distribution Restricted
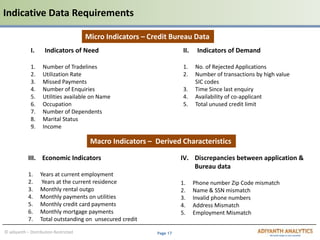
Indicative Data Requirements
I. Indicators of Need
1. Number of Tradelines
2. Utilization Rate
3. Missed Payments
4. Number of Enquiries
5. Utilities available on Name
6. Occupation
7. Number of Dependents
8. Marital Status
9. Income
II. Indicators of Demand
1. No. of Rejected Applications
2. Number of transactions by high value
SIC codes
3. Time Since last enquiry
4. Availability of co-applicant
5. Total unused credit limit
III. Economic Indicators
1. Years at current employment
2. Years at the current residence
3. Monthly rental outgo
4. Monthly payments on utilities
5. Monthly credit card payments
6. Monthly mortgage payments
7. Total outstanding on unsecured credit
IV. Discrepancies between application &
Bureau data
1. Phone number Zip Code mismatch
2. Name & SSN mismatch
3. Invalid phone numbers
4. Address Mismatch
5. Employment Mismatch
Micro Indicators – Credit Bureau Data
Macro Indicators – Derived Characteristics
Page 18© adiyanth – Distribution Restricted
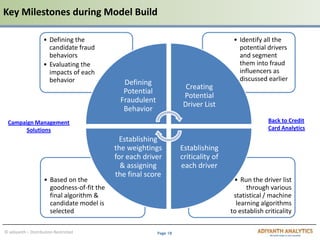
Key Milestones during Model Build
• Run the driver list
through various
statistical / machine
learning algorithms
to establish criticality
• Based on the
goodness-of-fit the
final algorithm &
candidate model is
selected
• Identify all the
potential drivers
and segment
them into fraud
influencers as
discussed earlier
• Defining the
candidate fraud
behaviors
• Evaluating the
impacts of each
behavior Defining
Potential
Fraudulent
Behavior
Creating
Potential
Driver List
Establishing
criticality of
each driver
Establishing
the weightings
for each driver
& assigning
the final score
Back to Credit
Card Analytics
Campaign Management
Solutions
Page 19© adiyanth – Distribution Restricted
Adiyanth Analytics is being set up with a vision of supplying analytical capabilities to
organizations that would want to "compete and win" based on its Data-driven
Competitive Advantage. We intend to arm the clients with this capability through any
one of the 3 core approaches - Outsourcing, Data Solutions, Professional Services. We
focus on Information & Knowledge management services wishing to cater to market
segment that consists of :
 organizations that have experienced growth for at least 5 years resulting in a unique
culture, brand recall, appreciation and market expectations being at their peak.
 These organizations are now at cusp and are at risk of quickly slipping into “trough of
disillusionment”, or at best feared for, flattened slope of enlightenment from any
misstep.
 They are addressing the 3 key challenges of Information Economy, viz., Availability,
Accessibility & Affordability of "knowledge for decision making"
About Us