Foreign Investment in China 2026: Transitioning from Manufacturing Hub to Innovation Leader
Analysis of China's evolving FDI landscape, highlighting shifts from manufacturing to R&D, risks, opportunities, and strategic decision-making for foreign investors in technology and innovation sectors.
Foreign Investment in China 2026: Transitioning from Manufacturing Hub to Innovation Leader
1.
Foreign Investment
in China2026
A Structural Reconfiguration: From "World Factory" to Innovation Arena
August, 2026
Produced By Amanda Li, Independent Chinese Consultant
AmandaLibusiness@hotmail.com
2.
Table of Contents
01The FDI Paradox
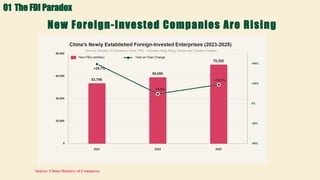
Lower headline capital, more new foreign-invested entities
02 Who Is Leaving, Who Is Staying
Strategic pullback, localization, and selected case studies
03 The New China Logic
From world factory to innovation arena and technology-intensive bets
04 Risk Map for Foreign Companies
Geopolitics, regulation, IP, competition, and capital allocation
05 Opportunity Sectors & Entry Filter
Where China still matters, and how to decide whether to enter
Core question: Is China exposure being reduced, or being repriced and rebuilt?
3.
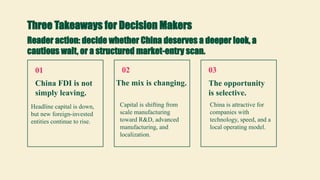
Three Takeaways forDecision Makers
01
China FDI is not
simply leaving.
Headline capital is down,
but new foreign-invested
entities continue to rise.
02
The mix is changing.
Capital is shifting from
scale manufacturing
toward R&D, advanced
manufacturing, and
localization.
03
The opportunity
is selective.
China is attractive for
companies with
technology, speed, and a
local operating model.
Reader action: decide whether China deserves a deeper look, a
cautious wait, or a structured market-entry scan.
4.
Global Context: FDIIs Being Repriced Everywhere
Overview:
- Global investment as operating in a turbulent era.
- Developing Asia remained the largest developing-region recipient in 2025.
- China remains a major FDI destination, but the model is moving from scale expansion
toward quality upgrading.
- Geopolitical tension, trade policy uncertainty, and economic-security concerns now shape
cross-border investment decisions.
Source: UNCTAD WIR 2026.
01 The FDI Paradox
5.
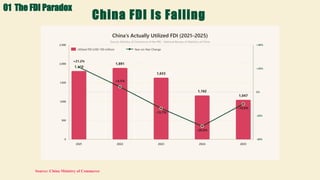
China FDI IsFalling
Source: China Ministry of Commerce
01 The FDI Paradox
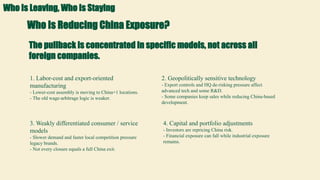
Who Is ReducingChina Exposure?
The pullback is concentrated in specific models, not across all
foreign companies.
1. Labor-cost and export-oriented
manufacturing
- Lower-cost assembly is moving to China+1 locations.
- The old wage-arbitrage logic is weaker.
2. Geopolitically sensitive technology
- Export controls and HQ de-risking pressure affect
advanced tech and some R&D.
- Some companies keep sales while reducing China-based
development.
3. Weakly differentiated consumer / service
models
- Slower demand and faster local competition pressure
legacy brands.
- Not every closure equals a full China exit.
4. Capital and portfolio adjustments
- Investors are repricing China risk.
- Financial exposure can fall while industrial exposure
remains.
Who Is Leaving, Who Is Staying
8.
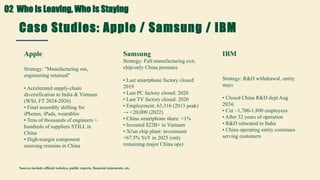
Case Studies: Apple/ Samsung / IBM
Apple
Strategy: "Manufacturing out,
engineering retained"
• Accelerated supply-chain
diversification to India & Vietnam
(WSJ, FT 2024-2026)
• Final assembly shifting for
iPhones, iPads, wearables
• Tens of thousands of engineers +
hundreds of suppliers STILL in
China
• High-margin component
sourcing remains in China
Samsung
Strategy: Full manufacturing exit,
chip-only China presence
• Last smartphone factory closed:
2019
• Last PC factory closed: 2020
• Last TV factory closed: 2020
• Employment: 63,316 (2013 peak)
→ <20,000 (2022)
• China smartphone share: <1%
• Invested $22B+ in Vietnam
• Xi'an chip plant: investment
+67.5% YoY in 2025 (only
remaining major China ops)
IBM
Strategy: R&D withdrawal, entity
stays
• Closed China R&D dept Aug
2024;
• Cut ~1,700-1,800 employees
• After 32 years of operation
• R&D relocated to India
• China operating entity continues
serving customers
Sources include official websites, public reports, financial statements, etc.
02 Who Is Leaving, Who Is Staying
9.
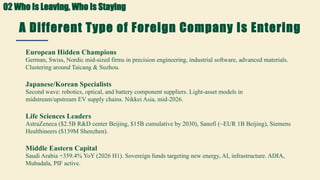
A Different Typeof Foreign Company Is Entering
Smaller, more specialized, more technology-intensive
European Hidden Champions
German, Swiss, Nordic mid-sized firms in precision engineering, industrial software, advanced materials.
Clustering around Taicang & Suzhou.
Japanese/Korean Specialists
Second wave: robotics, optical, and battery component suppliers. Light-asset models in
midstream/upstream EV supply chains. Nikkei Asia, mid-2026.
Life Sciences Leaders
AstraZeneca ($2.5B R&D center Beijing, $15B cumulative by 2030), Sanofi (~EUR 1B Beijing), Siemens
Healthineers ($139M Shenzhen).
Middle Eastern Capital
Saudi Arabia +359.4% YoY (2026 H1). Sovereign funds targeting new energy, AI, infrastructure. ADIA,
Mubadala, PIF active.
02 Who Is Leaving, Who Is Staying
10.
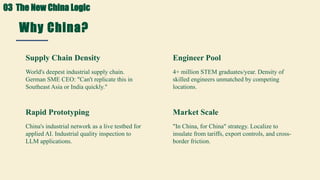
Why China?
Supply Chain/ Engineers / Prototype / Scale
Supply Chain Density
World's deepest industrial supply chain.
German SME CEO: "Can't replicate this in
Southeast Asia or India quickly."
Engineer Pool
4+ million STEM graduates/year. Density of
skilled engineers unmatched by competing
locations.
Rapid Prototyping
China's industrial network as a live testbed for
applied AI. Industrial quality inspection to
LLM applications.
Market Scale
"In China, for China" strategy. Localize to
insulate from tariffs, export controls, and cross-
border friction.
03 The New China Logic
11.
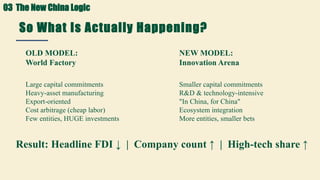
So What IsActually Happening?
The FDI Paradox Explained
OLD MODEL:
World Factory
Large capital commitments
Heavy-asset manufacturing
Export-oriented
Cost arbitrage (cheap labor)
Few entities, HUGE investments
NEW MODEL:
Innovation Arena
Smaller capital commitments
R&D & technology-intensive
"In China, for China"
Ecosystem integration
More entities, smaller bets
Result: Headline FDI ↓ | Company count ↑ | High-tech share ↑
03 The New China Logic
12.
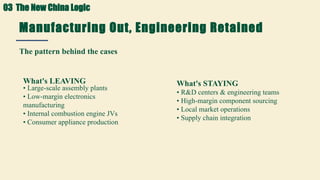
Manufacturing Out, EngineeringRetained
The pattern behind the cases
What's LEAVING
• Large-scale assembly plants
• Low-margin electronics
manufacturing
• Internal combustion engine JVs
• Consumer appliance production
What's STAYING
• R&D centers & engineering teams
• High-margin component sourcing
• Local market operations
• Supply chain integration
03 The New China Logic
13.
Risks
Key Concerns forForeign Investors
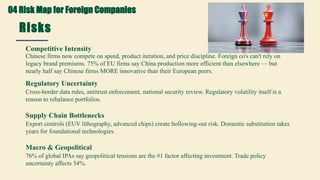
Competitive Intensity
Chinese firms now compete on speed, product iteration, and price discipline. Foreign co's can't rely on
legacy brand premiums. 75% of EU firms say China production more efficient than elsewhere — but
nearly half say Chinese firms MORE innovative than their European peers.
Regulatory Uncertainty
Cross-border data rules, antitrust enforcement, national security review. Regulatory volatility itself is a
reason to rebalance portfolios.
Supply Chain Bottlenecks
Export controls (EUV lithography, advanced chips) create hollowing-out risk. Domestic substitution takes
years for foundational technologies.
Macro & Geopolitical
76% of global IPAs say geopolitical tensions are the #1 factor affecting investment. Trade policy
uncertainty affects 54%.
04 Risk Map for Foreign Companies
14.
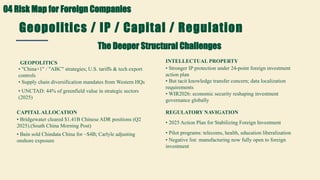
Geopolitics / IP/ Capital / Regulation
The Deeper Structural Challenges
GEOPOLITICS
• "China+1" / "ABC" strategies; U.S. tariffs & tech export
controls
• Supply chain diversification mandates from Western HQs
• UNCTAD: 44% of greenfield value in strategic sectors
(2025)
CAPITALALLOCATION
• Bridgewater cleared $1.41B Chinese ADR positions (Q2
2025).(South China Morning Post)
• Bain sold Chindata China for ~$4B; Carlyle adjusting
onshore exposure
INTELLECTUAL PROPERTY
• Stronger IP protection under 24-point foreign investment
action plan
• But tacit knowledge transfer concern; data localization
requirements
• WIR2026: economic security reshaping investment
governance globally
REGULATORY NAVIGATION
• 2025 Action Plan for Stabilizing Foreign Investment
• Pilot programs: telecoms, health, education liberalization
• Negative list: manufacturing now fully open to foreign
investment
04 Risk Map for Foreign Companies
15.
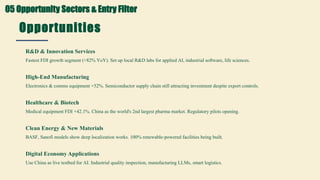
Opportunities
Sectors & Approaches
R&D& Innovation Services
Fastest FDI growth segment (+82% YoY). Set up local R&D labs for applied AI, industrial software, life sciences.
High-End Manufacturing
Electronics & comms equipment +52%. Semiconductor supply chain still attracting investment despite export controls.
Healthcare & Biotech
Medical equipment FDI +42.1%. China as the world's 2nd largest pharma market. Regulatory pilots opening.
Clean Energy & New Materials
BASF, Sanofi models show deep localization works. 100% renewable-powered facilities being built.
Digital Economy Applications
Use China as live testbed for AI. Industrial quality inspection, manufacturing LLMs, smart logistics.
05 Opportunity Sectors & Entry Filter
16.
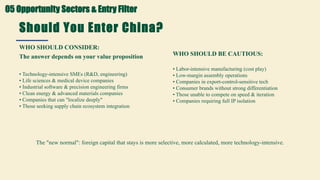
Should You EnterChina?
The answer depends on your value proposition
WHO SHOULD CONSIDER:
• Technology-intensive SMEs (R&D, engineering)
• Life sciences & medical device companies
• Industrial software & precision engineering firms
• Clean energy & advanced materials companies
• Companies that can "localize deeply"
• Those seeking supply chain ecosystem integration
WHO SHOULD BE CAUTIOUS:
• Labor-intensive manufacturing (cost play)
• Low-margin assembly operations
• Companies in export-control-sensitive tech
• Consumer brands without strong differentiation
• Those unable to compete on speed & iteration
• Companies requiring full IP isolation
The "new normal": foreign capital that stays is more selective, more calculated, more technology-intensive.
05 Opportunity Sectors & Entry Filter
17.
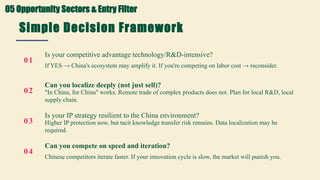
Simple Decision Framework
Fourquestions before entering China
01
Is your competitive advantage technology/R&D-intensive?
If YES → China's ecosystem may amplify it. If you're competing on labor cost → reconsider.
02
Can you localize deeply (not just sell)?
"In China, for China" works. Remote trade of complex products does not. Plan for local R&D, local
supply chain.
03
Is your IP strategy resilient to the China environment?
Higher IP protection now, but tacit knowledge transfer risk remains. Data localization may be
required.
04
Can you compete on speed and iteration?
Chinese competitors iterate faster. If your innovation cycle is slow, the market will punish you.
05 Opportunity Sectors & Entry Filter
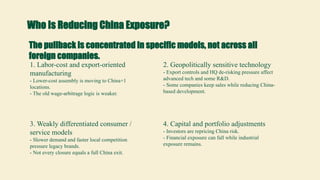
18.
Who Is ReducingChina Exposure?
The pullback is concentrated in specific models, not across all
foreign companies.
1. Labor-cost and export-oriented
manufacturing
- Lower-cost assembly is moving to China+1
locations.
- The old wage-arbitrage logic is weaker.
2. Geopolitically sensitive technology
- Export controls and HQ de-risking pressure affect
advanced tech and some R&D.
- Some companies keep sales while reducing China-
based development.
3. Weakly differentiated consumer /
service models
- Slower demand and faster local competition
pressure legacy brands.
- Not every closure equals a full China exit.
4. Capital and portfolio adjustments
- Investors are repricing China risk.
- Financial exposure can fall while industrial
exposure remains.
19.
Exploring China?
Best fit:
-Technology-intensive SMEs.
- Life sciences and medical devices.
- Industrial software, precision engineering,
clean energy, and advanced materials.
- Companies that need China supply-chain
or R&D ecosystem access.
All information is derived from official websites, publicly released reports, financial statements, and other public sources.
20.
Amanda Li
10+ yearsin finance | China tech & policy advisor
I help international clients navigate China's innovation
ecosystem, based in Shanghai.
AmandaLibusiness@hotmail.com
21.
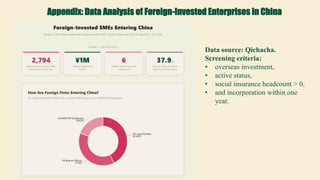
Data source: Qichacha.
Screeningcriteria:
• overseas investment,
• active status,
• social insurance headcount > 0,
• and incorporation within one
year.
Appendix: Data Analysis of Foreign-Invested Enterprises in China
22.
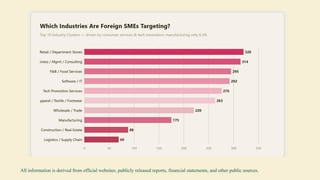
All information isderived from official websites, publicly released reports, financial statements, and other public sources.
23.
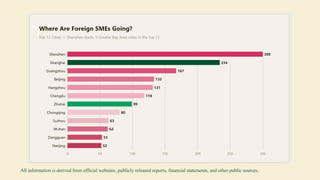
All information isderived from official websites, publicly released reports, financial statements, and other public sources.