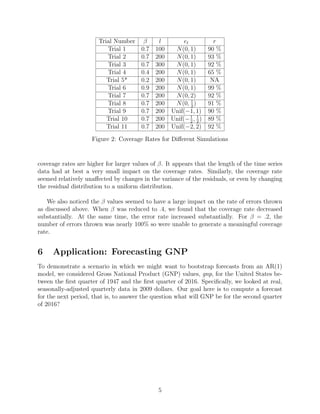
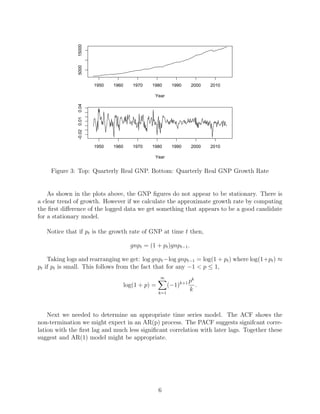
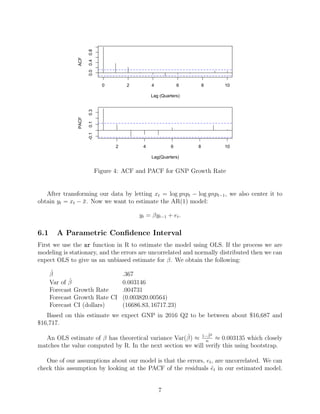
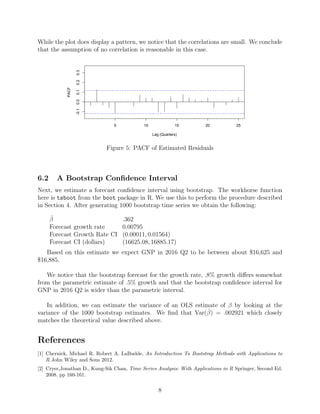
This document discusses using bootstrap methods to create confidence intervals for time series forecasts. It provides background on time series models and the autoregressive (AR) process. It then presents an algorithm for calculating a bootstrap confidence interval for forecasts from an AR(1) model. A simulation study compares coverage rates for bootstrap confidence intervals under different parameters. Finally, the method is applied to US Gross National Product data to forecast and construct confidence intervals.



![Inference in generative models using the Wasserstein distance [[INI]](https://cdn.slidesharecdn.com/ss_thumbnails/inewton-170706120746-thumbnail.jpg?width=640&height=640&fit=bounds)


