Credit and Debt Management
Instructions
Credit and Debt Management Pre-Survey
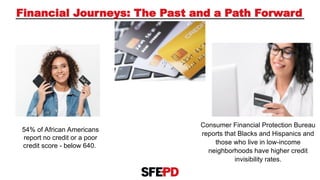
Financial Journeys: The Past and a Path Forward
54% of African Americans
report no credit or a poor
credit score - below 640.
Consumer Financial Protection Bureau
reports that Blacks and Hispanics and
those who live in low-income
neighborhoods have higher credit
invisibility rates.
CREDIT AND DEBT MANAGEMENT
LESSON OVERVIEW
In this lesson, you will learn:
•How to manage credit and debt
•How to increase your credit score
•How to identify actions that could damage your credit
•How to build and repair credit
•The use of credit cards
The Difference between Debt and Credit
• Debt is the total amount owed
(student debt, car loan, home
mortgage, etc.)
• Credit is the ability to borrow money
and repay the amount borrowed
(the amount borrowed is added to
your total debt)
•Credit gives you the ability to acquire goods and
services today, but pay later
•When you borrow you are making a promise to
repay, usually including interest
Credit is Important
The Three C’s
Capacity
• Your ability to pay your debts
Character
• Where credit is concerned, a person’s reputation for paying
bills when due. This is also referred to as your willingness and
ability to pay—or creditworthiness
Collateral
• An asset pledged to the creditor until the credit obligation is
paid. Example: If you own your home (or another car), it may
be used as collateral to secure a car loan
Credit Definitions
Pros vs. Cons of Credit
Cons
• Tempted to spend excessively
• May limit ability to save and invest
• Increase cost of item or service to
due interest charges
• Constant drainage of financial
resources
Pros
• Convenient
• Cover emergencies
• Build assets
• Build future credit
Economic
Benefits of
Good Credit
• Lower interest rates
• Availability of credit
Economic
Disadvantages
of Bad Credit
• Higher interest rates
• Limited sources of credit
• Limits employment opportunities
• Higher insurance premiums
• Difficulty in obtaining credit approval
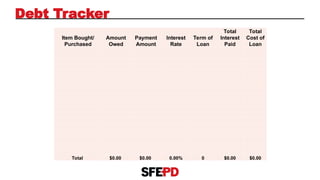
Debt Tracker
Item Bought/
Purchased
Amount
Owed
Payment
Amount
Interest
Rate
Term of
Loan
Total
Interest
Paid
Total
Cost of
Loan
Total $0.00 $0.00 0.00% 0 $0.00 $0.00
Financial Ratios
Debt-to-Limit
(divide outstanding credit card balance by credit card limit)
The percentage should be no more than 50% of the credit card
Limit. No more than 30% is better
Debt-to-Income
(divide total monthly payments by net monthly income)
A high debt-to-income ratio signals to lenders that you may not be able
to make payments on the loan that you are seeking. Should not exceed
20% of net monthly income
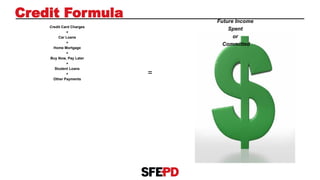
Credit Formula
Credit Card Charges
+
Car Loans
+
Home Mortgage
+
Buy Now, Pay Later
+
Student Loans
+
Other Payments
Future Income
Spent
or
Committed
=
Buy Now, Pay Later
• Buy Now, Pay Later (BNPL) is a type
of short-term financing that allows
consumers to make purchases and
pay for them at a future date, often
interest-free
• Also referred to as "point of sale
installment loans," BNPL
arrangements are becoming an
increasingly popular payment option,
especially when shopping online
Buy Now, Pay Later
Examples:
Affirm, Prosper, or Bread
Types of Credit Cards
• Bank Cards: Issued by banks, savings and loan associations, and credit
unions
• Charge Cards: “Travel and Entertainment” cards. Charges generally have to
be paid at the end of the month
Types of Credit Cards
• Retail Credit Cards: Issued by businesses such as department stores,
gasoline companies, and airlines. Credit is limited to goods or services
offered by the card issuer
• Secured Credit Cards: A credit card secured by a deposit in an
account held by the card issuer
• Affinity Cards: Affinity cards issued jointly by a lending institution and
some other organization such as charity or college alumni associations
How Finance Charges are Calculated
• Annual Percentage Rate (APR): This is the cost of credit,
expressed as a yearly rate
• Periodic Rate: This is the interest rate used to figure the finance
charge on your balance
• Annual Fee: Amount you pay to be a cardholder. Similar to a
membership fee
• Grace Period: This is the number of days you have to pay your bill
before finance charges begin to add up
• Finance Charges: Most lenders calculate finance charges using an
average daily account balance. Look for offers that use an
adjustable balance that subtracts your payment from your beginning
balance
Loan Agreements: Key Questions to Ask
• What is the specific loan payment?
• What is the principal and interest?
• How is the payment applied?
• What is an interest-only payment?
• What is a lump-sum payment?
•Is there a pre-payment penalty?​
​
•What is the interest rate or APR?​
​
•What are the consequences of default?​
​
•Under which State law will disputes be
resolved?
How to Repair Credit
Begin by requesting your credit report.
•This should be done at least twice a year – and at least six months
before a large purchase
•There are three major credit reporting agencies and many other
small ones
• The big three are Equifax, Experian & TransUnion
•These agencies may charge up to $8.00; however, the report is free
if you have been denied credit within the past 60 days
• www.annualcreditreport.com
How to Repair Credit
Look for errors in your report.
•If you see an error, fill out a dispute form or write a letter explaining what you think
is wrong. Attach any supporting documents
Look for any old information.
•Credit information older than 7 ½ years
•Bankruptcy information older than 10 years
How to Repair Credit
•Contact lenders
•Establish new payment arrangements that you can afford
•Pay consistently and on time
•Use tax refunds or any lump sums available to reduce
outstanding debts
• Leave your credit cards at home
• Pay off credit card balances each
month
• As you pay off debts (either lowest
balance or highest interest), set new
payment amounts for the remaining
debts
• Comparison shop for all large
purchases
Ways to Limit your Credit Card Debt
If you have difficulty maintaining credit:
How to Maintain/Improve Your Credit
• Limit spending to needs, not wants
• Remember that credit cards are loans
• Keep a low balance
• Pay loans first (do not make late payments)
• Charge less than the maximum amount available (no more than 30% of
credit limit)
• Keep a record of your purchases to avoid overspending
• Decline any credit card limit increases
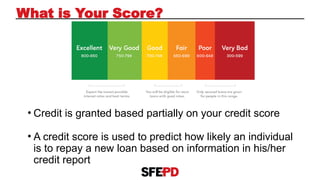
• Credit is granted based partially on your credit score
• A credit score is used to predict how likely an individual
is to repay a new loan based on information in his/her
credit report
What is Your Score?
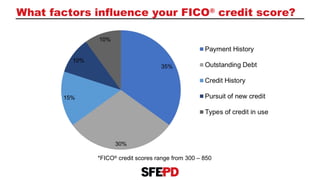
What factors influence your FICO®
credit score?
*FICO®
credit scores range from 300 – 850
• Mortgage lenders
• Automobile finance companies
• Banks and other financial institutions
• Potential employers
• Car insurance companies
• Landlords
• Anyone who has a need to understand how you handle credit
Who Uses Your Credit Score?
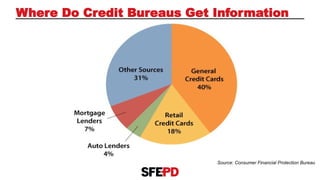
Where Do Credit Bureaus Get Information
Source: Consumer Financial Protection Bureau
•Reduce outstanding debt
•Pay loans consistently and on time
•Pay off debt rather than moving it around
•Apply for credit only when you need it
How to Improve Your Credit Score?
• Payment history
• Amounts owed
• Length of credit history
• Types of credit
• Accounts referred to collection companies, including medical
past due medical bills
• Charge-offs/settlements
• Repossessed vehicles
• Legal actions filed in courts to force payments of debts
What’s in Your Credit Report?
• Race
• Religion
• Medical information
• Driving or criminal records
• Political preference
• Income, savings and checking account information
What’s NOT in Your Credit Report?
Take Action
When looking to use credit:
1.Get a free copy of your credit report at www.annualcreditreport.com.
2.Check for errors that could impact your credit application/credit score.
3.Correct all errors before you apply for any type of loan. If you see an error, fill out a
dispute form or write a letter explaining what you think is wrong. Attach any
supporting documents.
4.Check your credit score. You can purchase your score from any of the credit reporting
agencies or myfico.com. Credit scores range from 300-850. The higher the credit score,
the lower the interest rate on your loan. You should target a credit score of 750.
The factors that affect your credit score are payment history, outstanding debt, credit
history, the pursuit of new credit, and types of credit in use.
Take Action
When looking to reduce debt:
To reduce debt, look at your short-term debt like credit cards -
Ask yourself before using a credit card:
a. Do I have the cash to pay for this?
b. Do I really need this item or service?
c. Is the item or service of lasting value?
d. Do I have a payment plan to cover this item or service?
e. What is the total cost of this item or service if I don’t pay for it in full the first
month? It will cost more than the purchase price if you pay over time.
Financial Literacy Certificate
Upon completion, individuals will receive a digital badge
credential issued through Credly, an industry-leading
credentialing organization.
Our online certificate consists of eight modules:
•Budgeting, Values, & Financial Goal Setting
•Credit & Debt Management
•Student Loan Management
•Insurance
•Homeownership
•Investor Education
•Retirement Planning
•Estate Planning
Scan to register
or visit:
sfepd.org/flc
Peer Virtual Financial Coaching Sessions
• Have money questions?
• Need assistance setting up
a budget/spending plan?
• Questions about credit or
student loans?
Scan to
register for a
session
or visit:
https://bit.ly/3MkSaOl
Open the Play store or App store
Search "QR Code Reader/QR Code Scanner"
Download the app
Instructions
Credit and Debt Management Post-Survey
Thank You!