Financial Services Industry Training


                   Credit Card Issuers
                     An Overview of the Credit Card Business


    Saunders Learning Group, LLC
    Saunders Learning Group, LLC, Andover, KS
Training from Saunders Learning Group
     Saunders Learning Group provides a variety
     of training programs, workshops and
     seminars targeted to the financial services
     industry.

     Programs are available in a wide range of
     topics, and we are specialists in developing
     custom programs that are targeted to your
     needs.

     Contact the founder, Floyd Saunders at
     316-680-6482 or at
     floyd@floydsaunders.com for more
     information.


       Saunders Learning Group, LLC, Andover, KS
1
Topics
1.    Role and Function of Credit Card Issuers
2.    Meaning and Definition
3.    Types of Credit Cards
4.    How a Credit Card Company Makes Money
5.    Credit Card Transaction Processing Steps
6.    Market Share of Major Credit Card Companies


      Saunders Learning Group, LLC, Andover, KS     Slide 2
Module 1
   Role and Function of Credit
          Card Issuers


Saunders Learning Group, LLC
Saunders Learning Group, LLC, Andover, KS
Credit Card Issuers & Associations

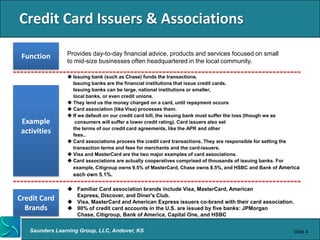
 Function       Provides day-to-day financial advice, products and services focused on small
                to mid-size businesses often headquartered in the local community.

                 Issuing bank (such as Chase) funds the transactions.
                  Issuing banks are the financial institutions that issue credit cards.
                  Issuing banks can be large, national institutions or smaller,
                  local banks, or even credit unions.
                 They lend us the money charged on a card, until repayment occurs
                 Card association (like Visa) processes them.
                 If we default on our credit card bill, the issuing bank must suffer the loss (though we as
 Example           consumers will suffer a lower credit rating). Card issuers also set
                  the terms of our credit card agreements, like the APR and other
 activities       fees..
                 Card associations process the credit card transactions. They are responsible for setting the
                  transaction terms and fees for merchants and the card-issuers.
                 Visa and MasterCard are the two major examples of card associations.
                 Card associations are actually cooperatives comprised of thousands of issuing banks. For
                  example, Citigroup owns 9.5% of MasterCard, Chase owns 8.5%, and HSBC and Bank of America
                  each own 5.1%.

                 Familiar Card association brands include Visa, MasterCard, American
                  Express, Discover, and Diner's Club.
Credit Card      Visa, MasterCard and American Express issuers co-brand with their card association.
  Brands         90% of credit card accounts in the U.S. are issued by five banks: JPMorgan
                  Chase, Citigroup, Bank of America, Capital One, and HSBC

   Saunders Learning Group, LLC, Andover, KS                                                               Slide 4
Module 2
          Credit Card Issuers Meanings
                 and Definitions


          Saunders Learning Group, LLC
          Saunders Learning Group, LLC, Andover, KS
Slide 5
Meaning and Definition
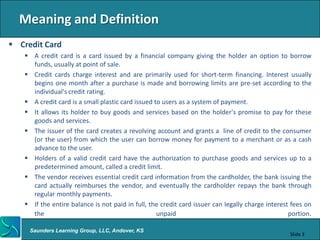
 Credit Card
    A credit card is a card issued by a financial company giving the holder an option to borrow
     funds, usually at point of sale.
    Credit cards charge interest and are primarily used for short-term financing. Interest usually
     begins one month after a purchase is made and borrowing limits are pre-set according to the
     individual's credit rating.
    A credit card is a small plastic card issued to users as a system of payment.
    It allows its holder to buy goods and services based on the holder's promise to pay for these
     goods and services.
    The issuer of the card creates a revolving account and grants a line of credit to the consumer
     (or the user) from which the user can borrow money for payment to a merchant or as a cash
     advance to the user.
    Holders of a valid credit card have the authorization to purchase goods and services up to a
     predetermined amount, called a credit limit.
    The vendor receives essential credit card information from the cardholder, the bank issuing the
     card actually reimburses the vendor, and eventually the cardholder repays the bank through
     regular monthly payments.
    If the entire balance is not paid in full, the credit card issuer can legally charge interest fees on
     the                                           unpaid                                         portion.

     Saunders Learning Group, LLC, Andover, KS
                                                                                                  Slide 3
Meaning and Definition
 Credit Card Issuer

     A credit card issuer is a bank or credit union that offers credit cards.
     The credit card issuer makes the credit limit available to cardholders and is
      responsible for sending payments to merchants for purchases made with
      credit cards from that bank.
     Also called member banks. Chase and Citi are examples of credit card issuers.
     Credit card issuers can't issue credit cards all by themselves, they need the
      help of payment processing networks like Visa and MasterCard (a credit card
      association).
     However, American Express and Discover act as both the credit card issuers
      and the payment processing network.


  Saunders Learning Group, LLC, Andover, KS
                                                                                Slide 4
Meaning and Definition
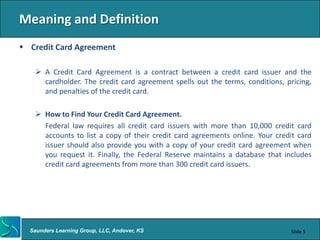
 Credit Card Agreement

    A Credit Card Agreement is a contract between a credit card issuer and the
     cardholder. The credit card agreement spells out the terms, conditions, pricing,
     and penalties of the credit card.

    How to Find Your Credit Card Agreement.
     Federal law requires all credit card issuers with more than 10,000 credit card
     accounts to list a copy of their credit card agreements online. Your credit card
     issuer should also provide you with a copy of your credit card agreement when
     you request it. Finally, the Federal Reserve maintains a database that includes
     credit card agreements from more than 300 credit card issuers.


  Saunders Learning Group, LLC, Andover, KS                                    Slide 5
Meaning and Definition
The credit card agreement will list:
     The annual percentage rate for each type of balance that can be carried – purchases,
      balance transfers, and cash advances.
     Finance charge information including the minimum finance charge and the finance charge
      calculation method.
     Grace Period.
     Credit Card Fees.
     Credit Limit and information about how your credit card issuer can change it .
     Details about using your credit card in another country.
     Options for paying your credit card balance.
     How your credit card is reported to the credit bureaus.
     How your information is shared or kept private.
     Changes the credit card issuer can make to your account.
     What constitutes default and what happens if you default.
     How to handle a lost credit card.
     How to close your account.
     How to handle disputes with the credit card issuer .
     The legal body who enforces the credit card agreement.


   Saunders Learning Group, LLC, Andover, KS                                          Slide 6
Module 3
              Types of Credit Card


Saunders Learning Group, LLC
Saunders Learning Group, LLC, Andover, KS
Types of Credit Cards
Since each person's financial needs are different, it makes sense that there are
different types of credit cards. Before you apply for a credit card, become familiar
with the various kinds of credit cards to make sure you're choosing the best credit
card for you.

Standard Credit Cards
        The most common type of credit card allows you to have a revolving balance
        up to a certain credit limit. Credit is used up when you make a purchase and
        made available again once you've made a payment. A finance charge is
        applied to outstanding balances at the end of each month. Credit cards have
        a minimum payment that must be paid by a certain due date to avoid late-
        payment penalties.

        Standard credit cards are also called "plain-vanilla" credit cards because they
        offer no frills or rewards. They're also uncomplicated and relatively easy to
        understand.


  Saunders Learning Group, LLC, Andover, KS                                         Slide 7
Types of Credit Cards
                   Premium Credit Cards
                   • These cards offer incentives and benefits beyond that of a regular credit card.
                     Examples of premium credit cards are Gold and Platinum cards that offer cash
                     back, reward points, travel upgrades, and other rewards to cardholders.
                     Premium cards can have higher fees and usually have minimum income and
                     credit score requirements.

                   Charge Cards
                   • Charge cards do not have a preset spending limit and balances must be paid in
                     full at the end of each month. Charge cards typically do not have a finance
                     charge or minimum payment since the balance is to be paid in full. Late
                     payments are subject to a fee, charge restrictions, or card cancellation
                     depending on your card agreement.

                   Limited Purpose Card
                   • Limited purpose credit cards can only be used at specific locations. Limited
                     purpose cards are used like credit cards with a minimum payment and finance
                     charge. Store credit cards and gas credit cards are examples of limited purpose
                     credit cards.


 Saunders Learning Group, LLC, Andover, KS
                                                                                                  Slide 8
Types of Credit Cards
                    Secured Credit Cards
                    • Secured credit cards are an option for those without a credit history or
                      those with blemished credit. Secured cards require a security deposit to
                      be placed on the card. The credit limit on a secured credit card is equal
                      typically at least the deposit made on the card, but it could be more in
                      some cases. You're still expected to make monthly payments on your
                      secured credit card balance.


                    Prepaid Cards
                    • Prepaid cards require the cardholder to load money onto the card before
                      the card can be used. Purchases are withdrawn from the card's balance.
                      The spending limit does not renew until more money is loaded onto the
                      card. Prepaid cards do not have finance charges or minimum payments
                      since the balance is withdrawn from the deposit. These cards are not
                      actually credit cards and they don't directly help you rebuild your credit
                      score. Prepaid cards are similar to debit cards, but are not tied to a
                      checking account.


 Saunders Learning Group, LLC, Andover, KS
                                                                                            Slide 9
Types of Credit Cards
                     Business Credit Cards
                     • Business credit cards are designed specifically for business use. They provide
                       business owners with an easy method of keeping business and personal
                       transactions separate. There are standard business credit and charge cards
                       available.


                     Rewards Credit Card
                     • Rewards credit cards give you a bonus based on your card usage. Choosing the
                       right rewards credit card means picking one that gives rewards you can use. With a
                       good rewards card, you can out earn any costs, e.g. annual fee, without too much
                       hassle.


                     Balance Transfer Credit Cards
                     • Balance transfer credit cards are good for combining several credit card balances
                       or for taking advantage of a lower interest rate. Not only should you consider the
                       introductory balance transfer interest rate, but also how long the rate lasts and the
                       rate that applies once the promotional rate expires.


 Saunders Learning Group, LLC, Andover, KS                                                         Slide 10
Types of Credit Cards


    Student Credit Cards                      Travel and Entertainment                 Zero Percent Interest Credit
    •Student credit cards are designed        Credit Cards                             Cards
     for college-aged consumers who are       •A credit card that can be used to       •As the name indicates, zero percent
     just starting out with credit. These      cover travelling expenses and for        credit cards do not require the
     cards typically give credit to college    your enjoyment/entertainment. An         credit card owner to make any kind
     students who lack a credit history.       example of a T&E card is "Diners         of interest on their shopping. You
     Not every credit card with "student"      Club." It can only be used at certain    could utilize your credit card and
     in the title is actually good for         restraunts which would constitute        also purchase anything you desire
     students. So, if you're on the            "entertainment.“                         and pay only the monthly minimum
     market for one of these cards, make                                                requirement.
     sure you pay attention to the credit
     card terms.


 Saunders Learning Group, LLC, Andover, KS
                                                                                                                              Slide 11
Module 4
  How Credit Card Companies
        Make Money


Saunders Learning Group, LLC
Saunders Learning Group, LLC, Andover, KS
How a Credit Card Issuers Makes Money
 Credit card issuers (most often a bank or credit union) receive revenue from
  fees paid by stores that accept their cards and by consumers that use the
  cards, and from interest charged consumers on unpaid balances.

 Credit Card Companies make money in a number of ways like :
     Fees (annual fee, over limit, past due, etc)
     Interest on the revolving loan if a credit card balance is not paid in full each
      month.
     The card Issuer [the bank that issued the card and/or the issuer network ie: Visa,
      MS, American Express, JCB etc] makes a percentage of each item you purchase
      from the merchant who accepts your credit card. These rates range from 1% to
      4% of each purchase.
     Last, the cardholder can make additional money through other means, such as
      selling your name to a mailing list or sending advertisements in your monthly
      bill.   (Due     to    regulation,    this   is   becoming      less   frequent)


  Saunders Learning Group, LLC, Andover, KS                                      Slide 16
Module 5
 Credit Card Processing Steps


Saunders Learning Group, LLC
Saunders Learning Group, LLC, Andover, KS
Credit Card Authorization Process Flow


 Saunders Learning Group, LLC, Andover, KS   Slide 19
Credit Card Transaction Processing Steps

 Step 1
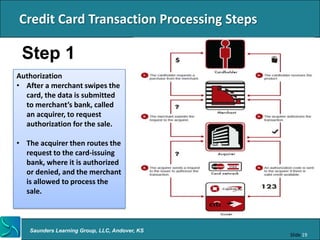
Authorization
• After a merchant swipes the
  card, the data is submitted
  to merchant’s bank, called
  an acquirer, to request
  authorization for the sale.

• The acquirer then routes the
  request to the card-issuing
  bank, where it is authorized
  or denied, and the merchant
  is allowed to process the
  sale.


   Saunders Learning Group, LLC, Andover, KS
                                               Slide 19
Credit Card Transaction Processing Steps

   Step2
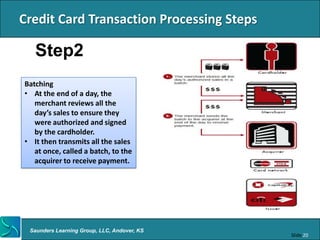
Batching
• At the end of a day, the
   merchant reviews all the
   day’s sales to ensure they
   were authorized and signed
   by the cardholder.
• It then transmits all the sales
   at once, called a batch, to the
   acquirer to receive payment.


 Saunders Learning Group, LLC, Andover, KS
                                             Slide 20
Credit Card Transaction Processing Steps

   Step3
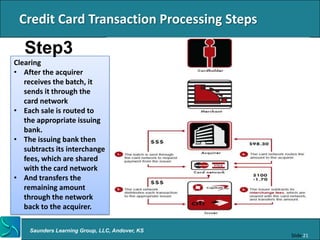
Clearing
• After the acquirer
   receives the batch, it
   sends it through the
   card network
• Each sale is routed to
   the appropriate issuing
   bank.
• The issuing bank then
   subtracts its interchange
   fees, which are shared
   with the card network
• And transfers the
   remaining amount
   through the network
   back to the acquirer.

    Saunders Learning Group, LLC, Andover, KS
                                                Slide 21
Credit Card Transaction Processing Steps

Step4
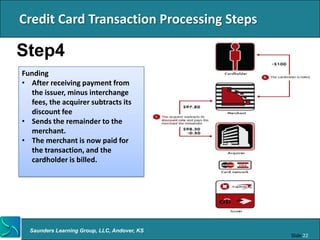
Funding
• After receiving payment from
  the issuer, minus interchange
  fees, the acquirer subtracts its
  discount fee
• Sends the remainder to the
  merchant.
• The merchant is now paid for
  the transaction, and the
  cardholder is billed.


  Saunders Learning Group, LLC, Andover, KS
                                              Slide 22
Credit Card Transaction Processing Steps
 Glossary

    Acquirer: A bank that processes and settles a merchant's credit card
     transactions with the help of a card issuer.
    Cardholder: The owner of a card that is used to make credit card purchases.
    Card network: Visa, MasterCard or other networks that act as an intermediary
     between an acquirer and an issuer to authorize credit card transactions.
    Discount fee: A processing fee paid by merchants to acquirers to cover the
     cost of processing credit cards.
    Interchange fee: A charge paid by merchants to a credit card issuer and a card
     network as a fee for accepting credit cards. They generally range from 1 to 3
     percent.
    Issuer: An financial institution, bank, credit union or company that issues or
     helps issue cards to cardholders.


  Saunders Learning Group, LLC, Andover, KS
Credit Card Transaction Processing Steps
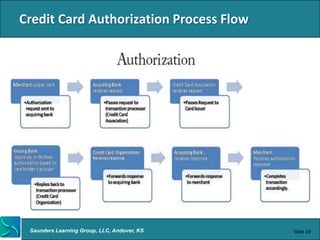
1. Merchant calculates the amount of purchase and asks buyer for payment .
2. Buyer presents merchant with a credit card.
3. Merchant runs credit card through the point of sale unit.
     The amount of the sale is either hand-entered or transmitted by the cash
      register.
4. Merchant transmits the credit card data and sales amount with a request
   for authorization of the sale to their acquiring bank.
5. The acquiring bank that processes the transaction, routes the
   authorization request to the card-issuing bank.
     The credit card number identifies type of card, issuing bank, and the
      cardholder's account.
6. If the cardholder has enough credit in their account to cover the sale, the
   issuing bank authorizes the transaction and generates an authorization
   code.
     This code is sent back to the acquiring bank.
     The issuing bank puts a hold on the cardholder's account for the amount of
      the sale. Note that the cardholder's account has not been actually charged
      yet.
    Saunders Learning Group, LLC, Andover, KS
Credit Card Transaction Processing Steps
7. The acquiring bank processing the transaction, and then sends the approval or
   denial code to the merchant's point of sale unit.
     • Each point of sale device has a separate terminal ID for credit card processors to be able
       to route data back to that particular unit.
8. A sale draft, or slip, is printed out by the point of sale unit or cash register.
     • The merchant asks the buyer to sign the sale draft, which obligates them to reimburse
       the card-issuing bank for the amount of the sale.
9. At a later time, probably that night when the store is closing up, the merchant
   reviews all the authorizations stored in the point of sale unit against the signed
   sales drafts.
     • When all the credit card authorizations have been verified to match the actual sales
       drafts, the merchant will capture, or transmit, the data on each authorized credit card
       transaction to the acquiring bank for deposit.
10. The acquiring bank performs what is called an interchange for each sales draft,
    with the appropriate card-issuing bank.
     • The card-issuing bank transfers the amount of the sales draft, minus an interchange fee
       to the acquiring bank
11. The acquiring bank then deposits the amount of the all the sales drafts submitted
    by the merchant, less a discount fee, into the merchant's bank account.


  Saunders Learning Group, LLC, Andover, KS                                                 Slide 25
Module 6
Major Credit Card Companies
       Market Share


Saunders Learning Group, LLC
Saunders Learning Group, LLC, Andover, KS
Visa
                Provides credit and debt card processing services to
Function         member banks, merchants and businesses.

                Credit Card Processing - Visa operates VisaNet,
                    the world’s largest retail electronic payments processing network, handling
                      150 million transactions every day.
Example             more than $5.9 trillion in global consumer spend is transacted annually.
                    includes: core transaction processing, debt card transactions, risk
product               management and information-based services.
  and               Services tailored to individual countries or regions and serve the needs of
Services              financial institutions, governments, businesses, merchants and consumers
                      around the globe.
                    Every day, VisaNet connects up to 1.93 billion cards, millions of acceptance
                      locations, 1.9 million ATMs and 15,200 financial institutions.
                      http://corporate.visa.com/about-visa/technology-index.shtml
                Risk Management Services
                    sophisticated risk management services that protect issuers, acquirers, and
                      merchants from losses due to fraud, theft or unauthorized use.
                    include transaction risk scoring, innovative data encryption techniques and
                      transaction alerts and notifications
 Share of
the Market     Visa’s share of worldwide purchase transactions on both credit and debit
               cards as of May 2012 was 64.67 percent, down 1.1 % from 2011.


   Saunders Learning Group, LLC, Andover, KS                                                   Slide 28
MasterCard
 Function            Provides credit, debit, prepaid, commercial credits for
                     consumers via member banks and payment processing to merchants.


                 Payment products include credit cards, debit card programs, e-commerce solutions, prepaid
                  cards, loyalty and reward solutions and comprehensive cardholder benefits and services.

                 MasterCard card products are provided to financial institutions, merchants, and businesses.

 Example         CARD PAYMENT SOLUTIONS
                      Manages and monitor travel and entertainment expenses
 product         MASTERCARD® SMART DATA
   and                Smart data suite delivers tools to leverage financial data, customize transaction Information
                        and establish spending controls.
 Services        MASTERCARD PURCHASE CONTROL™
                      Purchase Controls are a simple, secure, and effective way to manage business xpenses.


 Share of         MasterCard’s market share expanded by almost half of a percentage
the Market         point to 25.57 percent in 2011.


    Saunders Learning Group, LLC, Andover, KS                                                                          Slide 29
Discover

                  Provides consumers with credit cards
 Function          and a range of banking products. Unlike MasterCard and Visa is not an
                   association, and does it own payment processing.


                  Offers Cashback, miles, business and student cards with a 5% cashback bonus
 Example           applied to charges.
 Products         Offers savings and retirement plan accounts including Money Market, Online
   and             Savings, Certificates of Deposit, and IRA CD.
 Services         Provides student loans and personal loans via online application process
                  Also provides gift cards, identify theft protection and a credit score tracker.


                 Discover currently has about 9% of the market share for credit cards and 54.4 million
 Share of         customers.
the Market

   Saunders Learning Group, LLC, Andover, KS                                                     Slide 30
American Express

                  Provides both credit and charge cards for
 Function          individuals and corporations.
                   In addition, it’s financial services division offers Private Banking services to high net-
                   worth clients and a range of international cask management, payment and trade
                   services to banks. Unlike MasterCard and Visa is not an association, and does it own
                   payment processing.

                  American Express is multinational financial services corporation best known for credit
                   cards, charge cards and traveler’s cheque businesses.
 Example          Offers a range of charge cards with different levels of services, including
 Products                    Green Card
   and                       Gold Card
 Services                    Platinum Card
                             The “Blue” card
                             Centurion (or “Black) Card
                  Offers co-branded credit cards with Airlines, hotels and retailers.


                 American Express currently has about 8% of the market share for credit cards and 50
 Share of         million customers.
the Market

   Saunders Learning Group, LLC, Andover, KS                                                            Slide 31
Thank You !


Saunders Learning Group, LLC
Saunders Learning Group, LLC, Andover, KS
Questions


 Saunders Learning Group, LLC, Andover, KS
Summary of Book
                                              Figuring Out Wall Street Consumer’s Guide
                                              To Financial Markets
                                              By Floyd Saunders
                                              Publisher: Saunders Learning Group

                                              ISBN: 978-0-9824019-0-3
                                              available from Amazon, B&N, and
                                              http://www.figuringout wallstreet.com
                                              or www.floydsaunders.com
                                              Author Contact
                                              email: floyd@floydsaunders.com
                                              Blog: www/money/floydsaunders.com
                                              Twitter @floydsaunders
                                              Facebook: Figuring Out Wall Street
                                              Sideshare: http://www.slideshare.net/FloydSaunders


                                       Book summary: From bank failures to home foreclosures and panic around the
                                       world, Figuring Out Wall Street, is the concise guide to help everyone understand
                                       how this latest crisis happened, who was responsible and what to do now to
                                       restore our financial systems. Written in an easy to understand manner, even the
                                       most complex financial concepts are easy to digest. This book provides help to
                                       monitor investments with a review of investment products, financial regulators
                                       and economic indicators. Learn how the stock market exchanges work and the
                                       world of investment banking, hedge funds, venture capital and private equity.
                                       Every chapter includes action plans for investing.


 Saunders Learning Group, LLC, Andover, KS
About the Author
                                                Floyd Saunders has worked on Wall
                                                 Street with both Bank of America and
                                                 JPMorgan, where is was a vice
                                                 president in global financial systems.
                                                 He has worked across the industry in
                                                 retail, commercial, and investment
                                                 banking.
                                                He has taught courses in Money and
                                                 Banking and extensively for the
                                                 American Institute of Banking and
                                                 various colleges.
                                                As a consultant, he developed and
                                                 taught a wide range of banking and
                                                 investing courses.
                                                 He authored three programs for the
                                                 American Bankers Association: Banking
                                                 on Mutual Funds and Annuities,
                                                 Introduction to Securities Markets and
                                                 Investing in Securities.


 Saunders Learning Group, LLC, Andover, KS