© Consumer Intelligence 2015
Slide: 1
Slide No: 1
© Consumer Intelligence 2015
Matthew Green
Key Account Director
Consumer Preferences for
Connected Car Insurance
© Consumer Intelligence 2015
Slide: 2
Slide No: 2
© Consumer Intelligence 2015
Source: Voice-of-the-Customer Motor Insurance survey, n=5,890, May ‘15
“What innovative idea
would you suggest to
motor insurance
providers to improve
their service?”
© Consumer Intelligence 2015
Slide: 3
Slide No: 3
© Consumer Intelligence 2015
KEY FINDING NO 4.:
Harness the potential from existing
technology
Source: Voice-of-the-Customer Motor Insurance survey, n=5,890, May ‘15
!KEY
FINDING
Harness the potential from existing
and emerging technologies
© Consumer Intelligence 2015
Slide: 4
Slide No: 4
© Consumer Intelligence 2015
The key question for 2016
?
What innovative things
has the insurance industry
done with technology to
reach out to consumers
© Consumer Intelligence 2015
Slide: 5
Slide No: 5
© Consumer Intelligence 2015
Slide: 6
Slide No: 6
© Consumer Intelligence 2015
monitor
score
reward
© Consumer Intelligence 2015
Slide: 7
Slide No: 7
© Consumer Intelligence 2015
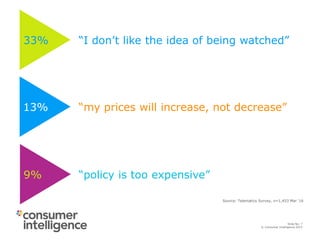
Source: Telematics Survey, n=1,453 Mar ‘16
“I don’t like the idea of being watched”
“policy is too expensive”
“my prices will increase, not decrease”
33%
13%
9%
© Consumer Intelligence 2015
Slide: 8
Slide No: 8
© Consumer Intelligence 2015
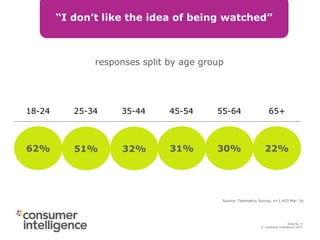
“I don’t like the idea of being watched”
18-24 25-34 35-44 45-54 55-64 65+
responses split by age group
Source: Telematics Survey, n=1,453 Mar ‘16
51% 32% 31% 30% 22%62%
© Consumer Intelligence 2015
Slide: 9
Slide No: 9
© Consumer Intelligence 2015
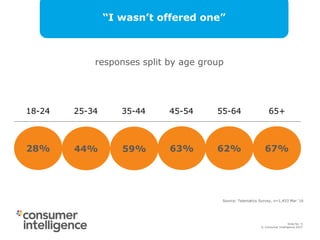
“I wasn’t offered one”
18-24 25-34 35-44 45-54 55-64 65+
responses split by age group
Source: Telematics Survey, n=1,453 Mar ‘16
44% 59% 63% 62% 67%28%
© Consumer Intelligence 2015
Slide: 10
Slide No: 10
© Consumer Intelligence 2015
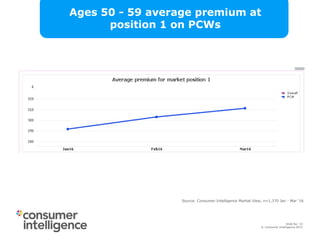
Source: Consumer Intelligence Market View, n=1,370 Jan - Mar ‘16
Ages 50 - 59 average premium at
position 1 on PCWs
© Consumer Intelligence 2015
Slide: 11
Slide No: 11
© Consumer Intelligence 2015
Telematics is insurer driven
Telematics is not needed
Telematics is CREEPY!
© Consumer Intelligence 2015
Slide: 12
Slide No: 12
© Consumer Intelligence 2015
This presentation is BORING!
© Consumer Intelligence 2015
Slide: 13
Slide No: 13
© Consumer Intelligence 2015
Slide: 14
Slide No: 14
© Consumer Intelligence 2015
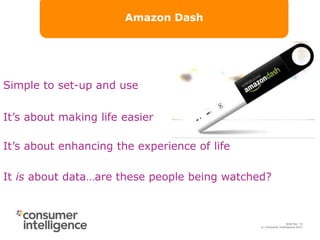
Simple to set-up and use
It’s about enhancing the experience of life
It is about data…are these people being watched?
Amazon Dash
It’s about making life easier
© Consumer Intelligence 2015
Slide: 15
Slide No: 15
© Consumer Intelligence 2015
Please…take my personal data!
© Consumer Intelligence 2015
Slide: 16
Slide No: 16
© Consumer Intelligence 2015
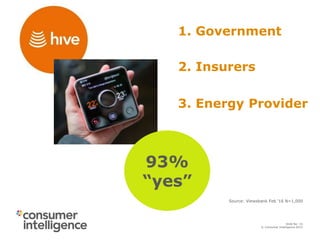
1. Government
Source: Viewsbank Feb ‘16 N=1,000
93%
“yes”
2. Insurers
3. Energy Provider
© Consumer Intelligence 2015
Slide: 17
Slide No: 17
© Consumer Intelligence 2015
KEY FINDING NO 4.:
Harness the potential from existing
technology
Source: Voice-of-the-Customer Motor Insurance survey, n=5,890, May ‘15
Potential from existing and emerging technologies
Develop agile, flexible products
Price isn’t everything – experience is
Key findings in full
© Consumer Intelligence 2015
Slide: 18
Slide No: 18
© Consumer Intelligence 2015
Matthew Green
Key Account Director
Consumer Preferences for
Connected Car Insurance
The Connected Car: Making
Consumers Lives Easier
© Consumer Intelligence 2015
Slide: 19
Slide No: 19
© Consumer Intelligence 2015
Slide: 20
Slide No: 20
© Consumer Intelligence 2015
Hum by Verizon
There when you need it, not intrusive
Simple to install, simple to use
Peace of mind; this is a life enabler
It is about data…what are the opportunities?
© Consumer Intelligence 2015
Slide: 21
Slide No: 21
© Consumer Intelligence 2015
What solution will you
offer to make consumers
lives easier?
© Consumer Intelligence 2015
Slide: 22
Slide No: 22
© Consumer Intelligence 2015
Matthew Green
Key Account Director
Thank you!