Find my Professional handles below:
LinkedIn - https://www.linkedin.com/in/chandana-aligeri-venkata-922569285/
Github - https://github.com/Chandana-pixel
Gmail - chandanawork97@gmail.com
(https://mail.google.com/mail/?view=cm&fs=1&to=chandanawork97@gmail.com)
AR(p) Model – Summary
1. Introduction
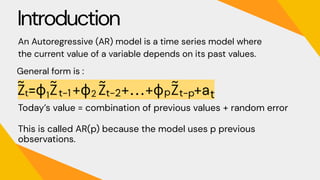
An Autoregressive (AR) model is a time series forecasting model in which the current value depends on its previous values. If the model uses p previous observations, it is called an AR(p) model.
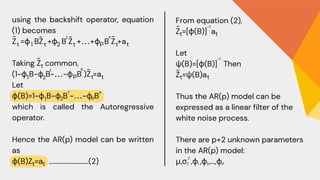
General equation: Zt=ϕ1Zt−1+ϕ2Zt−2+⋯+ϕpZt−p+at
2. Components of AR(p)
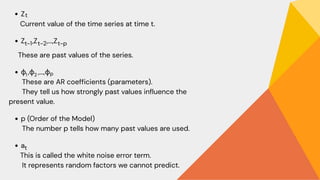
Zt – Current value of the time series.
Zt−1, Zt−2, …,Zt−p – Past values.
ϕ1, ϕ2, …,ϕp – Autoregressive coefficients showing the influence of past values.
p – Order of the model (number of previous observations used).
at – White noise (random error).
3. Derivation
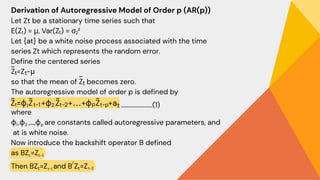
The presentation derives the AR(p) model by:
Assuming a stationary time series.
Centering the series by subtracting its mean.
Introducing the backshift operator (B).
Expressing the model using the autoregressive operator:
ϕ(B)Zt=at
Showing that the AR(p) model acts as a linear filter of white noise.
4. Properties
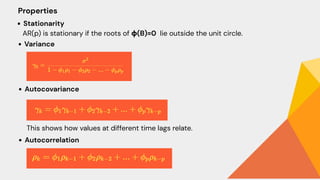
Stationarity: The roots of ϕ(B)=0 must lie outside the unit circle.
Has defined variance, autocovariance, and autocorrelation, which describe the relationship between observations at different time lags.
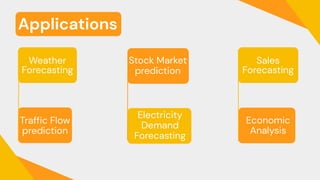
5. Applications
The AR(p) model is used for:
Weather forecasting
Stock market prediction
Sales forecasting
Electricity demand forecasting
Traffic flow prediction
Economic analysis
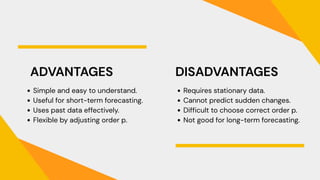
6. Advantages
Simple and easy to understand.
Effective for short-term forecasting.
Uses historical data efficiently.
Flexible by changing the order p.
7. Disadvantages
Requires stationary data.
Cannot capture sudden changes.
Selecting the correct order p can be difficult.
Not suitable for long-term forecasting.
8. Example
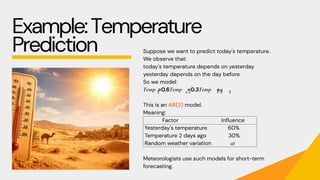
The PPT explains temperature prediction using an AR(2) model:
Yesterday's temperature contributes 60%.
Temperature from two days ago contributes 30%.
Remaining variation is due to random error (at).
This demonstrates how AR models predict future values using previous observations.
9. Conclusion
The AR(p) model is a time series forecasting model that predicts the current value using the previous p observations and is widely used for short-term forecasting in domains such as weather, finance, and sales.