Definitions – Various types of valuations – Valuation methods - Necessity –Year’s purchase-sinking fund- Capitalised value – Depreciation – Escalation – Valuation of land – Buildings – Calculation of Standard rent – Mortgage – Lease - Types of lease
CE3701-ECVE - Prof.AK 1
CE3701 - Estimation, Costing And Valuation Engineering
Prepared By: Dr. A. Ananthakumar, M.E (STRUCT)., Ph.D.,
COURSE OBJECTIVE:
The students will acquire knowledge in estimation, tender practices, contract
procedures, and valuation and will be able to prepare estimates, call for tenders
and execute works.
Credit 3
2.
August 7, 2026
CE3701-ECVE- Prof. AK
2
SYLLABUS
UNIT V VALUATION 9
Definitions – Various types of valuations – Valuation methods - Necessity –
Year’s purchase-sinking fund- Capitalised value – Depreciation – Escalation –
Valuation of land – Buildings – Calculation of Standard rent – Mortgage –
Lease - Types of lease
Unit 5 – Valuation
3.
August 7, 2026
CE3701-ECVE- Prof. AK
3
Unit 5 – Valuation
INTRODUCTION
Valuation is the process of determining the economic worth of an
asset, essential in fields like civil engineering, real estate, and finance. It
supports informed decisions in transactions, financing, insurance, and taxation.
Key valuation types include market, investment, insurance, and tax valuations.
Common methods are the comparative, income, and cost methods.
Important concepts in valuation include year's purchase, sinking fund,
capitalized value, depreciation, and escalation. Valuing land and buildings
involves assessing market value, calculating standard rent, and determining
mortgage and lease terms.
Leases, such as operating, finance, and sale and leaseback, define the
rights and obligations of asset use between lessor and lessee. Accurate
valuation is crucial for fair and efficient asset management.
Unit 5 – Valuation
4.
August 7, 2026
CE3701-ECVE- Prof. AK
4
Valuation
Definition
The valuation of a building refers to the process of estimating the
monetary value of a property. This valuation can be required for various
purposes, such as buying or selling property, securing a mortgage, insurance,
taxation, or investment analysis. The process involves assessing several factors
that influence the building's value, including its physical condition, location, size,
and any unique features it may possess.
In general before valuation the age of the building should be obtained
from record if a available or by enquiries or from visual inspection and its future
life should be ascertained.
Unit 5 – Valuation
5.
August 7, 2026
CE3701-ECVE- Prof. AK
5
General Definitions
Gross income:
Gross income is the total amount of money earned before any deductions or
taxes are applied.
Net income:
Net income is the amount of money a person or business earns after all
expenses, taxes, and deductions have been subtracted from their gross
income.
Net income = Gross income – outgoings
Outgoing:
It is the expanses which are required to be incurred to maintain the revenue of
the building.
Unit 5 – Valuation
6.
August 7, 2026
CE3701-ECVE- Prof. AK
6
General Definitions
Types of outgoing:
1. Taxes - include municipal tax property tax, wealth tax, etc.,
2. Repair - to be carried out every year to maintain a propertyin good condition (1-
1.5% of total cost)
3. Management and collection charges - include the expenses on rent collector,
watchman, liftman, pump attended, sweeper, etc.,(5-10% of gross rent)
4. Sinking fund - the gross rentset aside annually as sinking fund to accumulate the
total cost of construction when the life of building is over.
5. Loss of rent - The property may not be kept completely occupied in which case an
appropriate cost need to be subtracted from the gross rentunder outgoings.
6. Miscellaneous - include electric charges, lift, pump, lighting in common places,
etc.,
Unit 5 – Valuation
7.
August 7, 2026
CE3701-ECVE- Prof. AK
7
General Definitions
Municipal Taxes: (10 - 25% of net income)
The municipality collects property taxes to generate the funds necessary for the
maintenance and operation of the public utility services like, roads, drainage, water
supply, street light, etc.,.
Scrap value: (10% of total cost of construction)
It is the value of dismantled materials.
When the building's life is over at the end of its utility period, the dismantled
materials such as steel, bricks, timber, etc., will yield a certain amount, which is
the scrap value of the building.
Salvage value:
Salvage value refers to the estimated worth of a property at the conclusion of its
useful lifespan without undergoing demolition or dismantling.
Unit 5 – Valuation
8.
August 7, 2026
CE3701-ECVE- Prof. AK
8
General Definitions
Scrap value: (10% of total cost of construction)
It is the value of dismantled materials.
When the building's life is over at the end of its utility period, the dismantled
materials such as steel, bricks, timber, etc., will yield a certain amount, which is
the scrap value of the building.
Salvage value:
Salvage value refers to the estimated worth of a property at the conclusion of its
useful lifespan without undergoing demolition or dismantling.
Market value:
The market value of a property is the estimated amount for which it could be
exchanged on the open market under current market conditions between a willing
buyer and a willing seller, neither party being under compulsion.
Unit 5 – Valuation
9.
August 7, 2026
CE3701-ECVE- Prof. AK
9
General Definitions
Book value:
It is the amount shown in the account book after allowing necessary
depreciations.
Book value = Original cost - amount of depreciation at last year
Capital cost:
It is the total cost of construction including land, or the original total
amount required to possess a property.
Unit 5 – Valuation
10.
August 7, 2026
CE3701-ECVE- Prof. AK
10
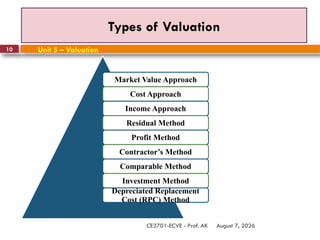
Types of Valuation
Market Value Approach
Cost Approach
Income Approach
Residual Method
Profit Method
Contractor’s Method
Comparable Method
Investment Method
Depreciated Replacement
Cost (RPC) Method
Unit 5 – Valuation
11.
August 7, 2026
CE3701-ECVE- Prof. AK
11
Types of Valuation
Unit 5 – Valuation
1. Market Value Approach
This approach estimates the value of a building by comparing it to similar
properties that have recently sold in the same area. Key factors considered include
location, size, condition, and features. This method is commonly used for residential
properties.
2. Cost Approach
This method calculates the value of a building based on the cost to construct a similar
building at current prices, minus depreciation. It is useful for newer buildings or
properties where accurate cost data is available.
Replacement Cost Method: Estimates the cost to replace the building with
one of similar utility using modern construction methods and materials.
Reproduction Cost Method: Calculates the cost to reproduce the building
with the same materials, design, and specifications.
12.
August 7, 2026
CE3701-ECVE- Prof. AK
12
Types of Valuation
Unit 5 – Valuation
3. Income Approach
This approach is often used for commercial and rental properties. It values the
building based on the income it generates or is expected to generate.
Direct Capitalization Method: Estimates the building's value by dividing
the net operating income (NOI) by a capitalization rate (cap rate).
Discounted Cash Flow (DCF) Method: Projects future income streams
from the property and discounts them to present value using a discount rate.
4. Residual Method
This method is used for development properties. It calculates the value of a building
by estimating the potential revenue from the completed project and subtracting
development costs (including construction, finance, and profit).
13.
August 7, 2026
CE3701-ECVE- Prof. AK
13
Types of Valuation
Unit 5 – Valuation
5. Profits Method
This method values properties that are rarely sold on the open market and are
typically owner-occupied, such as hotels or nursing homes. It involves calculating
the property's value based on its ability to generate profit.
6. Contractor's Method
Also known as the contractor's test or the summation method, this approach is used for
specialized properties. It involves adding the land value to the depreciated
replacement cost of the building and improvements.
7. Comparable Method
This method involves comparing the building with other similar properties that
have recently sold or are currently on the market. Adjustments are made for
differences in features, location, and condition.
14.
August 7, 2026
CE3701-ECVE- Prof. AK
14
Types of Valuation
Unit 5 – Valuation
8. Investment Method
This method is used to value properties that are bought for their investment
potential. It involves calculating the present value of future income streams that the
property will generate.
9. Depreciated Replacement Cost (DRC) Method
This method is used for properties that do not frequently trade on the open market,
such as schools or hospitals. It estimates the cost to replace the building and then
depreciates it to account for age and condition.
15.
August 7, 2026
CE3701-ECVE- Prof. AK
15
Valuation Methods
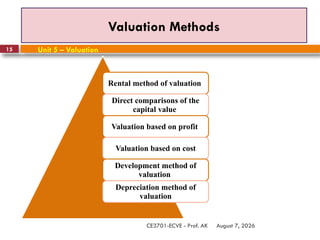
Rental method of valuation
Direct comparisons of the
capital value
Valuation based on profit
Valuation based on cost
Development method of
valuation
Depreciation method of
valuation
Unit 5 – Valuation
16.
August 7, 2026
CE3701-ECVE- Prof. AK
16
Valuation Methods
Unit 5 – Valuation
1. Rental method of valuation
In this method, the net income by way of rent is found out by deducting all
outgoing from the gross rent. A suitable rate of interest as prevailing in the
market is assumed and years purchase is calculated.
Capitalized value = Net Income x Years Purchase
2. Direct comparisons of the capital value
This method may be adapted when the rental value is not available from the
property concerned, but there are evidences of sale price of properties as a
whole. In such cases the capitalized value of the property is fixed by direct
comparison with capitalized value of similar property in the locality.
17.
August 7, 2026
CE3701-ECVE- Prof. AK
17
Valuation Methods
Unit 5 – Valuation
3. Valuation based on profit
This method of valuation is suitable for buildings like hotels, cinemas,
theatres, etc., for which the capitalized value depends on the profit. The
net annual income is worked out after deducting from the gross income all
possible working expenses, outgoings, interest on the capital invested, etc.,
Capitalized value = Net profit x Years Purchase
4. Valuation based on cost
In this method the actual cost incurred in constructing the building or in
possessing the property is taken as basis to determine the value of property.
18.
August 7, 2026
CE3701-ECVE- Prof. AK
18
Valuation Methods
Unit 5 – Valuation
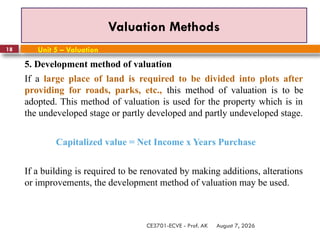
5. Development method of valuation
If a large place of land is required to be divided into plots after
providing for roads, parks, etc., this method of valuation is to be
adopted. This method of valuation is used for the property which is in
the undeveloped stage or partly developed and partly undeveloped stage.
Capitalized value = Net Income x Years Purchase
If a building is required to be renovated by making additions, alterations
or improvements, the development method of valuation may be used.
19.
August 7, 2026
CE3701-ECVE- Prof. AK
19
Valuation Methods
Unit 5 – Valuation
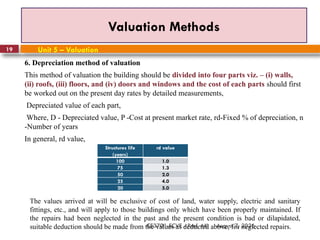
6. Depreciation method of valuation
This method of valuation the building should be divided into four parts viz. – (i) walls,
(ii) roofs, (iii) floors, and (iv) doors and windows and the cost of each parts should first
be worked out on the present day rates by detailed measurements,
Depreciated value of each part,
Where, D - Depreciated value, P -Cost at present market rate, rd-Fixed % of depreciation, n
-Number of years
In general, rd value,
Structures life
(years)
rd value
100 1.0
75 1.3
50 2.0
25 4.0
20 5.0
The values arrived at will be exclusive of cost of land, water supply, electric and sanitary
fittings, etc., and will apply to those buildings only which have been properly maintained. If
the repairs had been neglected in the past and the present condition is bad or dilapidated,
suitable deduction should be made from the values as deducted above, for neglected repairs.
20.
August 7, 2026
CE3701-ECVE- Prof. AK
20
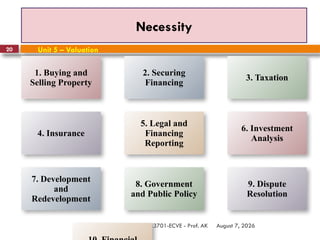
Necessity
Unit 5 – Valuation
1. Buying and
Selling Property
2. Securing
Financing
3. Taxation
4. Insurance
5. Legal and
Financing
Reporting
6. Investment
Analysis
7. Development
and
Redevelopment
8. Government
and Public Policy
9. Dispute
Resolution
21.
August 7, 2026
CE3701-ECVE- Prof. AK
21
Necessity
Unit 5 – Valuation
1. Buying and Selling Property
Valuation helps determine a fair market price for properties, ensuring that buyers
and sellers have an objective basis for negotiations.
Investors be sure of on accurate valuations to assess the potential return on investment
and to make informed decisions.
2. Securing Financing
Lenders require property valuations to determine the amount of money they are willing
to lend against the property as collateral.
Accurate valuations are essential when property owners seek to refinance their existing
loans.
3. Taxation
Governments use property valuations to assess property taxes, ensuring that tax
assessments are fair and based on the current market value.
When a property is sold, valuation helps in calculating the capital gains tax, which is the
tax on the profit made from the sale.
22.
August 7, 2026
CE3701-ECVE- Prof. AK
22
Necessity
Unit 5 – Valuation
4. Insurance
Valuation determines the appropriate amount of insurance coverage needed to replace
or repair a property in case of damage or loss.
Accurate valuations are necessary for fair settlement of insurance claims.
5. Legal and Financial Reporting
Valuations are used to determine the value of real estate within an estate for inheritance
and distribution purposes.
Property valuations help in equitable distribution of assets during divorce proceedings.
Businesses use valuations to report the value of their real estate assets in financial
statements, ensuring accurate representation of their financial position.
6. Investment Analysis
Investors need property valuations to manage their real estate portfolios effectively,
ensuring that their investments are performing as expected.
Accurate valuations help in assessing the risk associated with real estate investments.
23.
August 7, 2026
CE3701-ECVE- Prof. AK
23
Necessity
Unit 5 – Valuation
7. Development and Redevelopment
Valuation is crucial for determining the viability of development or
redevelopment projects, helping developers assess potential
profitability.
Accurate valuations guide decisions related to the purchase of land for
development purposes.
8. Government and Public Policy
Governments use valuations to make informed decisions about urban
planning, zoning, and land use policies.
When the government acquires private property for public use, valuations
ensure fair compensation to property owners.
24.
August 7, 2026
CE3701-ECVE- Prof. AK
24
Necessity
Unit 5 – Valuation
9. Dispute Resolution
Property valuations provide an objective basis for resolving disputes
related to property value, whether in court or through alternative dispute
resolution mechanisms.
10. Financial Restructuring
Accurate valuations are necessary during bankruptcy to determine the
value of assets and liabilities.
Valuations help in assessing the value of real estate assets during
corporate restructuring, mergers, and acquisitions.
25.
August 7, 2026
CE3701-ECVE- Prof. AK
25
Years Purchase
Unit 5 – Valuation
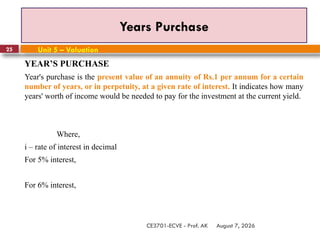
YEAR’S PURCHASE
Year's purchase is the present value of an annuity of Rs.1 per annum for a certain
number of years, or in perpetuity, at a given rate of interest. It indicates how many
years' worth of income would be needed to pay for the investment at the current yield.
Where,
i – rate of interest in decimal
For 5% interest,
For 6% interest,
26.
August 7, 2026
CE3701-ECVE- Prof. AK
26
Sinking Fund
Unit 5 – Valuation
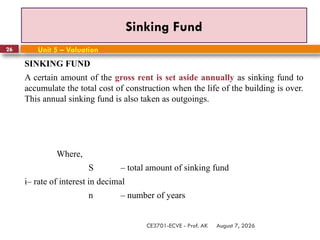
SINKING FUND
A certain amount of the gross rent is set aside annually as sinking fund to
accumulate the total cost of construction when the life of the building is over.
This annual sinking fund is also taken as outgoings.
Where,
S – total amount of sinking fund
i– rate of interest in decimal
n – number of years
27.
August 7, 2026
CE3701-ECVE- Prof. AK
27
Sinking Fund - Problem
Unit 5 – Valuation
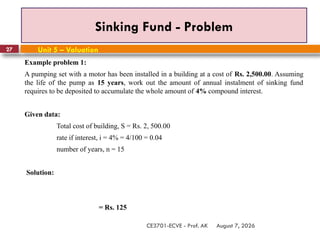
Example problem 1:
A pumping set with a motor has been installed in a building at a cost of Rs. 2,500.00. Assuming
the life of the pump as 15 years, work out the amount of annual instalment of sinking fund
requires to be deposited to accumulate the whole amount of 4% compound interest.
Given data:
Total cost of building, S = Rs. 2, 500.00
rate if interest, i = 4% = 4/100 = 0.04
number of years, n = 15
Solution:
= Rs. 125
28.
August 7, 2026
CE3701-ECVE- Prof. AK
28
Sinking Fund - Problem
Unit 5 – Valuation
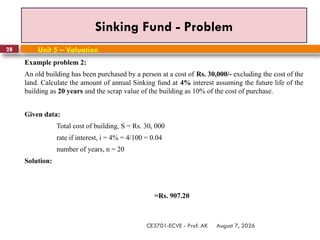
Example problem 2:
An old building has been purchased by a person at a cost of Rs. 30,000/- excluding the cost of the
land. Calculate the amount of annual Sinking fund at 4% interest assuming the future life of the
building as 20 years and the scrap value of the building as 10% of the cost of purchase.
Given data:
Total cost of building, S = Rs. 30, 000
rate if interest, i = 4% = 4/100 = 0.04
number of years, n = 20
Solution:
=Rs. 907.20
29.
August 7, 2026
CE3701-ECVE- Prof. AK
29
Capitalized Value
Unit 5 – Valuation
Capitalized Value
Capitalized value is a valuation method that converts a future income
stream into a present value. It iscommonly used in property and
investment valuation to determine the worth of an assetbased on its ability
to generate income over time. The process involves applying a capitalization
rate to the net income produced by the asset, resulting in a present value that
reflects the asset's worth.
30.
August 7, 2026
CE3701-ECVE- Prof. AK
30
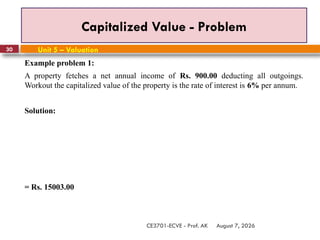
Capitalized Value - Problem
Unit 5 – Valuation
Example problem 1:
A property fetches a net annual income of Rs. 900.00 deducting all outgoings.
Workout the capitalized value of the property is the rate of interest is 6% per annum.
Solution:
= Rs. 15003.00
31.
August 7, 2026
CE3701-ECVE- Prof. AK
31
Depreciation
Unit 5 – Valuation
DEPRECIATION
Depreciation is the process of allocating the cost of a tangible asset over its useful
life. It represents the reduction in value of the asset over time due to factors such as
wear and tear, age, and obsolescence. Depreciation is important for accounting, tax
purposes, and financial reporting as it provides a systematic way to spread the expense
of an asset over the period it is used. Usually a percentage on depreciation per annum
is allowed.
The general annual decrease in the value of a property is known as Annual
depreciation. Usually, the percentage rate of depreciation is less at the beginning and
gradually increases during later years.
32.
August 7, 2026
CE3701-ECVE- Prof. AK
32
Methods of Depreciation
Unit 5 – Valuation
1. Straight Line Method
The straight-line method is the simplest and most commonly used method of
depreciation. It allocates an equal amount of depreciation expense each yearover
the useful life of the asset.
2. Constant percentage method (Declining balance method)
Depreciation is calculated at a fixed percentage of the book value of the asset at the
beginning of each period.The amount of depreciation decreases over time because it
is applied to the reducing balance of the asset.
Annual Depreciation = Book value at Beginning of Year × Depreciation Rate (i)
33.
August 7, 2026
CE3701-ECVE- Prof. AK
33
Methods of Depreciation
Unit 5 – Valuation
Constant Percentage Method:
Example problem:
If an asset has an initial cost of Rs. 10,000 and a depreciation rate of 20%.
Find the annual depreciation using constant percentage method.
Solution:
i. Annual depreciation (1st
year) = 10000 x (20/100) = Rs. 2000/-
ii. Annual Depreciation (2nd
year) = 8000 x (20/100) = Rs. 1600/-
34.
August 7, 2026
CE3701-ECVE- Prof. AK
34
Methods of Depreciation
Unit 5 – Valuation
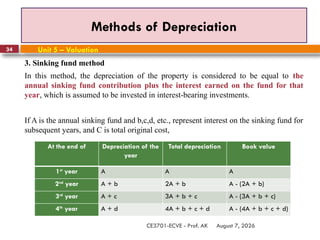
3. Sinking fund method
In this method, the depreciation of the property is considered to be equal to the
annual sinking fund contribution plus the interest earned on the fund for that
year, which is assumed to be invested in interest-bearing investments.
If A is the annual sinking fund and b,c,d, etc., represent interest on the sinking fund for
subsequent years, and C is total original cost,
At the end of Depreciation of the
year
Total depreciation Book value
1st
year A A A
2nd
year A + b 2A + b A - (2A + b)
3rd
year A + c 3A + b + c A - (3A + b + c)
4th
year A + d 4A + b + c + d A - (4A + b + c + d)
35.
August 7, 2026
CE3701-ECVE- Prof. AK
35
Methods of Depreciation
Unit 5 – Valuation
4. Quantity survey method
It is a meticulous approach to determining property depreciation,
particularly for complex structures like buildings. It involves a detailed
breakdown of the property into its individual components, each assessed
for its specific depreciation rate based on factors like wear and tear,
obsolescence, and physical deterioration.
36.
August 7, 2026
CE3701-ECVE- Prof. AK
36
Escalation
Unit 5 – Valuation
ESCALATION
Escalation in civil engineering and construction refers to the upward
adjustment of project costs over time. This increase is typically due to
economic factors such as inflation, fluctuations in material prices, or
changes in labor costs. As construction projects often span several months or
years, accurately forecasting and managing escalation is crucial for
preventing budget overruns.
37.
August 7, 2026
CE3701-ECVE- Prof. AK
37
Mortgage
Unit 5 – Valuation
MORTGAGE
A mortgage is a loan agreement in which a borrower uses real
property, such as a house or land, as collateral to secure the repayment of the
loan.
The borrower receives funds from a lender and agrees to make
regular payments over a specified period until the loan is fully repaid. If
the borrower fails to make the required payments, the lender has the legal
right to seize and sell the property.
Mortgagor: The person who takes the loan
Mortgagee: The person who advances the loan
38.
August 7, 2026
CE3701-ECVE- Prof. AK
38
Lease
Unit 5 – Valuation
LEASE
The owner of a freehold property may grant permission to another
person to use the property, which is known as leasing the property.
Lessee or Leaseholder : The person who takes lease
Lessor : The owner who grants lease
39.
August 7, 2026
CE3701-ECVE- Prof. AK
39
Types of Lease
Unit 5 – Valuation
1. Building lease
A building lease is a contractual agreement in which the owner of a building
grants the right to use and occupy the building to another person or
entity for a specified period in exchange for periodic rental payments.
The lease outlines the terms and conditions of the arrangement, including the
duration of the lease, the rental amount, and the responsibilities of both
parties regarding maintenance and use of the property.
2. Occupation lease
In this case, the building or structure is constructed by the owner and
leased out for occupation for a specific period in exchange for a certain
amount of annual rent.
 Most read