Comprehensive Disaster Risk Reduction Financing and Investment Strategies
1.
Mengol Training andConsultancy Services
Abraham Lebeza
MEL Expert
Email:- lebezaalemu@gmail.com
2.
Mengol Training andConsultancy Services
Disaster Risk Reduction Financing Training
(95) Module 1: Understanding the financial impact of
disasters | UNDRR – YouTube
Module 1: Understanding the financial impact of
disasters
Module 2: Analyzing the current financial landscape
Module 3: Identifying and prioritizing DRR investment
needs
Module 5: Developing a DRR financing strategy
Module 4: Matching needs with financing options
Special Module on Anticipatory Financing
3.
Mengol Training andConsultancy Services
Module 1: Understanding the financial impact of
disasters
The cost of disaster can be direct and indirect. If we
take in to account the combined cost, annually
disaster costs over 1 trillion.
Disasters classified in to sudden onsets and slow
onsets
4.
Mengol Training andConsultancy Services
The direct costs are the dames of housing,
infrastructures, livestock and the emergency
response costs. Where as the indirect costs are the
costs required for the recovery of damaged
industries , institutions and recovery of lost jobs.
5.
Mengol Training andConsultancy Services
Slow onset disasters like , sea level rise, rising
temperature and drought which can be classified as
slow onset disasters can also cause direct and
indirect costs the long term.
GIRI Global Infrastructure Risk Model and
Resilience Index
6.
Mengol Training andConsultancy Services
GIRI Global Infrastructure Risk Model and Resilience Index
GIRI is the first public tool that measures how likely climate and natural disasters
will damage buildings and roads. Developed by the Coalition for Disaster
Resilient Infrastructure (CDRI), it helps countries see which bridges, power grids,
and hospitals are at risk so they can build them stronger.
Here is how GIRI works and why it matters:
What it Does: GIRI uses math and history to predict damage. It calculates
AAL, which stands for Average Annual Loss. Think of this as the average
dollar amount a country will lose to disasters like floods or earthquakes
every single year.
Why it Matters: 60% of the infrastructure we need by 2050 is not built yet. GIRI
shows that without making these new structures "resilient" (strong enough to
survive disasters), the world could lose up to $845 billion every year.
7.
Mengol Training andConsultancy Services
Sectors Covered: It looks at 6 main areas:
• Power and energy
• Transport (roads, bridges)
• Telecommunications
• Water
• Education (schools)
• Health (hospitals)
Real-World Benefit: By understanding GIRI data, countries can plan
better. For example, it helps leaders see how adding green spaces
to a city can soak up floodwater and save money.
There are two types of costs. The first cost is the cost that used for
prevention investment and the second cost is the cost that is used
to rehabilitate the damages due to unavoidable disasters (residual
damage).
8.
Mengol Training andConsultancy Services
Module 2: Analyzing the current financial landscape
The cost of disaster reduction measures can be minimized due to the planned risk reduction and
management measures. For instance disaster prevention measures such as the construction of
defense in the river banks in a low-lying cities and the conservation of mangroves in coastal cities
not only reduced the cost of disaster risks but is also demands less cost. Such prevention
measures are more cost effective measures than early warning systems that are alerts for the
public.
However the cost of disaster risk reduction measures are not eliminated but minimized.
The cost of measures taken to prevent disaster can have a potential of saving a fifth fold cost damage
prevention as most agrees. As a result, it is important to know about the magnitude of investment
on disaster risk management.
Measuring disaster risk management investment is not an easy task, because disaster risk
management is a cross cutting that embeds across multiple sectors such as the industry,
agriculture, infrastructure and so on. The source of budget is also varying from public expenditure
, private investment and international assistances. The purpose of this course of is to try to track
the budget allocation by the national governments (public expenditure) for disaster risk
management
9.
Mengol Training andConsultancy Services
The United Nations Office for Disaster Risk Reduction (UNDRR) uses a five-step
approach to finance disaster resilience. This strategy helps governments stop
reacting to disasters and start paying for prevention before they happen
Here are the five steps:
1. Understand disaster costs: Governments calculate the true price of
disasters. This includes direct losses (broken buildings) and indirect losses
(lost business)
2. Analyze current spending: Countries look at their budgets. They see how
much money goes to fixing emergencies versus preventing them.
3. Build a financial strategy: Planners create a plan to pay for resilience. They
mix public funds, private money, and donor aid
4. Reform public systems: Governments change how they budget. They make sure every public
project (like a new school or road) is built to survive natural disasters.
5. Get political buy-in: Leaders officially agree on the plan. They give out tasks and timelines to
make sure the strategy actually works
10.
Mengol Training andConsultancy Services
1. Analyzing financial consequences of disasters
2. Analyze existing financial landscape
3. Identify and prioritize financial needs
4. Match needs with financial options
5. Develop a plan/DRR financial strategy
11.
Mengol Training andConsultancy Services
Budget tagging and tracking system (TAC)
A Budget Tagging and Tracking System (TAC) is a public
financial tool that assigns "labels" to government spending.
Governments use these tags to easily track how much money
goes toward specific goals, like fighting climate change or
improving health.
Global around sixty countries are adopting budget tagging and
tracking system at least for the climate change related
investments. As climate change investment and DRR are
overlapping activities, it is advisable to use the same budget
tagging and tracking system for both.
12.
Mengol Training andConsultancy Services
A budget tagging and tracking system classifies public spending
to monitor goals like climate change or poverty. The system
uses four main tag levels to categorize how a program
supports a goal: Principal, Significant, Moderate, and
Marginal
These four tags help governments track exactly how money is spent:
1. Principal: The goal is the main purpose of the project. Without this
goal, the project would not exist. It is weighted at 100% of the cost.
2. Significant: The goal is a deliberate and important part of the project,
but not the main reason for the project.
3. Moderate: The project provides some indirect support, but the goal is
not a primary focus.
4. Marginal: The project has very little or no clear link to the target goal.
13.
Mengol Training andConsultancy Services
Budget tagging and tracking system (TAC)
What percentage of investment needs for DRR and Climate Change Adaptation (CCA) are not met by
domestic and international public expenditures?(1 Point)
• Around 50%
• More than 75%
• Less than 25%
In DRR budget tagging, which activity would likely be tagged as a DRR investment?(1 Point)
• Purchasing relief supplies after a disaster
• Providing post-disaster compensation to affected communities
• Building climate-resilient infrastructure in flood-prone areas
What are the direct benefits and potential outcomes of DRR budget tagging? (Select all that apply)(1 Point)
• Increase budget transparency and understanding of publicly funded DRR actions
• Eliminate the need for governments to prepare separate disaster response budgets
• Uncover financing gaps
• Support budgetary allocations and mainstreaming of DRR into line ministries
Why is understanding the full costs of disasters important for policymakers?(1 Point)
• It provides the basis for making better-informed finance decisions and demonstrates the economic
benefits of investing in disaster risk reduction
• It ensures that post-disaster reconstruction is not needed
• It allows them to eliminate financial risk entirely
14.
Mengol Training andConsultancy Services
Module 3: Identifying and prioritizing DRR
investment needs
1. Resilient infrastructure
2. Resilient Nature and biodiversity
3. Resilient Health
4. Resilient Agri-food systems
5. resilient INDUSTRY AND COMMERCE
6. Resilient cities
7. Resilient society
15.
Mengol Training andConsultancy Services
Prevention investments
National DRR strategies
National determined contributions NDC
National Adaptation Plans NAPs
DRR preparedness
As disasters are unavoidable, national governments should take in
to account their risk profile and plan their financial risks so that
they can avail recovery and responses during disasters.
However, countries will come with a log list of risks and as a
result they can apply multi –criteria analysis to prioritize their
prioritized investment.
16.
Mengol Training andConsultancy Services
A Multi-Criteria Analysis (MCA) evaluates how well different disaster
risk reduction (DRR) investments achieve multiple goals, such as
economic, social, and environmental outcomes.
Cost –benefit analysis
Benefit –cost ratios
Resilient infrastructure are expected to cost 3% additional ,
however the benefit cost ration analysis revealed that it is 4. This
means that any resilience investment cost can benefit us to save
fourth fold cost of the infrastructure. However, the benefit –cost
ration depends on the context of the infrastructure and the types of
models we use for benefit –cost analysis
17.
Mengol Training andConsultancy Services
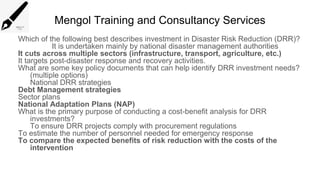
Which of the following best describes investment in Disaster Risk Reduction (DRR)?
It is undertaken mainly by national disaster management authorities
It cuts across multiple sectors (infrastructure, transport, agriculture, etc.)
It targets post-disaster response and recovery activities.
What are some key policy documents that can help identify DRR investment needs?
(multiple options)
National DRR strategies
Debt Management strategies
Sector plans
National Adaptation Plans (NAP)
What is the primary purpose of conducting a cost-benefit analysis for DRR
investments?
To ensure DRR projects comply with procurement regulations
To estimate the number of personnel needed for emergency response
To compare the expected benefits of risk reduction with the costs of the
intervention
18.
Mengol Training andConsultancy Services
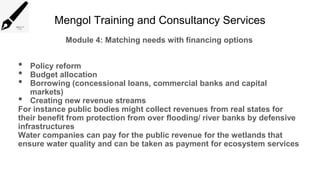
Module 4: Matching needs with financing options
• Policy reform
• Budget allocation
• Borrowing (concessional loans, commercial banks and capital
markets)
• Creating new revenue streams
For instance public bodies might collect revenues from real states for
their benefit from protection from over flooding/ river banks by defensive
infrastructures
Water companies can pay for the public revenue for the wetlands that
ensure water quality and can be taken as payment for ecosystem services
19.
Mengol Training andConsultancy Services
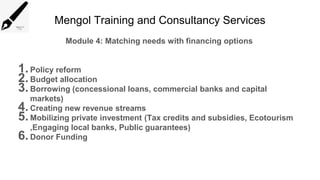
Module 4: Matching needs with financing options
1.Policy reform
2.Budget allocation
3.Borrowing (concessional loans, commercial banks and capital
markets)
4.Creating new revenue streams
5.Mobilizing private investment (Tax credits and subsidies, Ecotourism
,Engaging local banks, Public guarantees)
6.Donor Funding
20.
Mengol Training andConsultancy Services
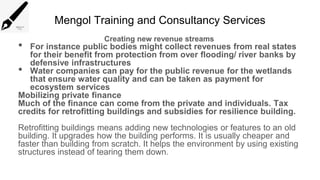
Creating new revenue streams
• For instance public bodies might collect revenues from real states
for their benefit from protection from over flooding/ river banks by
defensive infrastructures
• Water companies can pay for the public revenue for the wetlands
that ensure water quality and can be taken as payment for
ecosystem services
Mobilizing private finance
Much of the finance can come from the private and individuals. Tax
credits for retrofitting buildings and subsidies for resilience building.
Retrofitting buildings means adding new technologies or features to an old
building. It upgrades how the building performs. It is usually cheaper and
faster than building from scratch. It helps the environment by using existing
structures instead of tearing them down.
21.
Mengol Training andConsultancy Services
Response Preparedness
Risk layering is a strategy that splits risk into levels based on how
likely and costly a problem is. Governments and businesses use this
method to save money. Instead of buying expensive insurance for
small problems, they use cheaper local funds. They use insurance
or disaster bonds only for massive emergencies
Think of it like fixing a broken car window. You would pay for a small
$100 repair using cash from your savings. You would not use your
car insurance, because your deductible is higher than the repair
cost. However, if your car is totaled in a $10,000 crash, you activate
your insurance.
22.
Mengol Training andConsultancy Services
In financial protection and disaster risk finance, risks are broken down into three specific
levels:
Layer 1: Low-Risk, High-Frequency (Small problems): These are everyday
issues or minor storms. Because they happen often, the most cost-effective way
to pay for them is risk retention (using local budget reserves, petty cash, or
contingency funds)
Layer 2: Medium-Risk, Medium-Frequency (Moderate disasters): These events
cause more damage but happen less often. Organizations handle this using
contingent credit or pre-arranged loans (e.g., lines of credit that release funds
quickly only when a disaster strikes)
Layer 3: High-Risk, Low-Frequency (Catastrophes): These are massive
disasters that rarely happen but cost millions. Organizations use risk transfer
here. They transfer the financial burden to outside experts like insurance
companies, reinsurers, or capital markets (e.g., catastrophe bonds)
This method ensures that cheaper money is spent first. It prevents organizations from draining
their budgets on smaller, manageable risks
23.
Mengol Training andConsultancy Services
As per the risk layering strategy, there two are major financial
instruments to respond to the different needs :
These are :
1. Risk Retention Instruments
2. Risk Transfer Solutions
24.
Mengol Training andConsultancy Services
Risk Retention Instruments
Risk retention instruments are financial tools used to absorb the costs of losses
internally rather than transferring them to a third party like an insurance
company. Organizations and governments use these to manage frequent, low-
severity events where paying insurance premiums would be too expensive
• Disaster fund –readily available
• Budget Reallocation – seeks decisions by many stakeholders' and
delays
• Supplementary budget
• Adaptive social protection
25.
Mengol Training andConsultancy Services
Contingent credit lines
A contingent credit line is a pre-approved, standby loan that a borrower can
access only if a specific, unexpected event happens. Think of it like an
emergency umbrella. You do not pay for it until it rains, but you are glad it
is there when it does.
Governments and large businesses set up these agreements in calm times
to access quick cash during disasters, like floods or pandemics.
Here is how they work:
Setup: A bank or financial group agrees to lend a certain amount of
money, but only if a specific "trigger" event occurs.
No Upfront Debt: You do not owe anything until you actually withdraw the
money. However, you usually pay a small "commitment fee" to the bank
to keep the line open.
Fast Cash: Instead of waiting weeks to apply for a new loan during a
crisis, the borrower can withdraw the money immediately.
26.
Mengol Training andConsultancy Services
Climate Resilient Debt Clauses (CRDC)
Climate Resilient Debt Clauses (CRDCs) are loan terms that let borrowing countries temporarily pause
debt payments after natural disasters or health emergencies. This allows governments to redirect
money to emergency relief instead of paying back banks. The pause lasts up to two years
Think of a CRDC like pausing your monthly rent because your roof caved in. If a bad storm or flood
hits a country, its fiscal space—the budget a government has to spend on public needs—shrinks.
Instead of choosing between rebuilding roads or paying a loan, the country pauses the debt. This
stops the country from defaulting (failing to pay).
CRDCs are Net Present Value (NPV) neutral. This means the total cost of the loan does not change.
The paused payments are just moved to the end of the loan.
Key facts about CRDCs:
The Triggers: Severe events like floods, droughts, earthquakes, or pandemics activate the pause.
Global Support: Major lenders like the World Bank offer these clauses. Other countries like the UK,
France, and Japan also include these in their direct loans.
The 2025 Goal: A global coalition aims to make CRDCs a standard feature in all sovereign lending by
the end of 2025.
27.
Mengol Training andConsultancy Services
Climate Resilient Debt Clauses (CRDC)
Climate Resilient Debt Clauses (CRDCs) are loan terms that let borrowing countries temporarily pause
debt payments after natural disasters or health emergencies. This allows governments to redirect
money to emergency relief instead of paying back banks. The pause lasts up to two years
Think of a CRDC like pausing your monthly rent because your roof caved in. If a bad storm or flood
hits a country, its fiscal space—the budget a government has to spend on public needs—shrinks.
Instead of choosing between rebuilding roads or paying a loan, the country pauses the debt. This
stops the country from defaulting (failing to pay).
CRDCs are Net Present Value (NPV) neutral. This means the total cost of the loan does not change.
The paused payments are just moved to the end of the loan.
Key facts about CRDCs:
The Triggers: Severe events like floods, droughts, earthquakes, or pandemics activate the pause.
Global Support: Major lenders like the World Bank offer these clauses. Other countries like the UK,
France, and Japan also include these in their direct loans.
The 2025 Goal: A global coalition aims to make CRDCs a standard feature in all sovereign lending by
the end of 2025.
28.
Mengol Training andConsultancy Services
Risk Transfer Solutions
Risk transfer solutions move the financial burden of hazards from your business to a
third party (like an insurer or investor). Instead of paying for losses yourself, you pay
a fee or premium. This protects your cash flow from sudden disasters
These solutions range from standard policies to custom, non-traditional structures.
The best option depends on the type and size of your exposure:
Traditional Insurance: The most common form. You pay a premium to a company.
They cover losses from events like fires or lawsuits.
Contractual Transfer: Legal agreements (like a vendor contract) that shift
responsibility for damages to another party.
Captives: A company creates its own licensed insurance subsidiary. This helps you
insure hard-to-find risks and keep unused premiums.
Parametric Insurance: A policy that pays out automatically when a specific event
happens—like a storm with winds over 100 mph. You do not have to prove physical
damage.
Capital Market Solutions: Tools like catastrophe bonds that allow investors to take
on your financial risks
29.
Mengol Training andConsultancy Services
To find the right fit, it helps to understand how these options compare. Traditional
insurance acts like an umbrella for basic risks. A captive acts like a personalized safety
net you design yourself. Parametric insurance acts like a trigger that pays out instantly
when a specific number is reached.
The issue of accessibility and affordability is crucial as determining the parameter to
trigger the insurance and share the disaster among others. There are institutions like the
Caribbean catastrophe risk facility and the African risk capacity established to determine
the parameter for triggering an insurance.
Sovereign parametric insurance
Catastrophic bonds
Individual insurances
Community risk pools
30.
Mengol Training andConsultancy Services
Contingent credit lines are mainly used for:(1 Point)
• Investing in resilient infrastructure.
• Covering routine budget expenditures
• Providing rapid liquidity to governments for emergency response following a
disaster.
A government wants to fund large-scale flood protection infrastructure (e.g., dams, drainage
systems), which requires a high upfront investment and delivers benefits over many years.
What instruments would be most suitable in this case?(1 Point)
• Emergency relief funds
• Sovereign insurance payouts
• A long-term loan or resilience bond
• Humanitarian aid
Which combination of financing instruments best supports a comprehensive DRR financing
strategy?(1 Point)
• Relying on post-disaster humanitarian aid and international grants
• Focusing on insurance and pre-arranged financing
• Combining budget allocation for resilience investments (risk reduction), insurance
for shocks (risk transfer), and contingency finance for emergencies (risk retention)
31.
Mengol Training andConsultancy Services
Module 5: Developing a DRR financing strategy
The reform related to disaster risk management can includes:
• Disaster risk assessment in to investment planning
• Adding specific resilience criterial to public procurement processes
• Requiring regular stress test for infrastructure systems
Disaster risk reduction financing strategy
A Disaster Risk Reduction (DRR) financing strategy is a proactive plan used by governments
and organizations to fund disaster prevention and secure money for quick emergency recovery.
Its goal is to protect public budgets, prevent long-term debt, and stop communities from falling
into deep poverty when disasters strike
A disaster risk financing (DRF) strategy prepares governments or organizations to pay for
sudden emergencies. Key components include risk assessment, risk layering (mixing funds),
pre-arranged instruments, and institutional governance. These components prevent funds
from running out or halting vital services
32.
Mengol Training andConsultancy Services
What is the key difference between Disaster Risk Financing (DRF) strategies and Disaster Risk Reduction (DRR)
Financing Strategies?
(1 Point)
• DRF focuses on funding disaster response and recovery, while DRR Financing adds investments in
prevention to build a more comprehensive approach.
• DRF is a short-term emergency tool, while DRR Financing replaces the need for disaster response
• DRF focuses on preventing disasters, while DRR Financing focuses on post-disaster response
When addressing 'financial resilience', what does the strategy compare in order to determine if more insurance or credit
lines are needed?(1 Point)
• Private sector investment vs. public sector spending
• Expected impact of disasters vs. existing financial instruments
• Donor resources vs. national emergency reserves
• Historical loss data vs. current tax revenue
What can support the implementation of a DRR financing strategy and build internal buy-in for it? (multiple options)(1
Point)
• Cabinet Endorsement
• Engagement of Sectoral Ministries
• Engagement of Political Leaders
• A Champion in the Ministry of Finance
33.
Mengol Training andConsultancy Services
Special Module on Anticipatory Financing
Anticipatory financing uses pre-arranged money to fund early actions before a disaster
strikes. Instead of waiting to respond to emergencies, it relies on weather forecasts
and early warning data. When data hits a set threshold, the funds release
automatically, saving lives, protecting property, and saving money
Hard triggers versus soft triggers
Hard triggers are strict, objective, and automatic rules. Soft triggers rely on subjective
judgment, flexibility, or a series of minor events
Anticipatory financing relies on hard and soft triggers
Anticipatory financing releases money before a predicted disaster hits. It uses "hard" and
"soft" triggers to decide when to act. Hard triggers rely on strict data and automation.
Soft triggers use expert human opinion and flexible alerts.
34.
Mengol Training andConsultancy Services
Anticipatory action can be really both as a result of build funding and fuel funds
"Build funding" and "fuel funding" are the two main ways we pay for anticipatory action
(taking steps to protect communities before a disaster strikes).
Build funding pays to set up the system. It covers the costs of analyzing risks, building
weather prediction models, and creating emergency plans. Think of it like buying a
fire extinguisher and practicing a fire drill in your home.
Fuel funding is the money released immediately when a trigger or warning goes off. It
pays for the actual actions to keep people safe. Using the fire example, fuel funding is
the water that puts out the fire once the alarm sounds
35.
Mengol Training andConsultancy Services
Some courtiers do have good practices of incorporating anticipatory actions in their disaster
risk management financing strategy
Anticipatory actions rely on using early warnings and pre-arranged funds to protect
vulnerable communities before a disaster strikes. While both the Philippines and
Ethiopia use this method to save lives and protect assets, their legal and financial
strategies for implementing these actions are very different
Ethiopia disaster risk management financing strategy
Ethiopia's Disaster Risk Management Financing Strategy 2023–2030 | PDF
36.
Mengol Training andConsultancy Services
Anticipatory funds are financial pools that release money before a predicted disaster happens. By acting on
early warning forecasts, these mechanisms prevent damage instead of just reacting after a crisis occurs.
These funds protect vulnerable communities and save money on costly emergency responses.
The most common and trusted anticipatory funds used by international and local groups include:
• CERF (Central Emergency Response Fund): Managed by the United Nations, CERF has a dedicated
window specifically for anticipatory action. It releases money to UN agencies and partners the moment
strict early warning thresholds are met
• Start Ready: Managed by the Start Network, this is a pooled risk pool fund. It uses climate
data and scientific forecasts to release money to local humanitarian responders
automatically before disasters strike.
• FbF (Forecast-based Financing): Led by the Red Cross (IFRC), this mechanism releases
funding based on agreed-upon Early Action Protocols. Local branches pre-plan what to do
and access cash to distribute before extreme events like floods or droughts.
• The Food and Agriculture Organization (FAO) uses Anticipatory Action funds to release
money based on early warnings before disasters strike. By acting early, the FAO helps
farmers protect crops, secure food, and save livestock. Every dollar invested this way can
save up to $7 in emergency costs.
• ARC (African Risk Capacity) Replica: This is a climate risk insurance pool. It allows
governments and aid organizations to pay premiums that trigger quick payouts if seasonal
rainfall or drought forecasts reach a dangerous level
37.
Mengol Training andConsultancy Services
Which statement best describes how anticipatory finance is delivered?(1 Point)
• Funds are requested after a disaster strikes and released once the impact is assessed
• Funds are pre-arranged and released quickly when forecast thresholds or trigger points set in advance
are met
• Money is released automatically when a government declares a national emergency
• Finance becomes available if a set trigger is met and the donor or fund approves the funding request
A country is designing its anticipatory action framework. It needs [X] funding to update beneficiary registries, strengthen
social protection payout systems and run simulations and [Y] funding to fund anticipatory actions such as
evacuations, provision of water and food or cash transfers.
Fill in the missing words (X) and (Y) related to anticipatory finance.(1 Point)
• X = Preparedness; Y = Humanitarian
• X = Development; Y = Fuel
• X = Build; Y = Fuel
• X = Fuel; Y = Humanitarian
Which statement best reflects current funding sources for anticipatory action?(1 Point)
Most anticipatory action funding today comes from insurance payouts, with pooled funds playing a minimal role
• Risk pools now provide the majority of anticipatory finance, replacing donor supported contingency funds
• National governments are the main providers of pre arranged anticipatory funding
• Pooled funds and bilateral donors remain the most widely used sources of anticipatory finance, while
insurance mechanisms and risk pooling schemes are being tested but still represent a smaller share