The Big Credit Freeze
Akash Balram
Introduction
2
After 10 months of liquidity deficit for banks, the RBI liquidity tap is
back to surplus in the last two months, but will it stay there for
long?
3
Events leading up to the current liquidity
crisis in the Indian financial system
4
Clean up the system
Asset quality review (AQR) of banks
Close to a dozen banks did not have the wherewithal to
continue lending without cooking books
Prompt corrective action (PCA) watch - and forbade them from
lending afresh unless their capital adequacy was shored up
Role of NBFC’s and HFC’s
• High Growth experienced by non-banking
financial companies (NBFCs) and housing
finance companies (HFCs)
• Provided funds to not only troubled
sectors but also small and medium
enterprises incapable to receive loans
from Banks
5
6
ILFS Crisis • In June last year Infrastructure
Leasing and Financial Services
(IL&FS) subsidiaries defaulted,
setting off a chain reaction.
• NBFCs raising short-term
commercial papers (CPs) from banks
and mutual funds who rolled over
their previous borrowings, found it
difficult to access the money.
• No liquidation of their assets - loans
to projects that were long term and
incomplete.
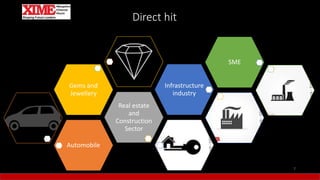
Direct hit
Automobile
Real estate
and
Construction
Sector
Gems and
Jewellery
Infrastructure
industry
SME
7
Real estate and Construction Sector
There is credit squeeze
Banks and NBFCs are staying away from early and mid-stage real estate project funding
they prefer to lend to a project once the building is half finished or where some sale has
taken place.
"There is simply no money available even for good businesses to expand,"
8
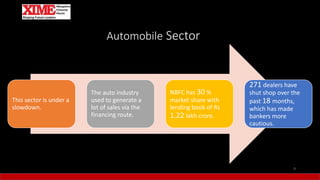
Automobile Sector
This sector is under a
slowdown.
The auto industry
used to generate a
lot of sales via the
financing route.
NBFC has 30 %
market share with
lending book of Rs
1.22 lakh crore.
271 dealers have
shut shop over the
past 18 months,
which has made
bankers more
cautious.
9
Gems and Jewellery
Demonetisation and GST
Nirav Modi and Mehul
Choksi frauds in the
banking sector coming to
light.
Outstanding bank credit to
the sector has been
stagnant at Rs 72,000
crore.
10
Infrastructure industry
The infrastructure industry saw lending from banks dry up.
• Bank and (PSBs) have turned extremely cautious in lending .
• Recent Challenge
• Liquidity crunch.
• Less demand.
• Project construction or big infrastructure projects have come to a standstill.
11
Small Medium Enterprise (SME’s)
Banks focus is more on micro loans, especially Mudra loans.
NBFC gave High level of loan against property (LAP)given by them.
LAP market with 53 per cent market share and outstanding lending at Rs 1.85 lakh crore as of
March 2019
liquidity squeeze has closed the doors to this source too for SMEs.
12
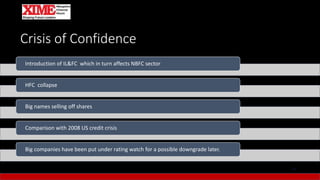
Crisis of Confidence
13
Introduction of IL&FC which in turn affects NBFC sector
HFC collapse
Big names selling off shares
Comparison with 2008 US credit crisis
Big companies have been put under rating watch for a possible downgrade later.
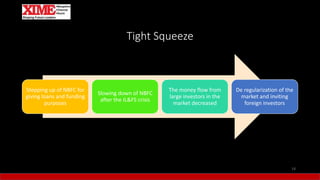
Tight Squeeze
Stepping up of NBFC for
giving loans and funding
purposes
Slowing down of NBFC
after the IL&FS crisis
The money flow from
large investors in the
market decreased
De regularization of the
market and inviting
foreign investors
14
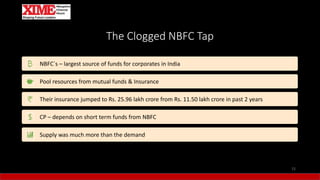
The Clogged NBFC Tap
15
NBFC`s – largest source of funds for corporates in India
Pool resources from mutual funds & Insurance
Their insurance jumped to Rs. 25.96 lakh crore from Rs. 11.50 lakh crore in past 2 years
CP – depends on short term funds from NBFC
Supply was much more than the demand
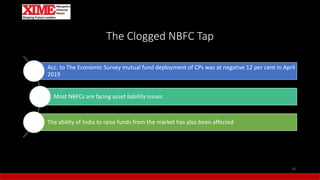
The Clogged NBFC Tap
Acc. to The Economic Survey mutual fund deployment of CPs was at negative 12 per cent in April
2019
Most NBFCs are facing asset liability issues
The ability of India to raise funds from the market has also been affected
16
Banking flows run dry
PSBs are the biggest
supplier of credit.
Central bank reported
de-growth of about 5%
in its loan book.
Government has
promised to pump in
capital.
As demand for credit
was already weak,
those who did need
money found it difficult.
17
Domestic Savings Leakage
The fall in the household
savings is mainly due to a
decline in physical savings
The overall savings rate in
the economy has fallen
from 33% of GDP to 30%.
Savings rate falling from
23% to 17%.
18
Private sector & Public sector Companies
Both are not encouraging
The corporate saving rate looks better despite GST and other
disruptions
19
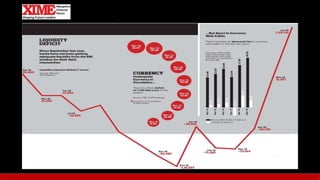
System Liquidity Deficit
Liquidity Deficit
Liquidity deficit means shortage of cash.
It occurs either due to limited market participation or because of decrease in
cash held by financial market participants.
System liquidity
RBI adds liquidity into the system by lending to banks and reduces liquidity into
the system by borrowing from banks.
20
System Liquidity Deficit
A broken credit system ,decline in deposit growth & falling domestic savings
rate all reflect in liquidity crunch.
The liquidity in the system was in a deficit mode since July last year,
peaking at 1 lakh crore in December last year.
This showed that banks were not getting adequate liquidity from the RBI
window for their daily mismatches, which affected money flowing from
banks to NBFCs and to other key sectors of the economy.
21
Post-demonetisation
Intervention by the RBI in
the foreign exchange market
to protect the rupee’s value
against the US dollar.
22
Other two factors that contributed to liquidity deficit : -
Lessons for policy makers…
The steps taken by the government and the RBI to infuse liquidity.
NBFCs need a boost as they play a crucial role.
A permanent liquidity window for NBFCs on the line of the National Housing Bank.
The cost of liquidity or funding has gone up substantially.
There is also an issue of financial stability.
23
Lessons for policy makers.
The economy
and the financial
system are two
sides of the
same coin.
The economy
cannot succeed
if the financial
system is
collapsing.
Crisis fighting
and
macroeconomic
policies have to
work together.
Government's
ability to limit
the intensity of a
financial crisis.
24