2024
Investor Day
APRIL 30, 2024
Demonstrate why we are
confident in our aspiration
to deliver 10%+ revenue
growth and mid-teens EPS
growth on a sustainable
basis.
Focus For Today
2
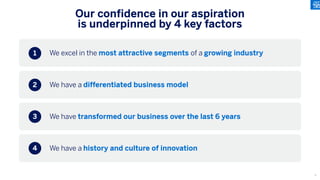
We excel in the most attractive segments of a growing industry
We have a differentiated business model
We have transformed our business over the last 6 years
We have a history and culture of innovation
1
2
3
4
Our confidence in our aspiration
is underpinned by 4 key factors
3
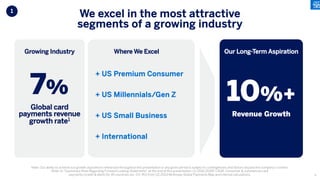
10%+
Revenue Growth
7%
Global card
payments revenue
growth rate1
Growing Industry
1
We excel in the most attractive
segments of a growing industry
Note: Our ability to achieve our growth aspirations referenced throughout this presentation in any given period is subject to contingencies and factors beyond the company's control.
Refer to "Cautionary Note Regarding Forward-Looking Statements" at the end of this presentation; (1) 2018-2026F CAGR; Consumer & commercial card
payments (credit & debit) for 45 countries (ex. CH, RU) from Q2 2023 McKinsey Global Payments Map and internal calculations.
Our Long-Term Aspiration
+ US Premium Consumer
+ US Millennials/Gen Z
+ US Small Business
+ International
Where We Excel
4
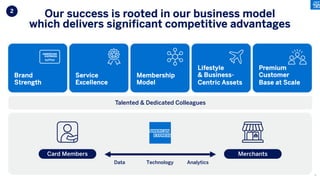
Brand
Strength
Service
Excellence
Membership
Model
Lifestyle
& Business-
Centric Assets
Premium
Customer
Base at Scale
Card Members Merchants
Data Analytics
Technology
Our success is rooted in our business model
which delivers significant competitive advantages
2
Talented & Dedicated Colleagues
5
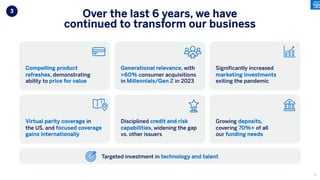
Compelling product
refreshes, demonstrating
ability to price for value
Generational relevance, with
>60% consumer acquisitions
in Millennials/Gen Z in 2023
Significantly increased
marketing investments
exiting the pandemic
Virtual parity coverage in
the US, and focused coverage
gains internationally
Disciplined credit and risk
capabilities, widening the gap
vs. other issuers
Growing deposits,
covering 70%+ of all
our funding needs
Targeted investment in technology and talent
3
Over the last 6 years, we have
continued to transform our business
6
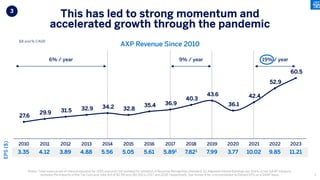
EPS
($)
3.35 4.12 3.89 4.88 5.56 5.05 5.61 5.891 7.821 7.99 3.77 10.02 9.85 11.21
3
This has led to strong momentum and
accelerated growth through the pandemic
Notes: Total revenue net of interest expense for 2015 and prior not restated for adoption of Revenue Recognition standard; (1) Adjusted Diluted Earnings per share, a non-GAAP measure,
excludes the impacts of the Tax Cuts and Jobs Act of $2.90 and ($0.09) in 2017 and 2018, respectively. See Annex A for a reconciliation to Diluted EPS on a GAAP basis.
9% / year 19% / year
6% / year
27.6
29.9 31.5 32.9 34.2 32.8
35.4 36.9
40.3
43.6
36.1
42.4
52.9
60.5
2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023
$B and % CAGR
7
AXP Revenue Since 2010
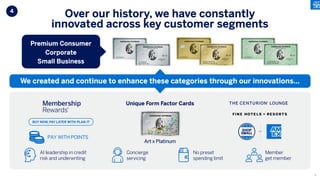
Premium Consumer
Corporate
Small Business
Unique Form Factor Cards
PAY WITH POINTS
4
Over our history, we have constantly
innovated across key customer segments
We created and continue to enhance these categories through our innovations…
AI leadership in credit
risk and underwriting
Concierge
servicing
Member
get member
No preset
spending limit
Art x Platinum
8
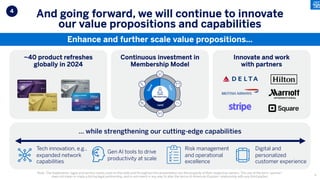
~40 product refreshes
globally in 2024
… while strengthening our cutting-edge capabilities
Continuous investment in
Membership Model
Innovate and work
with partners
Gen AI tools to drive
productivity at scale
Digital and
personalized
customer experience
Tech innovation, e.g.,
expanded network
capabilities
4
And going forward, we will continue to innovate
our value propositions and capabilities
Enhance and further scale value propositions…
Card
Membership
S
p
e
n
d
F
e
e
s
Lend
Risk management
and operational
excellence
Note: The trademarks, logos and service marks used on this slide and throughout this presentation are the property of their respective owners. The use of the term “partner”
does not mean or imply a formal legal partnership, and is not meant in any way to alter the terms of American Express’ relationship with any third parties. 9
We excel in the most attractive segments of a growing industry
Our differentiated business model
The continued successful execution of our strategy
A history and culture of innovation
1
2
3
4
These four factors will enable us to
achieve our long-term aspiration…
10
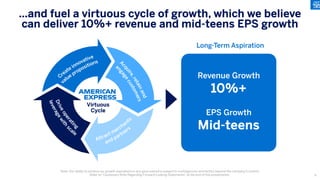
Long-Term Aspiration
Revenue Growth
10%+
EPS Growth
Mid-teens
…and fuel a virtuous cycle of growth, which we believe
can deliver 10%+ revenue and mid-teens EPS growth
Note: Our ability to achieve our growth aspirations in any given period is subject to contingencies and factors beyond the company's control.
Refer to "Cautionary Note Regarding Forward-Looking Statements" at the end of this presentation.
Virtuous
Cycle
11
Opening
Remarks
How We
Will Achieve
Our Long-Term
Aspiration
Why Continue
to Invest
in American
Express?
Q&A
1
2
3
4
Premium
growth
through our
Membership
Model
Howard Grosfield
President,
U.S. Consumer Services
Premium growth through
our Membership Model
Howard Grosfield
Winning the SME recovery
Anna Marrs
Runway for growth in
International
Rafa Marquez
Expanding network
coverage & capabilities
Raymond Joabar
Efficiency, growth & service
through technology
Anré Williams
12
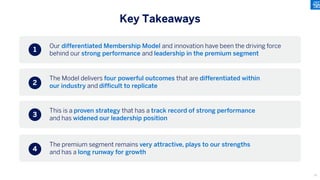
Our differentiated Membership Model and innovation have been the driving force
behind our strong performance and leadership in the premium segment
Key Takeaways
The Model delivers four powerful outcomes that are differentiated within
our industry and difficult to replicate
This is a proven strategy that has a track record of strong performance
and has widened our leadership position
The premium segment remains very attractive, plays to our strengths
and has a long runway for growth
1
2
3
4
13
Today’s Focus
How do
we execute and
innovate to deliver
on this model?
Why is there
a long runway
for accelerated
growth?
What is our
differentiated
Membership Model?
14
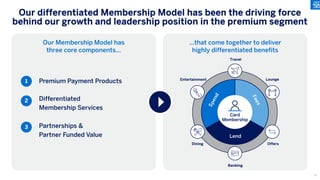
Our differentiated Membership Model has been the driving force
behind our growth and leadership position in the premium segment
Our Membership Model has
three core components…
…that come together to deliver
highly differentiated benefits
Premium Payment Products
Differentiated
Membership Services
Partnerships &
Partner Funded Value
1
2
3
Travel
Lounge
Offers
Banking
Entertainment
Dining
Card
Membership
S
p
e
n
d
F
e
e
s
Lend
15
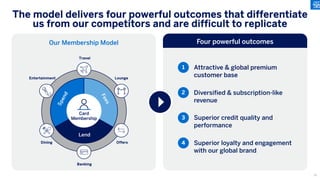
The model delivers four powerful outcomes that differentiate
us from our competitors and are difficult to replicate
Our Membership Model Four powerful outcomes
Attractive & global premium
customer base
Diversified & subscription-like
revenue
Superior credit quality and
performance
Superior loyalty and engagement
with our global brand
1
2
3
4
Travel
Lounge
Offers
Banking
Entertainment
Dining
Card
Membership
S
p
e
n
d
F
e
e
s
Lend
16
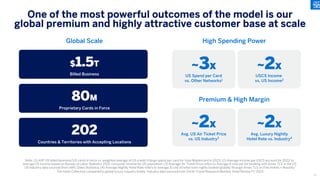
One of the most powerful outcomes of the model is our
global premium and highly attractive customer base at scale
Global Scale High Spending Power
Note: (1) AXP US billed business/US cards in force vs. weighted average of US credit/charge spend per card for Visa/Mastercard in 2023; (2) Average income per USCS account for 2022 vs.
average US income based on Bureau of Labor Statistics 2022 consumer income for US population; (3) Average Air Ticket Price refers to Average $ cost per Air booking with Amex TLS in the US.
US Industry data sourced from IARC Sales Statistics; (4) Average Nightly Hotel Rate refers to average $ cost of hotel room nights booked globally through Amex TLS on Fine Hotels + Resorts/
The Hotel Collection compared to global luxury industry hotels. Industry data sourced from Smith Travel Research Monthly Hotel Review FY 2023
~3x
US Spend per Card
vs. Other Networks1
~2x
USCS Income
vs. US Income2
Premium & High Margin
~2x
Avg. US Air Ticket Price
vs. US Industry3
~2x
Avg. Luxury Nightly
Hotel Rate vs. Industry4
$1.5T
Billed Business
80M
Proprietary Cards in Force
202
Countries & Territories with Accepting Locations
17
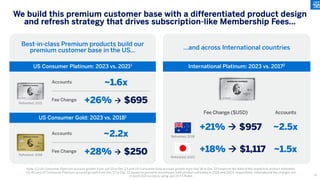
We build this premium customer base with a differentiated product design
and refresh strategy that drives subscription-like Membership Fees…
Note: (1) US Consumer Platinum account growth from Jun’21 to Dec’23 and US Consumer Gold account growth from Sep’18 to Dec’23 based on the date of the respective product refreshes;
(2) AU and JP Consumer Platinum account growth from Dec’17 to Dec’23 based on period to encompass both product refreshes in 2018 and 2023, respectively. International fee changes are
in local USD currency using Jan’24 FX Rates
…and across International countries
US Consumer Platinum: 2023 vs. 20211
US Consumer Gold: 2023 vs. 20181
International Platinum: 2023 vs. 20172
Best-in-class Premium products build our
premium customer base in the US…
Accounts ~1.6x
Fee Change +26% à $695
Accounts ~2.2x
Fee Change +28% à $250
Fee Change ($USD) Accounts
+21% à $957
+18% à $1,117
~2.5x
~1.5x
Refreshed: 2021
Refreshed: 2018
Refreshed: 2018
Refreshed: 2023
18
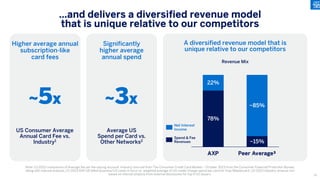
A diversified revenue model that is
unique relative to our competitors
78%
~15%
22%
~85%
AXP Peer Average³
…and delivers a diversified revenue model
that is unique relative to our competitors
Note: (1) 2022 comparison of Average fee per fee-paying account. Industry sourced from The Consumer Credit Card Market – October 2023 from the Consumer Financial Protection Bureau
along with internal analysis; (2) 2023 AXP US billed business/US cards in force vs. weighted average of US credit/charge spend per card for Visa/Mastercard; (3) 2023 industry revenue mix
based on internal analysis from external disclosures for top 5 US issuers
Net Interest
Income
Spend & Fee
Revenues
Revenue Mix
Higher average annual
subscription-like
card fees
US Consumer Average
Annual Card Fee vs.
Industry1
Average US
Spend per Card vs.
Other Networks2
Significantly
higher average
annual spend
~5x ~3x
19
2.3%
0.9%
1.7%
11.3% 11.6%
12.4%
2019 2022 2023
2.4%
2.0%
3.0%
1.6%
1.0%
1.4%
2019 2022 2023
Net Credit
Margin:
9.0%
10.7% 10.7%
88 bps
160 bps
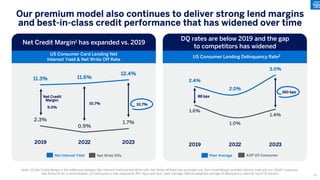
Our premium model also continues to deliver strong lend margins
and best-in-class credit performance that has widened over time
Note: (1) Net Credit Margin is the difference between Net Interest Yield and Net Write-offs. Net Write-off Rates are principal only. Net Credit Margin and Net Interest Yield are non-GAAP measures.
See Annex B for a reconciliation; (2) Delinquency rate represents 30+ days past due; peer average reflects weighted average of delinquency rates for top 5 US issuers
Peer Average AXP US Consumer
Net Interest Yield Net Write Offs
Net Credit Margin1 has expanded vs. 2019
DQ rates are below 2019 and the gap
to competitors has widened
US Consumer Card Lending Net
Interest Yield & Net Write Off Rate
US Consumer Lending Delinquency Rate2
20
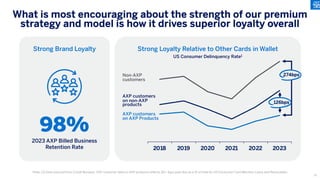
What is most encouraging about the strength of our premium
strategy and model is how it drives superior loyalty overall
Note: (1) Data sourced from Credit Bureaus. AXP customer data on AXP products reflects 30+ days past due as a % of total for US Consumer Card Member Loans and Receivables
Strong Brand Loyalty
98%
2023 AXP Billed Business
Retention Rate 2018 2019 2020 2021 2022 2023
126bps
274bps
AXP customers
on non-AXP
products
Non-AXP
customers
AXP customers
on AXP Products
Strong Loyalty Relative to Other Cards in Wallet
US Consumer Delinquency Rate1
21
How do
we execute and
innovate to deliver
on this model?
Why is there
a long runway
for accelerated
growth?
What is our
differentiated
Membership Model?
Today’s Focus
22
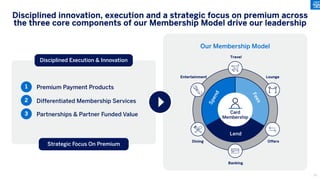
Disciplined innovation, execution and a strategic focus on premium across
the three core components of our Membership Model drive our leadership
Our Membership Model
Premium Payment Products
Differentiated Membership Services
Partnerships & Partner Funded Value
1
2
3
Disciplined Execution & Innovation
Strategic Focus On Premium
Travel
Lounge
Offers
Banking
Entertainment
Dining
Card
Membership
S
p
e
n
d
F
e
e
s
Lend
23
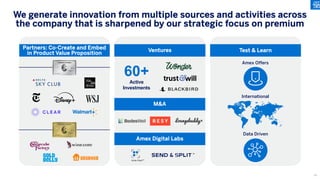
We generate innovation from multiple sources and activities across
the company that is sharpened by our strategic focus on premium
Partners: Co-Create and Embed
in Product Value Proposition
Test & Learn
Ventures
60+
Active
Investments
Amex Offers
International
Data Driven
M&A
Amex Digital Labs
24
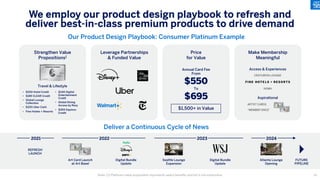
We employ our product design playbook to refresh and
deliver best-in-class premium products to drive demand
Note: (1) Platinum value proposition represents select benefits and list is not exhaustive
Our Product Design Playbook: Consumer Platinum Example
• $200 Hotel Credit
• $189 CLEAR Credit
• Global Lounge
Collection
• $200 Uber Cash
• Fine Hotels + Resorts
Travel & Lifestyle
• $240 Digital
Entertainment
Credit
• Global Dining
Access by Resy
• $300 Equinox
Credit
$1,500+ in Value
Annual Card Fee
From
$550
To
$695
CENTURION LOUNGE
NOMA
ARTIST CARDS
Access & Experiences
Aspirational
“MEMBER SINCE”
Strengthen Value
Propositions1
Leverage Partnerships
& Funded Value
Price
for Value
Make Membership
Meaningful
Deliver a Continuous Cycle of News
REFRESH
LAUNCH
Digital Bundle
Update
Art Card Launch
at Art Basel
Digital Bundle
Update
Seattle Lounge
Expansion
Atlanta Lounge
Opening
FUTURE
PIPELINE
2022 2023 2024
2021
25
Note: Avg Lend and Avg Spend behaviors for USCS refer to Average Revolving loans per Account and Average Billed Business per Account. Avg. lend, Avg. spend, and Avg. income for USCS
other age cohorts and industry Millennials & Gen Z are indexed to USCS Millennials & Gen Z, as applicable; Avg. Income for the industry is based on Bureau of Labor Statistics 2022 consumer
income as 2023 data is unavailable; Fee paying and avg. spend for industry sourced from Argus Advisory, a TransUnion Company; Industry FICO sourced from Experian
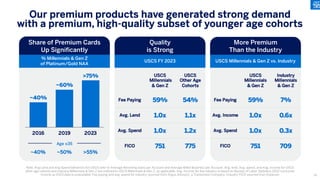
Our premium products have generated strong demand
with a premium, high-quality subset of younger age cohorts
~40%
~60%
>75%
2016 2019 2023
Age ≤35
USCS
Millennials
& Gen Z
USCS
Other Age
Cohorts
Fee Paying 59% 54%
Avg. Lend 1.0x 1.1x
Avg. Spend 1.0x 1.2x
FICO 751 775
USCS
Millennials
& Gen Z
Industry
Millennials
& Gen Z
Fee Paying 59% 7%
Avg. Income 1.0x 0.6x
Avg. Spend 1.0x 0.3x
FICO 751 709
~40% ~50% >55%
Share of Premium Cards
Up Significantly
% Millennials & Gen Z
of Platinum/Gold NAA
More Premium
Than the Industry
Quality
is Strong
USCS Millennials & Gen Z vs. Industry
USCS FY 2023
26
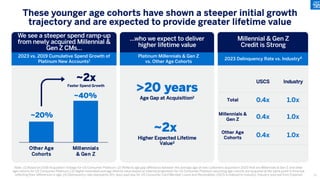
These younger age cohorts have shown a steeper initial growth
trajectory and are expected to provide greater lifetime value
Note: (1) Based on 2018 Acquisition Vintage for US Consumer Platinum; (2) Reflects age gap difference between the average age of new customers acquired in 2023 that are Millennials & Gen Z and other
age cohorts for US Consumer Platinum; (3) Higher estimated average lifetime value based on internal projections for US Consumer Platinum assuming age cohorts are acquired at the same point in time but
reflecting their differences in age; (4) Delinquency rate represents 30+ days past due for US Consumer Card Member Loans and Receivables; USCS is indexed to industry; Industry sourced from Experian
>20 years
Age Gap at Acquisition2
~2x
Higher Expected Lifetime
Value3
~20%
~40%
Other Age
Cohorts
Millennials
& Gen Z
~2x
Faster Spend Growth
USCS Industry
Total 0.4x 1.0x
Millennials &
Gen Z 0.4x 1.0x
Other Age
Cohorts 0.4x 1.0x
We see a steeper spend ramp-up
from newly acquired Millennial &
Gen Z CMs…
…who we expect to deliver
higher lifetime value
Millennial & Gen Z
Credit is Strong
2023 vs. 2019 Cumulative Spend Growth of
Platinum New Accounts1
Platinum Millennials & Gen Z
vs. Other Age Cohorts
2023 Delinquency Rate vs. Industry4
27
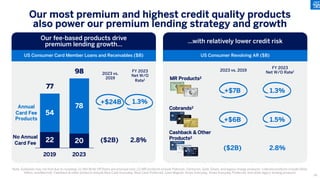
Our most premium and highest credit quality products
also power our premium lending strategy and growth
Note: Subtotals may not foot due to rounding; (1) Net Write Off Rates are principal only; (2) MR products include Platinum, Centurion, Gold, Green, and legacy charge products; Cobrand products include Delta,
Hilton, and Marriott; Cashback & other products include Blue Cash Everyday, Blue Cash Preferred, Cash Magnet, Amex Everyday, Amex Everyday Preferred, and other legacy lending products
2023 vs. 2019
MR Products2
Cobrands2
Cashback & Other
Products2
FY 2023
Net W/O Rate1
($2B)
+$24B
2.8%
1.3%
Annual
Card Fee
Products
No Annual
Card Fee
22 20
54
78
77
98
2019 2023
+$7B 1.3%
2023 vs.
2019
FY 2023
Net W/O
Rate1
+$6B 1.5%
($2B) 2.8%
…with relatively lower credit risk
US Consumer Revolving AR ($B)
Our fee-based products drive
premium lending growth…
US Consumer Card Member Loans and Receivables ($B)
28
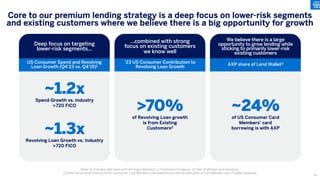
Note: (1) Industry data sourced from Argus Advisory, a TransUnion Company; (2) Net of attrited card members;
(3) Non-Amex lend of active Amex Consumer Card Members calculated from internal estimates of Card Member size of wallet capability
Core to our premium lending strategy is a deep focus on lower-risk segments
and existing customers where we believe there is a big opportunity for growth
~1.2x
Spend Growth vs. Industry
>720 FICO
~1.3x
Revolving Loan Growth vs. Industry
>720 FICO
~24%
of US Consumer Card
Members’ card
borrowing is with AXP
>70%
of Revolving Loan growth
is from Existing
Customers2
Deep focus on targeting
lower-risk segments…
We believe there is a large
opportunity to grow lending while
sticking to primarily lower-risk
existing customers
…combined with strong
focus on existing customers
we know well
US Consumer Spend and Revolving
Loan Growth (Q4‘23 vs. Q4‘19)1 AXP share of Lend Wallet3
‘23 US Consumer Contribution to
Revolving Loan Growth
29
Travel1 Offers
Dining
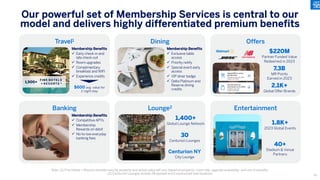
Note: (1) Fine Hotels + Resorts benefits vary by property and actual value will vary based on property, room rate, upgrade availability, and use of benefits;
(2) Centurion Lounges include 28 opened and 2 announced new locations
Our powerful set of Membership Services is central to our
model and delivers highly differentiated premium benefits
$220M
Partner Funded Value
Redeemed in 2023
2.1K+
Global Offer Brands
Membership Benefits
ü Early check-in and
late check-out
ü Room upgrades
ü Complimentary
breakfast and WIFI
ü Experience credits
$600 avg. value for
2-night stay
Membership Benefits
ü Exclusive table
access
ü Priority notify
ü Special event early
access
ü VIP diner badge
ü Delta Platinum and
Reserve dining
credits
7.3B
MR Points
Earned in 2023
Banking Entertainment
Lounge2
1.8K+
2023 Global Events
Membership Benefits
ü Competitive APYs
ü Membership
Rewards on debit
ü No-to-low everyday
banking fees
40+
Stadium & Venue
Partners
1,400+
Global Lounge Network
30
Centurion Lounges
Centurion NY
City Lounge
1,500+
F IN E H O T E L S
+ R E S O R T S ®
30
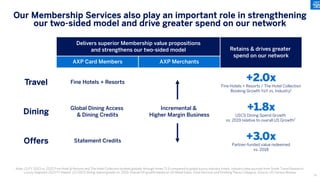
Note: (1) FY 2023 vs. 2022 Fine Hotel & Resorts and The Hotel Collection booked globally through Amex TLS compared to global luxury industry hotels. Industry data sourced from Smith Travel Research,
Luxury Segment 2023 FY Report; (2) USCS Dining spend growth vs. 2019; Overall US growth based on US Retail Sales: Food Services and Drinking Places Category. Source: US Census Bureau
Our Membership Services also play an important role in strengthening
our two-sided model and drive greater spend on our network
Delivers superior Membership value propositions
and strengthens our two-sided model Retains & drives greater
spend on our network
AXP Card Members AXP Merchants
Travel Fine Hotels + Resorts +2.0x
Fine Hotels + Resorts / The Hotel Collection
Booking Growth YoY vs. Industry1
Dining
Global Dining Access
& Dining Credits
Incremental &
Higher Margin Business
+1.8x
USCS Dining Spend Growth
vs. 2019 relative to overall US Growth2
Offers Statement Credits +3.0x
Partner-funded value redeemed
vs. 2018
31
Investments and innovation in Travel are paying off as we
outperform the industry in premium performance and growth
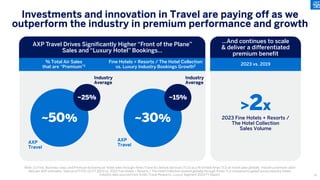
Note: (1) First, Business class, and Premium Economy air ticket sales through Amex Travel & Lifestyle Services (TLS) as a % of total Amex TLS air ticket sales globally. Industry premium cabin
data per AXP estimates. Data as of FY23; (2) FY 2023 vs. 2022 Fine Hotels + Resorts / The Hotel Collection booked globally through Amex TLS compared to global luxury industry hotels.
Industry data sourced from Smith Travel Research, Luxury Segment 2023 FY Report
>2x
2023 Fine Hotels + Resorts /
The Hotel Collection
Sales Volume
~50%
~25%
Industry
Average
AXP
Travel
~30%
~15%
Industry
Average
AXP
Travel
AXP Travel Drives Significantly Higher “Front of the Plane”
Sales and “Luxury Hotel” Bookings…
…And continues to scale
& deliver a differentiated
premium benefit
% Total Air Sales
that are “Premium”1
Fine Hotels + Resorts / The Hotel Collection
vs. Luxury Industry Bookings Growth2 2023 vs. 2019
32
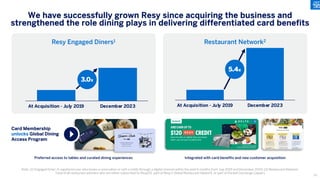
At Acquisition - July 2019 December 2023
Card Membership
unlocks Global Dining
Access Program
We have successfully grown Resy since acquiring the business and
strengthened the role dining plays in delivering differentiated card benefits
Note: (1) Engaged Diner: A registered user who books a reservation or sets a notify through a digital channel within the past 6 months from July 2019 and December 2023; (2) Restaurant Network:
Total of all restaurant partners who are either subscribed to ResyOS, part of Resy's Global Restaurant Network, or part of Pocket Concierge (Japan)
Resy Engaged Diners1 Restaurant Network2
Preferred access to tables and curated dining experiences Integrated with card benefits and new customer acquisition
3.0x
5.4x
back annually on eligible Resy purchases
when you use your enrolled Card.
33
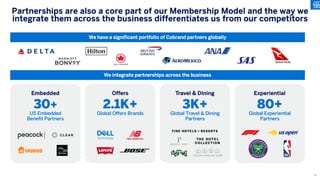
We have a significant portfolio of Cobrand partners globally
Travel & Dining
3K+
Global Travel & Dining
Partners
Experiential
80+
Global Experiential
Partners
Offers
2.1K+
Global Offers Brands
Partnerships are also a core part of our Membership Model and the way we
integrate them across the business differentiates us from our competitors
Embedded
30+
US Embedded
Benefit Partners
We integrate partnerships across the business
34
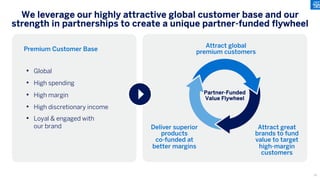
• Global
• High spending
• High margin
• High discretionary income
• Loyal & engaged with
our brand
We leverage our highly attractive global customer base and our
strength in partnerships to create a unique partner-funded flywheel
Premium Customer Base
Attract global
premium customers
Attract great
brands to fund
value to target
high-margin
customers
Deliver superior
products
co-funded at
better margins
Partner-Funded
Value Flywheel
35
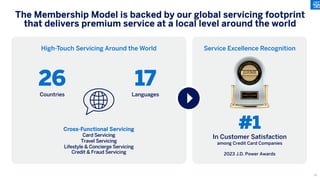
26
Countries
The Membership Model is backed by our global servicing footprint
that delivers premium service at a local level around the world
High-Touch Servicing Around the World
17
Languages
#1
In Customer Satisfaction
among Credit Card Companies
2023 J.D. Power Awards
Service Excellence Recognition
Cross-Functional Servicing
Card Servicing
Travel Servicing
Lifestyle & Concierge Servicing
Credit & Fraud Servicing
36
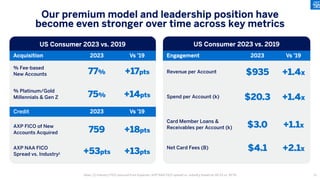
Acquisition 2023 Vs ’19
% Fee-based
New Accounts 77% +17pts
% Platinum/Gold
Millennials & Gen Z 75% +14pts
Credit 2023 Vs ’19
AXP FICO of New
Accounts Acquired 759 +18pts
AXP NAA FICO
Spread vs. Industry1 +53pts +13pts
Engagement 2023 Vs ’19
Revenue per Account $935 +1.4x
Spend per Account (k) $20.3 +1.4x
Card Member Loans &
Receivables per Account (k) $3.0 +1.1x
Net Card Fees (B) $4.1 +2.1x
Our premium model and leadership position have
become even stronger over time across key metrics
Note: (1) Industry FICO sourced from Experian; AXP NAA FICO spread vs. industry based on 1H’23 vs. 1H’19
US Consumer 2023 vs. 2019
37
Why is there
a long runway
for accelerated
growth?
What is our
differentiated
Membership Model?
How do
we execute and
innovate to deliver
on this model?
Today’s Focus
38
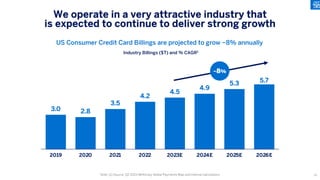
3.0 2.8
3.5
4.2
4.5
4.9
5.3 5.7
2019 2020 2021 2022 2023E 2024E 2025E 2026E
We operate in a very attractive industry that
is expected to continue to deliver strong growth
Note: (1) Source: Q2 2023 McKinsey Global Payments Map and internal calculations
~8%
Industry Billings ($T) and % CAGR1
US Consumer Credit Card Billings are projected to grow ~8% annually
39
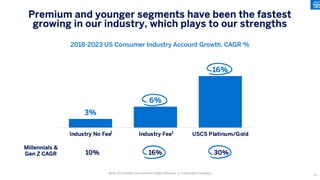
10% 16% 30%
3%
6%
16%
Industry No Fee Industry Fee USCS Platinum/Gold
Premium and younger segments have been the fastest
growing in our industry, which plays to our strengths
Note: (1) Industry sourced from Argus Advisory, a TransUnion Company
2018-2023 US Consumer Industry Account Growth, CAGR %
Millennials &
Gen Z CAGR
40
1 1
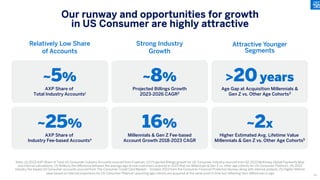
Our runway and opportunities for growth
in US Consumer are highly attractive
Note: (1) 2023 AXP Share of Total US Consumer Industry Accounts sourced from Experian; (2) Projected Billings growth for US Consumer Industry sourced from Q2 2023 McKinsey Global Payments Map
and internal calculations; (3) Reflects the difference between the average age of new customers acquired in 2023 that are Millennials & Gen Z vs. other age cohorts for US Consumer Platinum; (4) 2022
industry fee-based US Consumer accounts sourced from The Consumer Credit Card Market – October 2023 from the Consumer Financial Protection Bureau along with internal analysis; (5) Higher lifetime
value based on internal projections for US Consumer Platinum assuming age cohorts are acquired at the same point in time but reflecting their differences in age
~5%
AXP Share of
Total Industry Accounts1
~8%
Projected Billings Growth
2023-2026 CAGR2
>20years
Age Gap at Acquisition Millennials &
Gen Z vs. Other Age Cohorts3
~25%
AXP Share of
Industry Fee-based Accounts4
16%
Millennials & Gen Z Fee-based
Account Growth 2018-2023 CAGR
~2x
Higher Estimated Avg. Lifetime Value
Millennials & Gen Z vs. Other Age Cohorts5
Relatively Low Share
of Accounts
Strong Industry
Growth
Attractive Younger
Segments
41
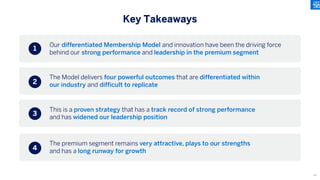
Our differentiated Membership Model and innovation have been the driving force
behind our strong performance and leadership in the premium segment
Key Takeaways
The Model delivers four powerful outcomes that are differentiated within
our industry and difficult to replicate
This is a proven strategy that has a track record of strong performance
and has widened our leadership position
The premium segment remains very attractive, plays to our strengths
and has a long runway for growth
1
2
3
4
42
Opening
Remarks
How We
Will Achieve
Our Long-Term
Aspiration
Why Continue
to Invest
in American
Express?
Q&A
43
1
2
3
4
Premium growth through
our Membership Model
Howard Grosfield
Winning the SME recovery
Anna Marrs
Runway for growth in
International
Rafa Marquez
Expanding network
coverage & capabilities
Raymond Joabar
Efficiency, growth & service
through technology
Anré Williams
Winning
the SME
recovery
Anna Marrs
Group President, Global
Commercial Services and
Credit & Fraud Risk
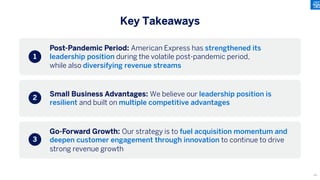
Post-Pandemic Period: American Express has strengthened its
leadership position during the volatile post-pandemic period,
while also diversifying revenue streams
Small Business Advantages: We believe our leadership position is
resilient and built on multiple competitive advantages
Go-Forward Growth: Our strategy is to fuel acquisition momentum and
deepen customer engagement through innovation to continue to drive
strong revenue growth
1
2
3
Key Takeaways
44
International is accretive to AXP revenue growth
Post-Pandemic
Period
Small Business
Advantages
Go-Forward
Growth
Today’s Focus
45
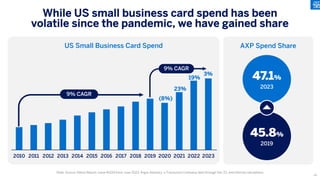
US Small Business Card Spend AXP Spend Share
While US small business card spend has been
volatile since the pandemic, we have gained share
Note: Source: Nilson Report, Issue #1243 from June 2023, Argus Advisory, a Transunion Company data through Dec’23, and internal calculations
2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023
(8%)
23%
19%
3%
9% CAGR
9% CAGR
47.1%
2023
45.8%
2019
46
3%
(14%)
19%
13%
(2%) (3%)
6%
5%
7%
8%
7% 6%
(3%)
(3%)
(2%) (2%)
(2%) (2%)
2019 2020 2021 2022 2023 Q1'24
3%
(14%)
19%
13%
(2%) (4%) (3%)
6%
5%
7%
8%
7% 6% 6%
(3%)
(3%)
(2%) (2%)
(2%)
(2%) (2%)
2019 2020 2021 2022 2023 Q4'23 Q1'24
Note: Totals may not foot due to rounding, (1) New account spend ≤13 months of tenure
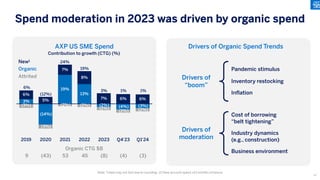
AXP US SME Spend Drivers of Organic Spend Trends
Spend moderation in 2023 was driven by organic spend
Drivers of
“boom”
Drivers of
moderation
Pandemic stimulus
Inventory restocking
Inflation
Cost of borrowing
“belt tightening”
Industry dynamics
(e.g., construction)
Business environment
9 (43) 53 45 (8) (4) (3)
Contribution to growth (CTG) (%)
Organic CTG $B
Organic
Attrited
New1
6%
(12%)
24%
19%
3% 1%
1%
47
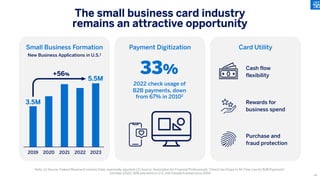
The small business card industry
remains an attractive opportunity
Small Business Formation Card Utility
Payment Digitization
Note: (1) Source: Federal Reserve Economic Data, seasonally adjusted; (2) Source: Association for Financial Professionals “Check Use Drops to All-Time Low for B2B Payments”
(October 2022), B2B payments in U.S. and Canada tracked since 2004
2019 2020 2021 2022 2023
New Business Applications in U.S.1
+56% 33%
2022 check usage of
B2B payments, down
from 67% in 20102
Purchase and
fraud protection
Cash flow
flexibility
Rewards for
business spend
3.5M
5.5M
48
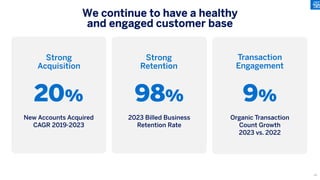
Strong
Acquisition
Strong
Retention
Transaction
Engagement
We continue to have a healthy
and engaged customer base
20%
New Accounts Acquired
CAGR 2019-2023
98%
2023 Billed Business
Retention Rate
9%
Organic Transaction
Count Growth
2023 vs. 2022
49
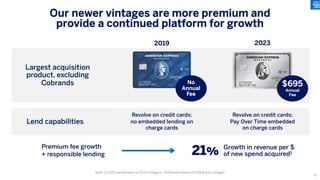
Note: (1) 2023 performance of 2022 vintage vs. 2019 performance of 2018 & prior vintages
Our newer vintages are more premium and
provide a continued platform for growth
2019 2023
No
Annual
Fee
$695
Annual
Fee
Largest acquisition
product, excluding
Cobrands
Lend capabilities
Revolve on credit cards;
Pay Over Time embedded
on charge cards
Revolve on credit cards;
no embedded lending on
charge cards
Premium fee growth
+ responsible lending
Growth in revenue per $
of new spend acquired1
21%
50
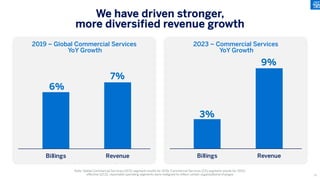
3%
9%
Billings Revenue
6%
7%
Billings Revenue
We have driven stronger,
more diversified revenue growth
Note: Global Commercial Services (GCS) segment results for 2019, Commercial Services (CS) segment results for 2023;
effective Q3'22, reportable operating segments were realigned to reflect certain organizational changes
2019 – Global Commercial Services
YoY Growth
2023 – Commercial Services
YoY Growth
51
International is accretive to AXP revenue growth
Post-Pandemic
Period
Small Business
Advantages
Go-Forward
Growth
Today’s Focus
52
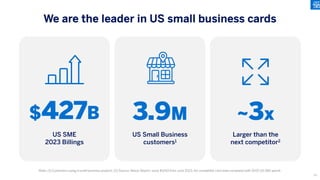
We are the leader in US small business cards
$427B 3.9M ~3x
Note: (1) Customers using a small business product; (2) Source: Nilson Report, Issue #1243 from June 2023, for competitor card data compared with 2022 US SBS spend.
US SME
2023 Billings
Larger than the
next competitor2
US Small Business
customers1
53
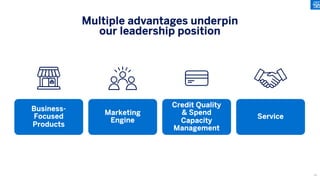
Multiple advantages underpin
our leadership position
Marketing
Engine
Credit Quality
& Spend
Capacity
Management
Service
Business-
Focused
Products
54
2019 2023
Competitor Cards
in Wallet
AXP
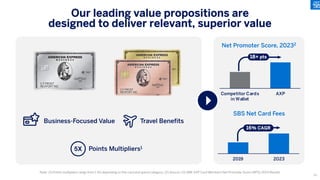
Net Promoter Score, 20232
Business-Focused Value
Points Multipliers1
Travel Benefits
Our leading value propositions are
designed to deliver relevant, superior value
Note: (1) Points multipliers range from 1-5X depending on the card and spend category; (2) Source: US SME AXP Card Members Net Promoter Score (NPS) 2023 Results
SBS Net Card Fees
16% CAGR
18+ pts
55
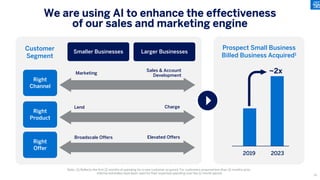
We are using AI to enhance the effectiveness
of our sales and marketing engine
2019 2023
Prospect Small Business
Billed Business Acquired1
Right
Channel
Right
Product
Right
Offer
Customer
Segment
Smaller Businesses Larger Businesses
Marketing
Sales & Account
Development
Lend Charge
Broadscale Offers Elevated Offers
~2x
Note: (1) Reflects the first 12 months of spending for a new customer acquired. For customers acquired less than 12 months prior,
internal estimates have been used for their expected spending over the 12 month period
56
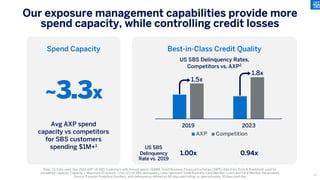
Spend Capacity
~3.3x
Our exposure management capabilities provide more
spend capacity, while controlling credit losses
Note: (1) Data used: Sep 2023 AXP US SBS Customers with Annual spend >$1MM, Small Business Financial Exchange (SBFE) data from Duns & Bradstreet used for
competitor capacity. Capacity = Maximum (Exposure, Line) (2) US SBS delinquency rates represent Small Business Card Member Loans and Card Member Receivables.
Source: Experian Analytical Sandbox, with delinquency defined as 60 days past billing, or approximately 30 days past due
Best-in-Class Credit Quality
2019 2023
AXP Competition
US SBS Delinquency Rates,
Competitors vs. AXP2
1.5x
1.8x
Avg AXP spend
capacity vs competitors
for SBS customers
spending $1M+1
US SBS
Delinquency
Rate vs. 2019
1.00x 0.94x
57
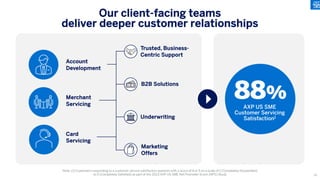
Our client-facing teams
deliver deeper customer relationships
88%
AXP US SME
Customer Servicing
Satisfaction1
Note: (1) Customers responding to a customer service satisfaction question with a score of 4 or 5 on a scale of 1 (Completely Dissatisfied)
to 5 (Completely Satisfied) as part of the 2023 AXP US SME Net Promoter Score (NPS) Study
B2B Solutions
Underwriting
Marketing
Offers
Trusted, Business-
Centric Support
Card
Servicing
Merchant
Servicing
Account
Development
58
International is accretive to AXP revenue growth
Post-Pandemic
Period
Small Business
Advantages
Go-Forward
Growth
Today’s Focus
59
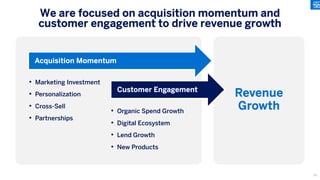
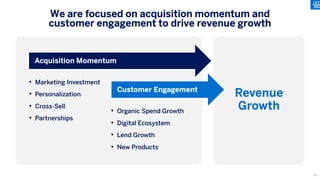
Revenue
Growth
• Organic Spend Growth
• Digital Ecosystem
• Lend Growth
• New Products
• Marketing Investment
• Personalization
• Cross-Sell
• Partnerships
Acquisition Momentum
Customer Engagement
We are focused on acquisition momentum and
customer engagement to drive revenue growth
60
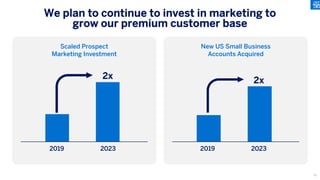
Scaled Prospect
Marketing Investment
New US Small Business
Accounts Acquired
We plan to continue to invest in marketing to
grow our premium customer base
2019 2023 2019 2023
2x
2x
61
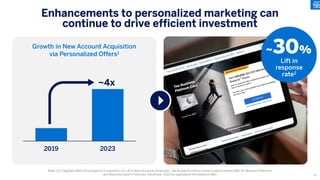
~30%
Lift in
response
rate2
2019 2023
Note: (1) Targeted offers for prospects/customers (2) Lift in New Accounts Acquired / site & search visitors shown a personalized offer for Business Platinum
and Business Gold in February-December 2023 as opposed to the baseline offer
Growth in New Account Acquisition
via Personalized Offers1
Enhancements to personalized marketing can
continue to drive efficient investment
~4x
62
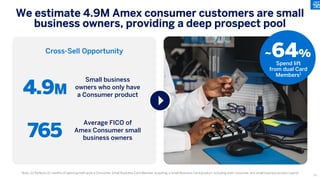
~64%
Spend lift
from dual Card
Members1
Note: (1) Reflects 12 months of spend growth post a Consumer Small Business Card Member acquiring a Small Business Card product, including both consumer and small business product spend
Cross-Sell Opportunity
We estimate 4.9M Amex consumer customers are small
business owners, providing a deep prospect pool
4.9M
765
Small business
owners who only have
a Consumer product
Average FICO of
Amex Consumer small
business owners
63
The strength of our partnerships creates customer
value and acquisition opportunities
Cobrand Partnerships Solution Partnerships
Partner Benefits
64
We are focused on acquisition momentum and
customer engagement to drive revenue growth
Revenue
Growth
• Organic Spend Growth
• Digital Ecosystem
• Lend Growth
• New Products
• Marketing Investment
• Personalization
• Cross-Sell
• Partnerships
Acquisition Momentum
Customer Engagement
65
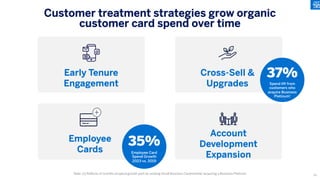
Note: (1) Reflects 12 months of spend growth post an existing Small Business Cardmember acquiring a Business Platinum
Customer treatment strategies grow organic
customer card spend over time
Spend lift from
customers who
acquire Business
Platinum1
37%
Early Tenure
Engagement
Cross-Sell &
Upgrades
Employee
Cards Employee Card
Spend Growth
2023 vs. 2019
35%
Account
Development
Expansion
66
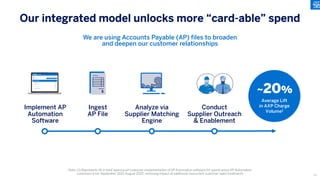
Note: (1) Represents lift in total spend post customer implementation of AP Automation software for spend active AP Automation
customers from September 2021-August 2022, removing impact of additional concurrent customer sales treatments
Our integrated model unlocks more “card-able” spend
We are using Accounts Payable (AP) files to broaden
and deepen our customer relationships
Average Lift
in AXP Charge
Volume1
Implement AP
Automation
Software
Ingest
AP File
Analyze via
Supplier Matching
Engine
Conduct
Supplier Outreach
& Enablement
~20%
67
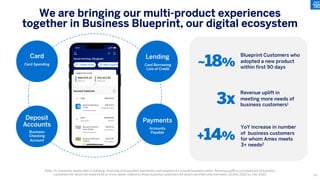
Deposit
Accounts
Business
Checking
Account
Card
Card Spending
Lending
Card Borrowing
Line of Credit
Payments
Accounts
Payable
Note: (1) Customer needs refer to banking, financing and payment operations and solutions for a small business owner. Revenue uplift is a comparison of business
customers for whom we meet three or more needs relative to those business customers for whom we meet only one need. (2) Dec 2023 vs. Dec 2022
We are bringing our multi-product experiences
together in Business Blueprint, our digital ecosystem
3x
Revenue uplift in
meeting more needs of
business customers1
+14%
YoY increase in number
of business customers
for whom Amex meets
3+ needs2
~18%
Blueprint Customers who
adopted a new product
within first 90 days
68
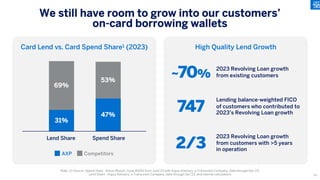
We still have room to grow into our customers’
on-card borrowing wallets
Card Lend vs. Card Spend Share1 (2023) High Quality Lend Growth
Note: (1) Source: Spend share - Nilson Report, Issue #1243 from June’23 with Argus Advisory, a Transunion Company, data through Dec’23;
Lend Share - Argus Advisory, a Transunion Company, data through Dec’23, and internal calculations
~70%
747
2/3
2023 Revolving Loan growth
from existing customers
Lending balance-weighted FICO
of customers who contributed to
2023’s Revolving Loan growth
2023 Revolving Loan growth
from customers with >5 years
in operation
47%
53%
31%
69%
Spend Share
Lend Share
Competitors
AXP
69
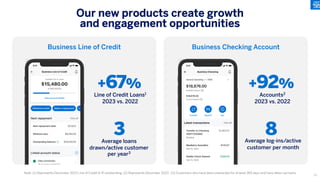
Our new products create growth
and engagement opportunities
Business Line of Credit Business Checking Account
Note: (1) Represents December 2023 Line of Credit A/R outstanding, (2) Represents December 2023 , (3) Customers who have been onboarded for at least 365 days and have taken out loans
+67%
3
+92%
8
Line of Credit Loans1
2023 vs. 2022
Accounts2
2023 vs. 2022
Average loans
drawn/active customer
per year3
Average log-ins/active
customer per month
70
Post-Pandemic Period: American Express has strengthened its
leadership position during the volatile post-pandemic period,
while also diversifying revenue streams
Small Business Advantages: We believe our leadership position is
resilient and built on multiple competitive advantages
Go-Forward Growth: Our strategy is to fuel acquisition momentum and
deepen customer engagement through innovation to continue to drive
strong revenue growth
1
2
3
Key Takeaways
71
Opening
Remarks
How We
Will Achieve
Our Long-Term
Aspiration
Why Continue
to Invest
in American
Express?
Q&A
72
1
2
3
4
Premium growth through
our Membership Model
Howard Grosfield
Winning the SME recovery
Anna Marrs
Runway for growth in
International
Rafa Marquez
Expanding network
coverage & capabilities
Raymond Joabar
Efficiency, growth & service
through technology
Anré Williams
Runway for
growth in
International
Rafa Marquez
President,
International Card Services
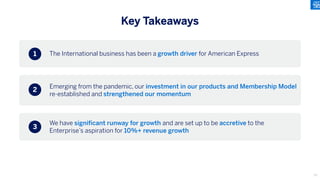
The International business has been a growth driver for American Express
Emerging from the pandemic, our investment in our products and Membership Model
re-established and strengthened our momentum
We have significant runway for growth and are set up to be accretive to the
Enterprise’s aspiration for 10%+ revenue growth
1
2
3
Key Takeaways
73
Today’s Focus
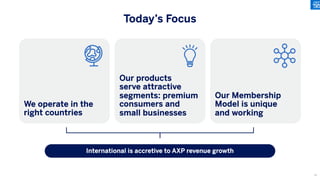
International is accretive to AXP revenue growth
We operate in the
right countries
Our products
serve attractive
segments: premium
consumers and
small businesses
Our Membership
Model is unique
and working
74
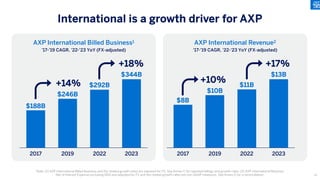
2017 2019 2022 2023
$188B
$246B
$292B
$344B
2017 2019 2022 2023
$8B
$10B
$11B
$13B
International is a growth driver for AXP
Note: (1) AXP International Billed Business and the related growth rates are adjusted for FX. See Annex C for reported billings and growth rates; (2) AXP International Revenue
Net of Interest Expense excluding GNS and adjusted for FX and the related growth rates are non-GAAP measures. See Annex D for a reconciliation.
+14%
+18%
+10%
+17%
AXP International Billed Business1 AXP International Revenue2
’17-’19 CAGR, ’22-’23 YoY (FX-adjusted) ’17-’19 CAGR, ’22-’23 YoY (FX-adjusted)
75
What drives International growth?
International is accretive to AXP revenue growth
We operate in the
right countries
Our products
serve attractive
segments: premium
consumers and
small businesses
Our Membership
Model is unique
and working
76
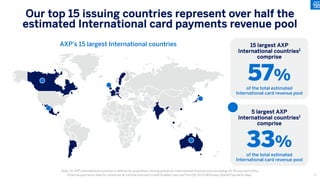
Our top 15 issuing countries represent over half the
estimated International card payments revenue pool
15 largest AXP
International countries1
comprise
57%
of the total estimated
International card revenue pool
5 largest AXP
International countries1
comprise
33%
of the total estimated
International card revenue pool
AXP’s 15 largest International countries
Note: (1) AXP International countries is defined by proprietary issuing presence. International revenue pool excluding US, Russia and China.
External payments data for consumer & commercial card (credit & debit) sourced from Q2 2023 McKinsey Global Payments Map. 77
2017 2019 2022 2023
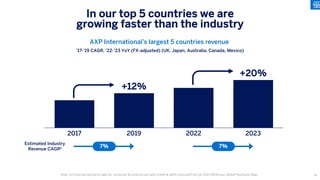
In our top 5 countries we are
growing faster than the industry
Note: (1) External payments data for consumer & commercial card (credit & debit) sourced from Q2 2023 McKinsey Global Payments Map.
+12%
+20%
Estimated Industry
Revenue CAGR1
AXP International’s largest 5 countries revenue
’17-’19 CAGR, ’22-’23 YoY (FX-adjusted) (UK, Japan, Australia, Canada, Mexico)
7% 7%
78
2017 2019 2022 2023
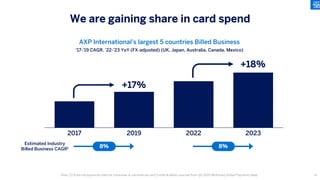
We are gaining share in card spend
Note: (1) External payments data for consumer & commercial card (credit & debit) sourced from Q2 2023 McKinsey Global Payments Map.
+17%
+18%
AXP International’s largest 5 countries Billed Business
’17-’19 CAGR, ’22-’23 YoY (FX-adjusted) (UK, Japan, Australia, Canada, Mexico)
Estimated Industry
Billed Business CAGR1 8% 8%
79
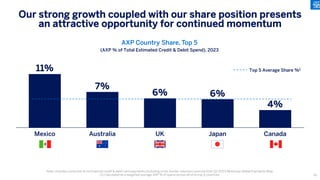
AXP Country Share, Top 5
(AXP % of Total Estimated Credit & Debit Spend), 2023
11%
7%
6% 6%
4%
Mexico Australia UK Japan Canada
Our strong growth coupled with our share position presents
an attractive opportunity for continued momentum
Note: Includes consumer & commercial credit & debit card payments (including cross-border volumes) sourced from Q2 2023 McKinsey Global Payments Map;
(1) Calculated as a weighted average AXP % of spend across all of its top 5 countries.
Top 5 Average Share %1
80
What drives International growth?
International is accretive to AXP revenue growth
We operate in the
right countries
Our products
serve attractive
segments: premium
consumers and
small businesses
Our Membership
Model is unique
and working
81
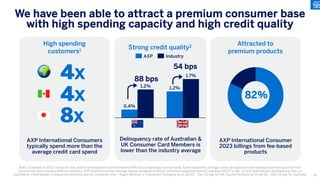
AXP International Consumers
typically spend more than the
average credit card spend
Delinquency rate of Australian &
UK Consumer Card Members is
lower than the industry average
4x
4x
8x
AXP International Consumer
2023 billings from fee-based
products
High spending
customers1
Attracted to
premium products
Strong credit quality2
82%
We have been able to attract a premium consumer base
with high spending capacity and high credit quality
Note: (1) Based on 2023 consumer only and for International countries where AXP has a proprietary issuing model. External data for average credit card spend in International countries sourced from
Euromonitor and excludes debit transactions. AXP and Euromonitor Average Spend compared in $USD converted using Euromonitor supplied 2023 FX rate. (2) AXP and Industry Delinquency rates as
reported by credit bureau in respective countries and for Consumer only – Argus Advisory, a TransUnion Company as of Jan’23 – Dec’23 avg. for UK, Equifax Australia as of Jan’23 – Dec’23 avg. for Australia.
0.4%
1.2% 1.2%
1.7%
88 bps
54 bps
AXP Industry
82
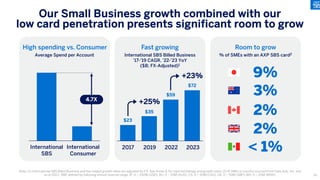
Our Small Business growth combined with our
low card penetration presents significant room to grow
Note: (1) International SBS Billed Business and the related growth rates are adjusted for FX. See Annex E for reported billings and growth rates; (2) # SMEs in country sourced from Data Axle, Inc. and
as of 2023. SME defined by following annual revenue range JP: 0 – 250M (USD), AU: 0 – 50M (AUD), CA: 0 – 50M (CAD), UK: 0 – 50M (GBP), MX: 0 – 20M (MXN).
International
SBS
International
Consumer
9%
3%
2%
2%
< 1%
$23
$35
$59
$72
2017 2019 2022 2023
+25%
+23%
High spending vs. Consumer Room to grow
Fast growing
Average Spend per Account % of SMEs with an AXP SBS card2
International SBS Billed Business
’17-’19 CAGR, ’22-’23 YoY
($B; FX-Adjusted)1
4.7X
83
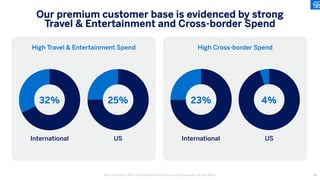
High Travel & Entertainment Spend High Cross-border Spend
Note: Spend for AXP International Proprietary Issuing (excludes JVs and GNS).
Our premium customer base is evidenced by strong
Travel & Entertainment and Cross-border Spend
32% 25%
International US
23% 4%
International US
84
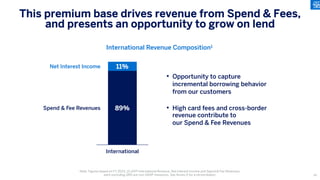
International Revenue Composition1
This premium base drives revenue from Spend & Fees,
and presents an opportunity to grow on lend
Note: Figures based on FY 2023. (1) AXP International Revenue, Net Interest Income and Spend & Fee Revenues,
each excluding GNS are non-GAAP measures. See Annex D for a reconciliation.
89%
11%
International
Spend & Fee Revenues
Net Interest Income
• Opportunity to capture
incremental borrowing behavior
from our customers
• High card fees and cross-border
revenue contribute to
our Spend & Fee Revenues
85
What drives International growth?
International is accretive to AXP revenue growth
We operate in the
right countries
Our products
serve attractive
segments: premium
consumers and
small businesses
Our Membership
Model is unique
and working
86
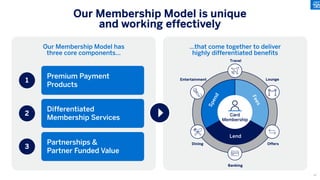
Our Membership Model has
three core components…
Our Membership Model is unique
and working effectively
Premium Payment
Products
Differentiated
Membership Services
Partnerships &
Partner Funded Value
1
…that come together to deliver
highly differentiated benefits
2
3
Travel
Lounge
Offers
Banking
Entertainment
Dining
Card
Membership
S
p
e
n
d
F
e
e
s
Lend
87
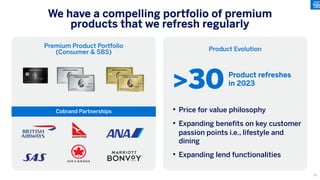
Premium Product Portfolio
(Consumer & SBS) Product Evolution
We have a compelling portfolio of premium
products that we refresh regularly
Cobrand Partnerships • Price for value philosophy
• Expanding benefits on key customer
passion points i.e., lifestyle and
dining
• Expanding lend functionalities
>30 Product refreshes
in 2023
88
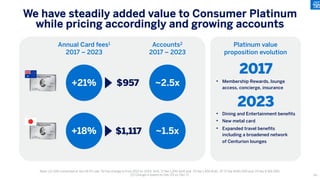
We have steadily added value to Consumer Platinum
while pricing accordingly and growing accounts
Note: (1) USD converted at Jan’24 FX rate. % Fee change is from 2017 to 2023. AUS ’17 fee 1,200 AUD and ’23 fee 1,450 AUD. JP ’17 fee ¥140,000 and ’23 fee ¥ 165,000.
(2) Change is based on Dec’23 vs. Dec’17.
Platinum value
proposition evolution
Annual Card fees1
2017 – 2023
Accounts2
2017 – 2023
2017
• Membership Rewards, lounge
access, concierge, insurance
2023
• Dining and Entertainment benefits
• New metal card
• Expanded travel benefits
including a broadened network
of Centurion lounges
$957
$1,117
+21%
+18%
~2.5x
~1.5x
89
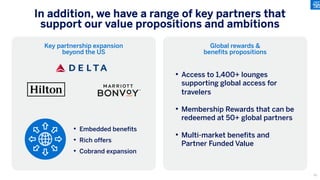
In addition, we have a range of key partners that
support our value propositions and ambitions
Key partnership expansion
beyond the US
Global rewards &
benefits propositions
• Access to 1,400+ lounges
supporting global access for
travelers
• Membership Rewards that can be
redeemed at 50+ global partners
• Multi-market benefits and
Partner Funded Value
• Embedded benefits
• Rich offers
• Cobrand expansion
90
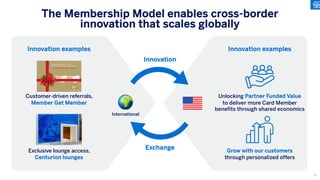
The Membership Model enables cross-border
innovation that scales globally
Innovation examples Innovation examples
Customer-driven referrals,
Member Get Member
Exclusive lounge access,
Centurion lounges
Unlocking Partner Funded Value
to deliver more Card Member
benefits through shared economics
Grow with our customers
through personalized offers
International
Innovation
Exchange
91
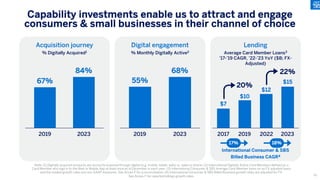
Acquisition journey Lending
Digital engagement
% Digitally Acquired1 Average Card Member Loans3
’17-’19 CAGR, ’22-’23 YoY ($B; FX-
Adjusted)
% Monthly Digitally Active2
Note: (1) Digitally acquired accounts are accounts acquired through digital (e.g. mobile, tablet, web) vs. sales or phone; (2) International Digitally Active Card Members defined as a
Card Member who logs in to the Web or Mobile App at least once as of December in each year; (3) International Consumer & SBS Average Card Member loans on an FX adjusted basis
and the related growth rates are non-GAAP measures. See Annex F for a reconciliation; (4) International Consumer & SBS Billed Business growth rates are adjusted for FX.
See Annex F for reported billings growth rates.
Capability investments enable us to attract and engage
consumers & small businesses in their channel of choice
$7
$10
$12
$15
67%
84%
55%
68%
2017 2019 2022 2023
2019 2023 2019 2023
International Consumer & SBS
Billed Business CAGR4
17% 18%
20%
22%
92
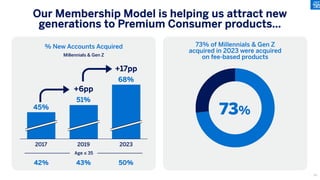
% New Accounts Acquired 73% of Millennials & Gen Z
acquired in 2023 were acquired
on fee-based products
Our Membership Model is helping us attract new
generations to Premium Consumer products…
Millennials & Gen Z
73%
2017 2019 2023
51%
68%
45%
+6pp
+17pp
42% 43% 50%
Age ≤ 35
93
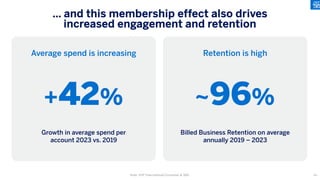
Average spend is increasing Retention is high
… and this membership effect also drives
increased engagement and retention
Note: AXP International Consumer & SBS.
~96%
+42%
Billed Business Retention on average
annually 2019 – 2023
Growth in average spend per
account 2023 vs. 2019
94
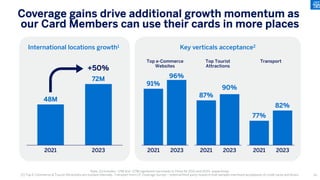
International locations growth1 Key verticals acceptance2
Note: (1) Includes ~17M and ~27M registered merchants in China for 2021 and 2023, respectively;
(2) Top E-Commerce & Tourist Attractions are tracked internally, Transport from LIF Coverage Survey – external third-party research that samples merchant acceptance of credit cards and Amex.
Coverage gains drive additional growth momentum as
our Card Members can use their cards in more places
48M
72M
91%
96%
87%
90%
77%
82%
2021 2023 2021 2023 2021 2023 2021 2023
+50%
Top e-Commerce
Websites
Top Tourist
Attractions
Transport
95
The International business has been a growth driver for American Express
Emerging from the pandemic, our investment in our products and Membership Model
re-established and strengthened our momentum
We have significant runway for growth and are set up to be accretive to the
Enterprise’s aspiration for 10%+ revenue growth
1
2
3
Key Takeaways
96
Opening
Remarks
How We
Will Achieve
Our Long-Term
Aspiration
Why Continue
to Invest
in American
Express?
Q&A
97
1
2
3
4
Expanding
network
coverage &
capabilities
Raymond Joabar
Group President,
Global Merchant &
Network Services
Premium growth through
our Membership Model
Howard Grosfield
Winning the SME recovery
Anna Marrs
Runway for growth in
International
Rafa Marquez
Expanding network
coverage & capabilities
Raymond Joabar
Efficiency, growth & service
through technology
Anré Williams
We have more than tripled the number of locations globally that accept American
Express since 2017 where Card Members live, work, and travel to most.
These coverage gains are driving scale and relevance and have been a significant
contributor to AXP’s revenue growth.
And tremendous opportunities remain to sustain this growth:
• Continue growing US acceptance as new businesses form or start accepting
card payments
• Accelerate International coverage through expansion of Partnerships
• Leverage our World Class Payment Ecosystem to deliver more value to Merchants,
Card Members & Partners
1
2
3
Key Takeaways
98
Today’s Focus
U.S. Merchant
Acceptance
International
Merchant
Acceptance
Network
Capabilities
Global Merchant
Journey
99
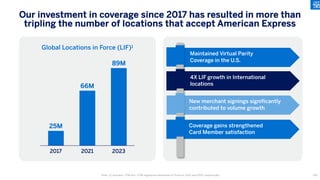
Our investment in coverage since 2017 has resulted in more than
tripling the number of locations that accept American Express
Note: (1) Includes ~17M and ~27M registered merchants in China for 2021 and 2023, respectively.
66M
25M
89M
2017 2023
2021
Global Locations in Force (LIF)1
Maintained Virtual Parity
Coverage in the U.S.
4X LIF growth in International
locations
New merchant signings significantly
contributed to volume growth
Coverage gains strengthened
Card Member satisfaction
100