BCG AI RADAR
FromPotential to
Profit: Closing the AI
Impact Gap
JANUARY 2025
2.
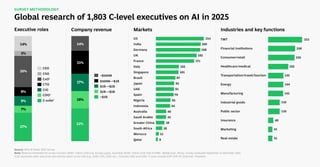
Global research of1,803 C-level executives on AI in 2025
Company revenue Markets Industries and key functions
Source: BCG AI Radar 2025 Survey
Note: Revenue thresholds for survey inclusion: $500+ million USD (US, Europe, Japan, Australia); $100+ million USD (rest of APAC, Middle East, Africa). Survey conducted September to December 2024.
1
CxO represents other executives who directly report to the CEO (e.g., CMO, CFO, COO, etc.). 2
Includes CDO and CAIO. 3
C-suite includes EVP, SVP, VP, Chairman, President.
C-suite3
CSO
CEO
CxO1
CTO
CIO
CDO2
>$5B
<$500M
$500M–<$1B
$1B–<$2B
$2B–<$5B
Executive roles
Energy
TMT
Industrial goods
Transportation/travel/tourism
Public sector
Financial institutions
Manufacturing
Insurance
Marketing
Healthcare/medical
Consumer/retail
Real estate
SURVEY METHODOLOGY
323
256
250
192
145
144
142
110
110
49
41
41
214
200
198
182
171
102
101
87
82
81
79
65
64
46
45
38
8
28
12
US
India
Germany
UK
France
Italy
Singapore
Brazil
Japan
UAE
Spain
Nigeria
Indonesia
Australia
Saudi Arabia
Greater China
Qatar
South Africa
Morocco
17%
16%
22%
14%
31%
5%
30%
8%
9%
7%
27%
14%
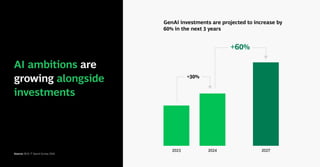
2023 2024 2027
+30%
+60%
AIambitions are
growing alongside
investments
Source: BCG IT Spend Survey 2024.
GenAI investments are projected to increase by
60% in the next 3 years
5.
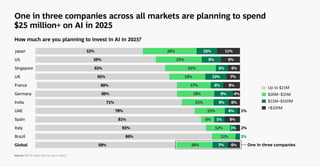
How much areyou planning to invest in AI in 2025?
Source: BCG AI Radar 2025 Survey (n=1,803).
One in three companies across all markets are planning to spend
$25 million+ on AI in 2025
Up to $25M
$26M–$50M
$51M–$100M
>$100M
53%
59%
63%
65%
69%
69%
71%
78%
81%
83%
86%
69%
26%
23%
25%
18%
17%
18%
15%
15%
6%
12%
12%
18%
10%
9%
6%
10%
6%
9% 4%
8%
6%
5%
3%
2%
7%
11%
9%
6%
7%
8%
6%
1%
8%
2%
6%
Germany
India
Japan
Spain
France
UK
Singapore
Italy
US
Brazil
Global One in three companies
UAE
6.
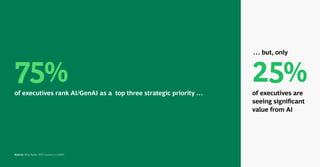
of executives rankAI/GenAI as a top three strategic priority …
75% of executives are
seeing significant
value from AI
25%
… but, only
Source: BCG Radar 2025 Survery (n=1,803).
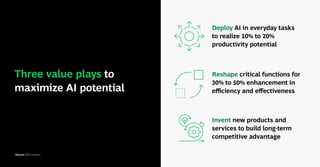
Three value playsto
maximize AI potential
Deploy AI in everyday tasks
to realize 10% to 20%
productivity potential
Reshape critical functions for
30% to 50% enhancement in
efficiency and effectiveness
Invent new products and
services to build long-term
competitive advantage
Source: BCG analysis.
9.
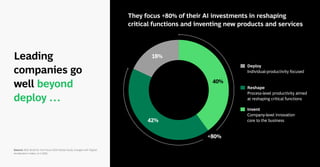
Leading
companies go
well beyond
deploy…
Source: BCG Build for the Future 2024 Global Study (merged with Digital
Acceleration Index), (n=1,000).
They focus +80% of their AI investments in reshaping
critical functions and inventing new products and services
40%
42%
+80%
18%
Deploy
Individual-productivity focused
Reshape
Process-level productivity aimed
at reshaping critical functions
Invent
Company-level innovation
core to the business
10.
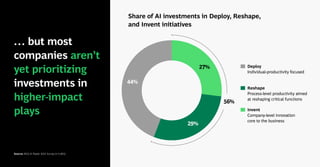
… but most
companiesaren’t
yet prioritizing
investments in
higher-impact
plays
Source: BCG AI Radar 2025 Survey (n=1,803).
Share of AI investments in Deploy, Reshape,
and Invent initiatives
27%
29%
44%
Deploy
Individual-productivity focused
Reshape
Process-level productivity aimed
at reshaping critical functions
Invent
Company-level innovation
core to the business
56%
11.
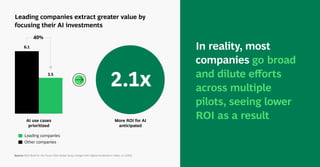
AI use cases
prioritized
Source:BCG Build for the Future 2024 Global Study (merged with Digital Acceleration Index), (n=1,000).
Leading companies extract greater value by
focusing their AI investments
Other companies
Leading companies
6.1
3.5
More ROI for AI
anticipated
In reality, most
companies go broad
and dilute efforts
across multiple
pilots, seeing lower
ROI as a result
2.1x
40%
12.
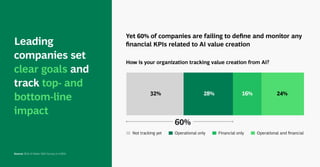
Yet 60% ofcompanies are failing to define and monitor any
financial KPIs related to AI value creation
How is your organization tracking value creation from AI?
Leading
companies set
clear goals and
track top- and
bottom-line
impact
Source: BCG AI Radar 2025 Survey (n=1,803).
32% 28% 16% 24%
Not tracking yet Operational only Financial only Operational and financial
60%
13.
Source: BCG AIRadar 2025 Survey (n=1,803).
Note: AI talent refers to AI specialists (i.e., data scientists, ML ops engineers) and non–specialists (i.e., upskilled talent leveraging AI tools).
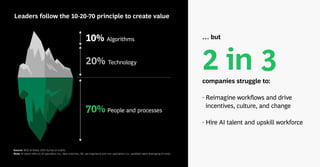
Leaders follow the 10-20-70 principle to create value
10% Algorithms
20% Technology
70% People and processes
companies struggle to:
· Reimagine workflows and drive
incentives, culture, and change
· Hire AI talent and upskill workforce
2 in 3
… but
14.
Source: BCG AIRadar 2025 Survey (n=1,803).
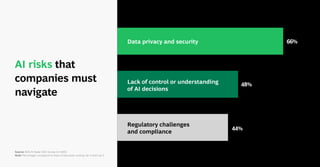
Note: Percentages correspond to share of executives ranking risk in their top 3.
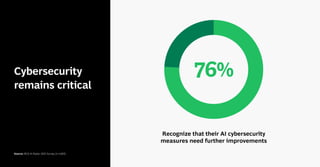
AI risks that
companies must
navigate
66%
48%
44%
Data privacy and security
Lack of control or understanding
of AI decisions
Regulatory challenges
and compliance
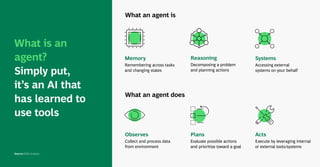
What an agentis
What an agent does
What is an
agent?
Simply put,
it’s an AI that
has learned to
use tools
Source: BCG Analysis
Memory
Remembering across tasks
and changing states
Reasoning
Decomposing a problem
and planning actions
Systems
Accessing external
systems on your behalf
Observes
Collect and process data
from environment
Plans
Evaluate possible actions
and prioritize toward a goal
Acts
Execute by leveraging internal
or external tools/systems
18.
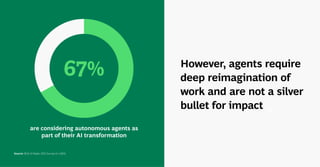
15%
67%
are considering autonomousagents as
part of their AI transformation
Source: BCG AI Radar 2025 Survey (n=1,803).
However, agents require
deep reimagination of
work and are not a silver
bullet for impact
19.
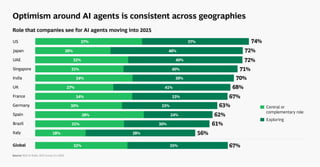
Role that companiessee for AI agents moving into 2025
Source: BCG AI Radar 2025 Survey (n=1,803).
Optimism around AI agents is consistent across geographies
Central or
complementary role
Exploring
Germany
India
Japan
Spain
France
UK
Singapore
Italy
US
Brazil
Global
UAE
37%
26%
32%
31%
34%
27%
34%
30%
38%
31%
18%
32%
37%
46%
40%
40%
36%
41%
33%
33%
24%
30%
38%
35%
74%
72%
72%
71%
70%
68%
67%
67%
63%
62%
61%
56%
20.
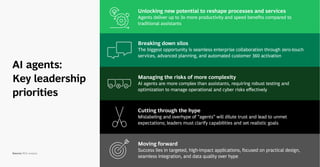
AI agents:
Key leadership
priorities
Unlockingnew potential to reshape processes and services
Agents deliver up to 3x more productivity and speed benefits compared to
traditional assistants
Breaking down silos
The biggest opportunity is seamless enterprise collaboration through zero-touch
services, advanced planning, and automated customer 360 activation
Managing the risks of more complexity
AI agents are more complex than assistants, requiring robust testing and
optimization to manage operational and cyber risks effectively
Cutting through the hype
Mislabeling and overhype of “agents” will dilute trust and lead to unmet
expectations; leaders must clarify capabilities and set realistic goals
Moving forward
Success lies in targeted, high-impact applications, focused on practical design,
seamless integration, and data quality over hype
Source: BCG analysis.
21.
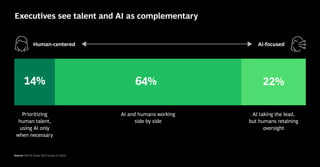
With AI agentson the rise, who will hold
the power: humans or AI?
22.
Source: BCG AIRadar 2025 Survey (n=1,803).
Executives see talent and AI as complementary
22%
64%
14%
Prioritizing
human talent,
using AI only
when necessary
AI taking the lead,
but humans retaining
oversight
AI and humans working
side by side
Human-centered AI-focused
23.
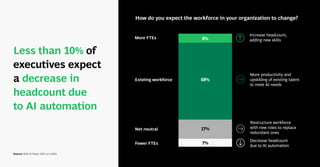
Less than 10%of
executives expect
a decrease in
headcount due
to AI automation
Source: BCG AI Radar 2025 (n=1,803).
8%
68%
17%
7%
More FTEs
Existing workforce
Net neutral
Fewer FTEs
Increase headcount,
adding new skills
More productivity and
upskilling of existing talent
to meet AI needs
Decrease headcount
due to AI automation
How do you expect the workforce in your organization to change?
Restructure workforce
with new roles to replace
redundant ones
24.
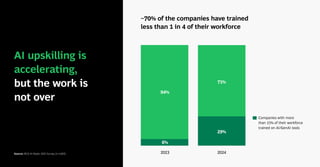
AI upskilling is
accelerating,
butthe work is
not over
Source: BCG AI Radar 2025 Survey (n=1,803).
~70% of the companies have trained
less than 1 in 4 of their workforce
6%
94%
71%
29%
2023 2024
Companies with more
than 25% of their workforce
trained on AI/GenAI tools
25.
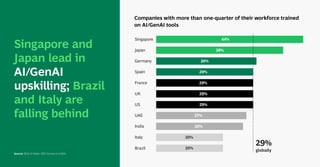
Singapore and
Japan leadin
AI/GenAI
upskilling; Brazil
and Italy are
falling behind
Source: BCG AI Radar 2025 Survey (n=1,803).
38%
Japan
30%
Germany
29%
Spain
29%
France
Singapore 44%
29%
US
27%
UAE
26%
India
20%
Italy
20%
Brazil
29%
UK
29%
globally
Companies with more than one-quarter of their workforce trained
on AI/GenAI tools
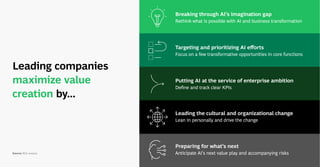
Leading companies
maximize value
creationby...
Breaking through AI’s imagination gap
Rethink what is possible with AI and business transformation
Targeting and prioritizing AI efforts
Focus on a few transformative opportunities in core functions
Putting AI at the service of enterprise ambition
Define and track clear KPIs
Leading the cultural and organizational change
Lean in personally and drive the change
Preparing for what’s next
Anticipate AI’s next value play and accompanying risks
Source: BCG analysis.
 Most read
 Most read