Download to read offline
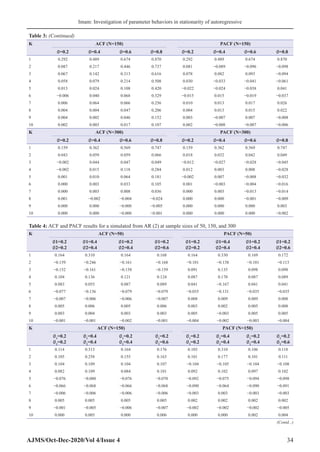
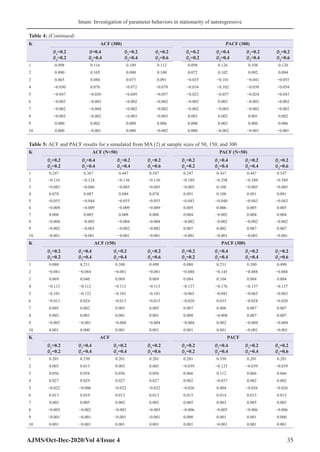
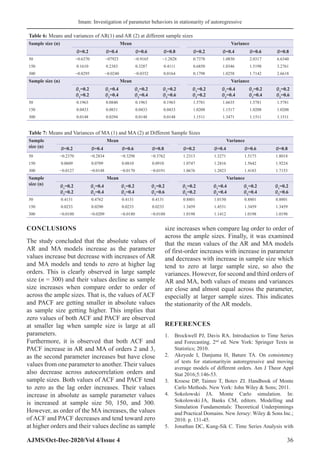
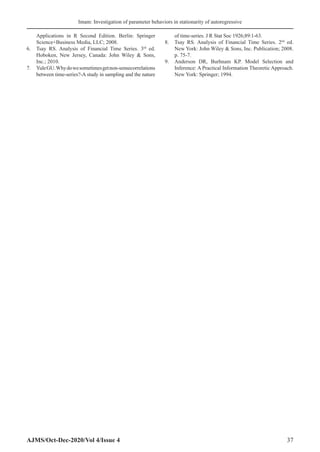

The document describes a study that investigated parameter behaviors related to stationarity in autoregressive (AR) and moving average (MA) models through simulations. The study conducted simulations using R at different parameter orders (p for AR, q for MA) and sample sizes. It analyzed properties like the mean, variance, autocorrelation function (ACF), and partial autocorrelation function (PACF). The study found that the ACF and PACF values increased with higher parameter values but decreased with higher orders, eventually tending to zero at larger lags. It also observed that means and variances declined with increasing sample size.


